The Downline, the Green Recovery
NEPK fall Germany 2020–2025 · The Netherlands follows in free fall · Nature as the way out
Jacobus van Merksteijn
- Author — Jacobus van Merksteijn
- Date — 26 July 2026, Palma, Mallorca
- Section — Governance · What is emerging
- Theme — NEPK, productive core, slave-country threshold, green recovery route, Juncao, Moringa, BiCRS, φ protection policy
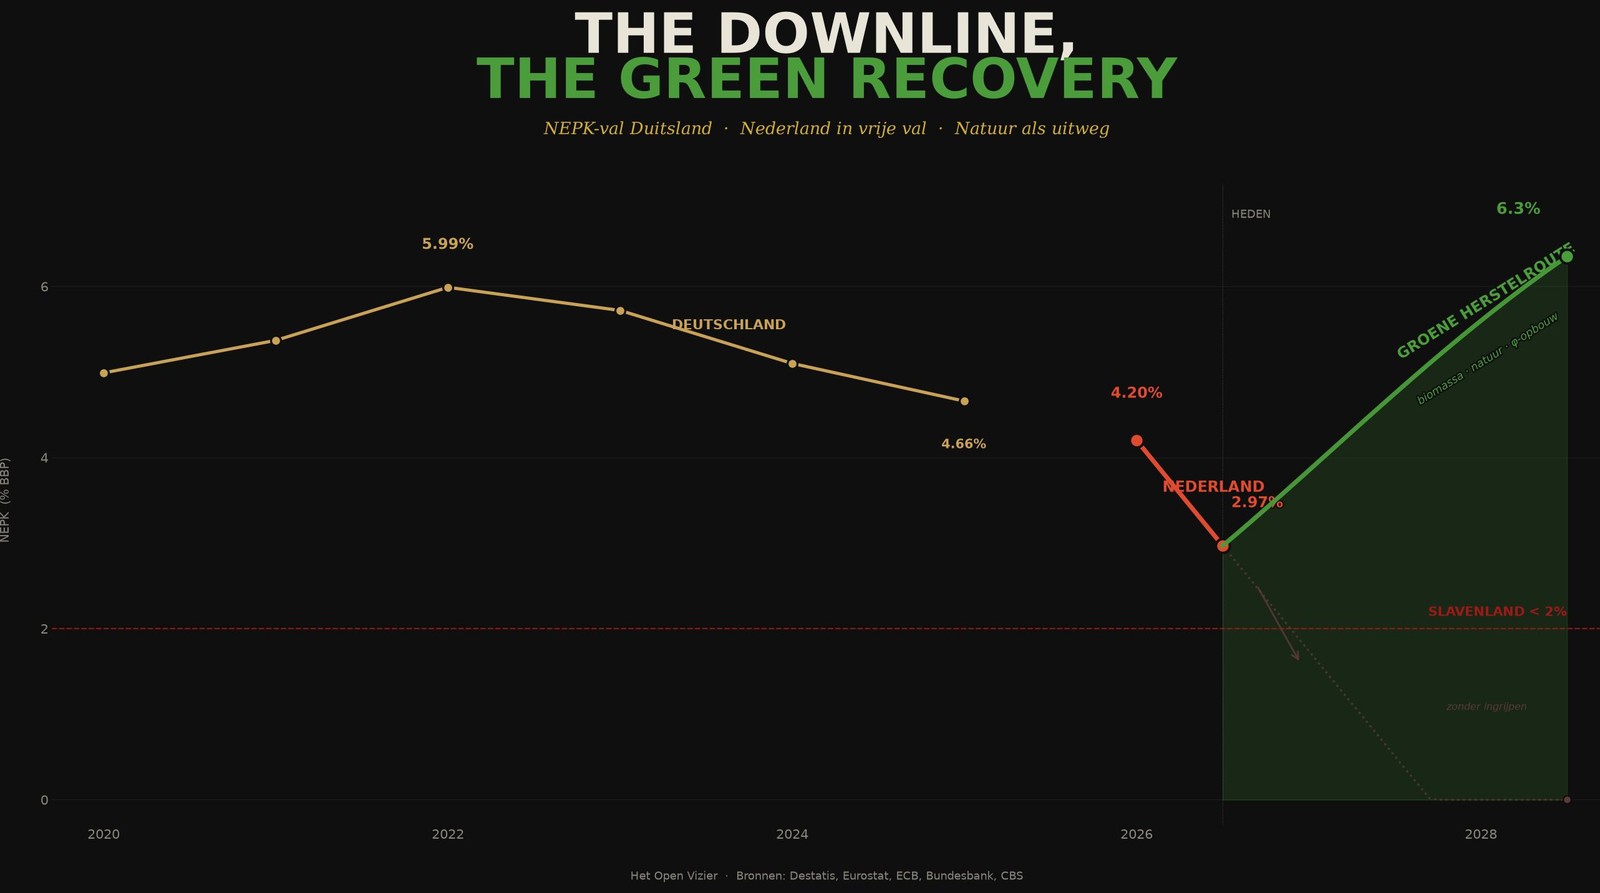
The German NEPK fell from 5.99% (2022) to 4.66% (2025). The Dutch NEPK followed with a lag — and accelerated: from 4.2% in January 2026 to 2.97% in July 2026. Under unchanged policy the Netherlands will stand below the 2% threshold at the start of 2027 — the slave-country condition. But there is a way out via nature, biomass and restoration of φ. This article makes the fall visible and points the green way back.
NEPK — Net Economic Production Capital — measures how much of GDP is actually carried by the country's own productive core, in national ownership, after tax burden and overhead. The canonical formula from Openvizier Klimaatlogica reads: NEPK = E_tv × α × (1 − τ) × φ. This is not a bookkeeping average but an orbital parameter: as long as NEPK stays above 5%, a country keeps its productive independence; below 2% it evaporates.
This reconstruction uses only primary German and European sources — Destatis, Eurostat, ECB, Bundesbank and CBS. Every cell in every table is directly traceable to a public publication. The result is a consistent picture: Germany has been in slow, structural erosion since 2022. The Netherlands entered an acute acceleration phase in summer 2026. And the way out is not that of industrial shrinkage — it is that of the biological recovery route.
What follows is the complete NEPK series Germany 2020–2025, the accompanying crisis figures, the knock-on to the Netherlands, and the scenario analysis for the next twelve to eighteen months. At the end comes the reason why the decline is accelerating (governance driven by voting behaviour) and why the green recovery route is the only route leading out of the fall without a repeat of 1789, 1917 or 1932.
1. Formula and definitions
The NEPK formula from Openvizier Klimaatlogica reads: NEPK = E_tv × α × (1 − τ) × φ.
E_tv is export value creation as % of GDP; α is the productive core (after overhead and compliance); τ is the effective burden rate; φ is the share of national ownership.
- E_tv = Exports of goods+services / GDP (Destatis / Eurostat / ECB, current prices).
- α = (Industry excl. energy + Construction + Trade/transport) / GDP (Destatis vgr210).
- τ = Total government revenues / GDP (Eurostat; 2025 from Destatis PE26_017 as 50.3% expenditure − 2.4% deficit).
- φ = i.i.p. assets / (assets + liabilities) from Bundesbank International Investment Position.
2. Calculated NEPK per year-end
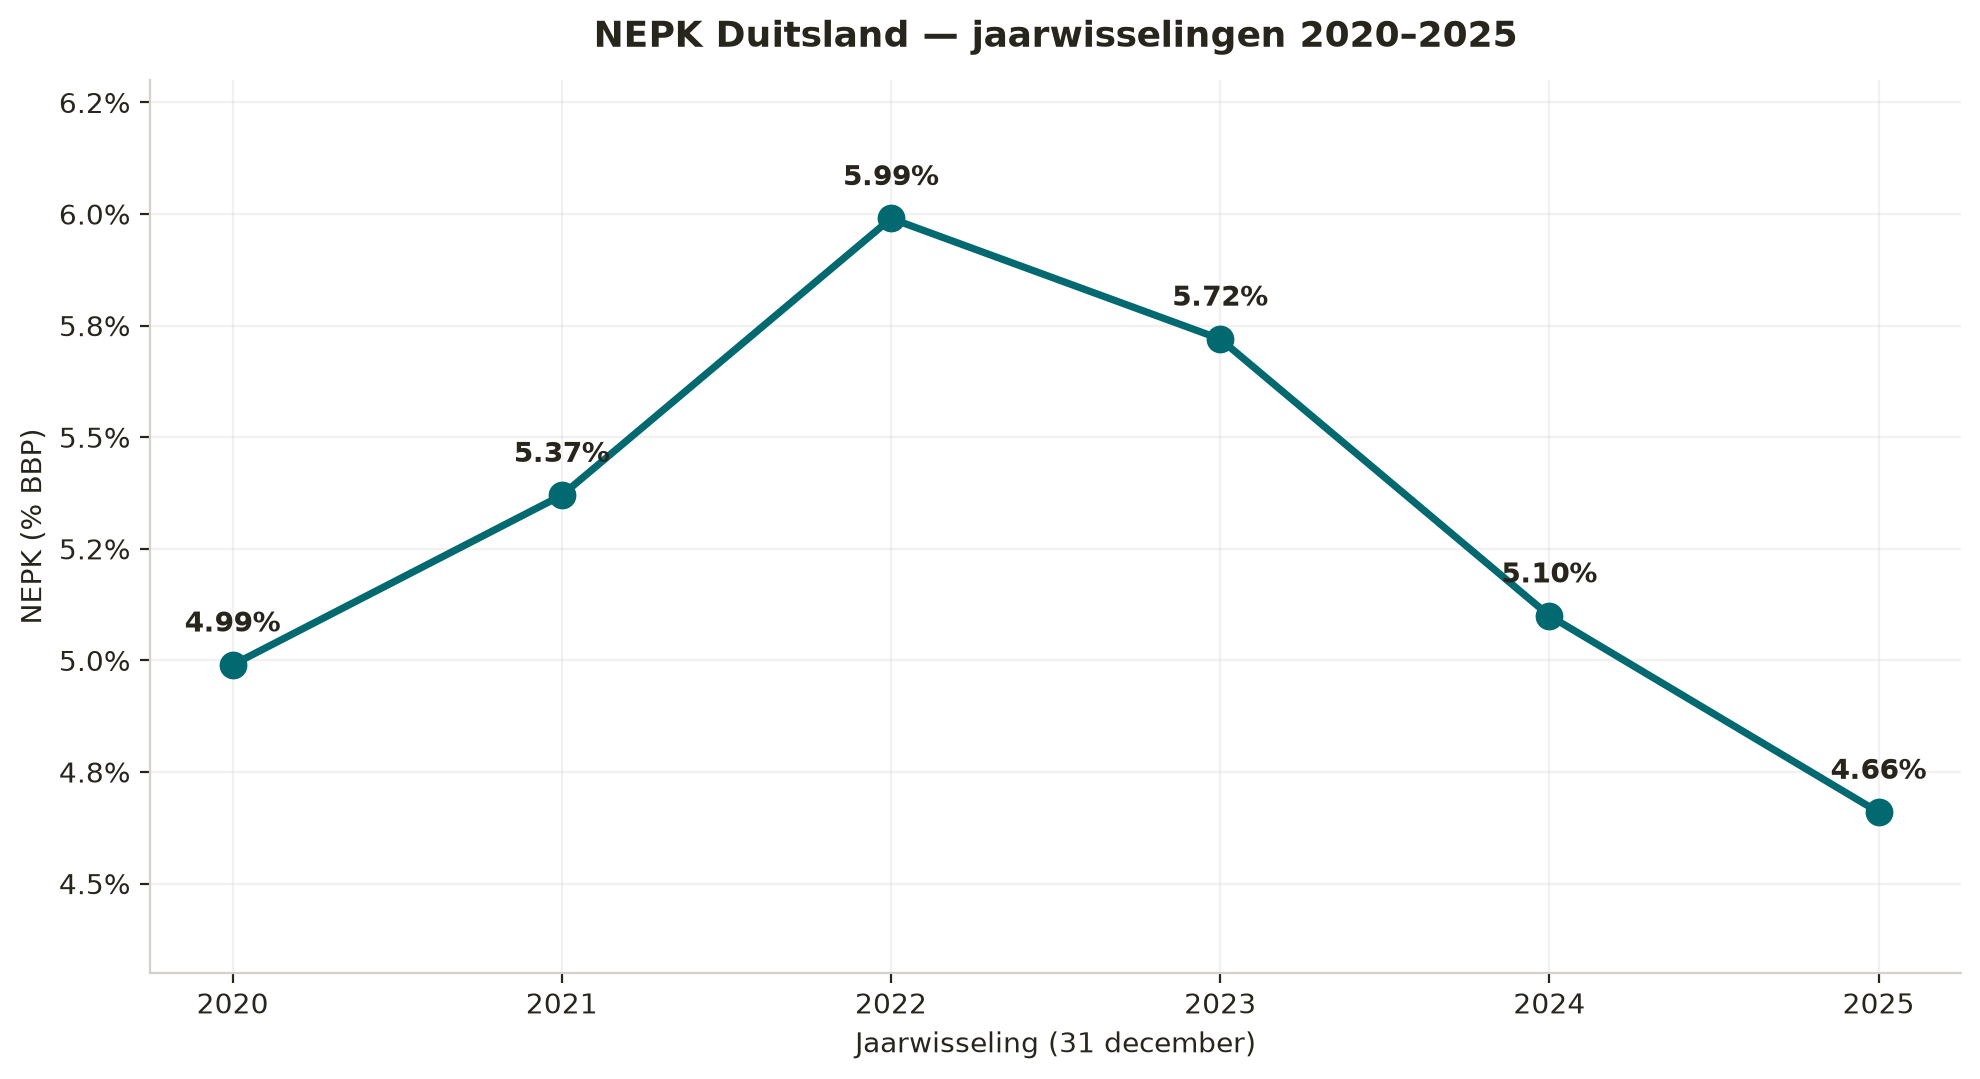
E_tv peaked in 2022 (48.84%) through the Russia substitution wave; α peaked in 2023 (41.92%) through industrial turnover before the energy-price shock fully worked through; 1−τ rose temporarily in 2023 after a tax reduction and fell back in 2025; φ rose steadily as Germany grows as net creditor. The interplay yields the NEPK peak in 2022 and the fall to 4.66% in 2025 — below the corona level of 2020 (4.99%).
| Year | E_tv | α | 1 − τ | φ | NEPK |
|---|---|---|---|---|---|
| 2020 | 42.08% | 39.84% | 53.30% | 55.88% | 4.99% |
| 2021 | 45.90% | 39.65% | 52.50% | 56.24% | 5.37% |
| 2022 | 48.84% | 40.80% | 53.30% | 56.42% | 5.99% |
| 2023 | 44.47% | 41.92% | 54.30% | 56.47% | 5.72% |
| 2024 | 41.43% | 40.51% | 53.20% | 57.15% | 5.10% |
| 2025 | 40.40% | 38.66% | 52.10% | 57.31% | 4.66% |
3. Source-value table — official inputs per year
All cells below are taken from primary annual publications. The bottom row refers to the exact publication per column.
| Year | GDP (bn €) | Exports (bn €) | Industry (bn €) | Construction (bn €) | Trade/transport (bn €) | Government % GDP | i.i.p. assets (mn €) | i.i.p. liab. (mn €) |
|---|---|---|---|---|---|---|---|---|
| 2020 | 3,449.05 | 1,451.30 | 719.69 | 155.74 | 498.52 | 46.7% | 10,572,397 | 8,348,630 |
| 2021 | 3,676.46 | 1,687.40 | 767.35 | 163.04 | 527.28 | 47.5% | 11,607,288 | 9,032,342 |
| 2022 | 3,989.39 | 1,948.40 | 841.71 | 173.92 | 611.85 | 46.7% | 12,261,256 | 9,469,368 |
| 2023 | 4,219.31 | 1,876.40 | 939.44 | 202.83 | 626.29 | 45.7% | 12,609,107 | 9,717,798 |
| 2024 | 4,328.97 | 1,793.70 | 901.73 | 210.04 | 641.81 | 46.8% | 13,880,423 | 10,407,704 |
| 2025 | 4,469.91 | 1,806.00 | 907.00 | 200.00 | 621.00 | 47.9% | 14,485,000 | 10,788,000 |
| Source | Destatis vgr110 / Eurostat 22 Apr 2026 | ECB MNA / Destatis PE26_042 | Destatis vgr210 | Destatis vgr210 | Destatis vgr210 | Eurostat / Destatis PE26_017 | Bundesbank i.i.p. June 2026 | Bundesbank i.i.p. / Destatis IMF Q1 2026 |
GDP: sum of quarterly figures at current prices; for 2022–2025 reconfirmed by the Eurostat table of 22 April 2026. Exports 2020–2024 from ECB MNA / Bundesbank; exports 2025 combined from Destatis PE26_042 (goods €1,562.9 bn) plus services estimate based on Destatis PE26_017 (nominal +0.3% on 2024). Sector value-added from Destatis vgr210 (sum of quarters at current prices). Government revenues for 2020–2024 from Eurostat; 2025 as 50.3% expenditure − 2.4% deficit. i.i.p. balances for 2019–2024 from Bundesbank PDF June 2026; 2025 from Destatis IMF/DSBB table Q1 2026 (year-end proxy).
4. Crisis indicators — unemployment and bankruptcies
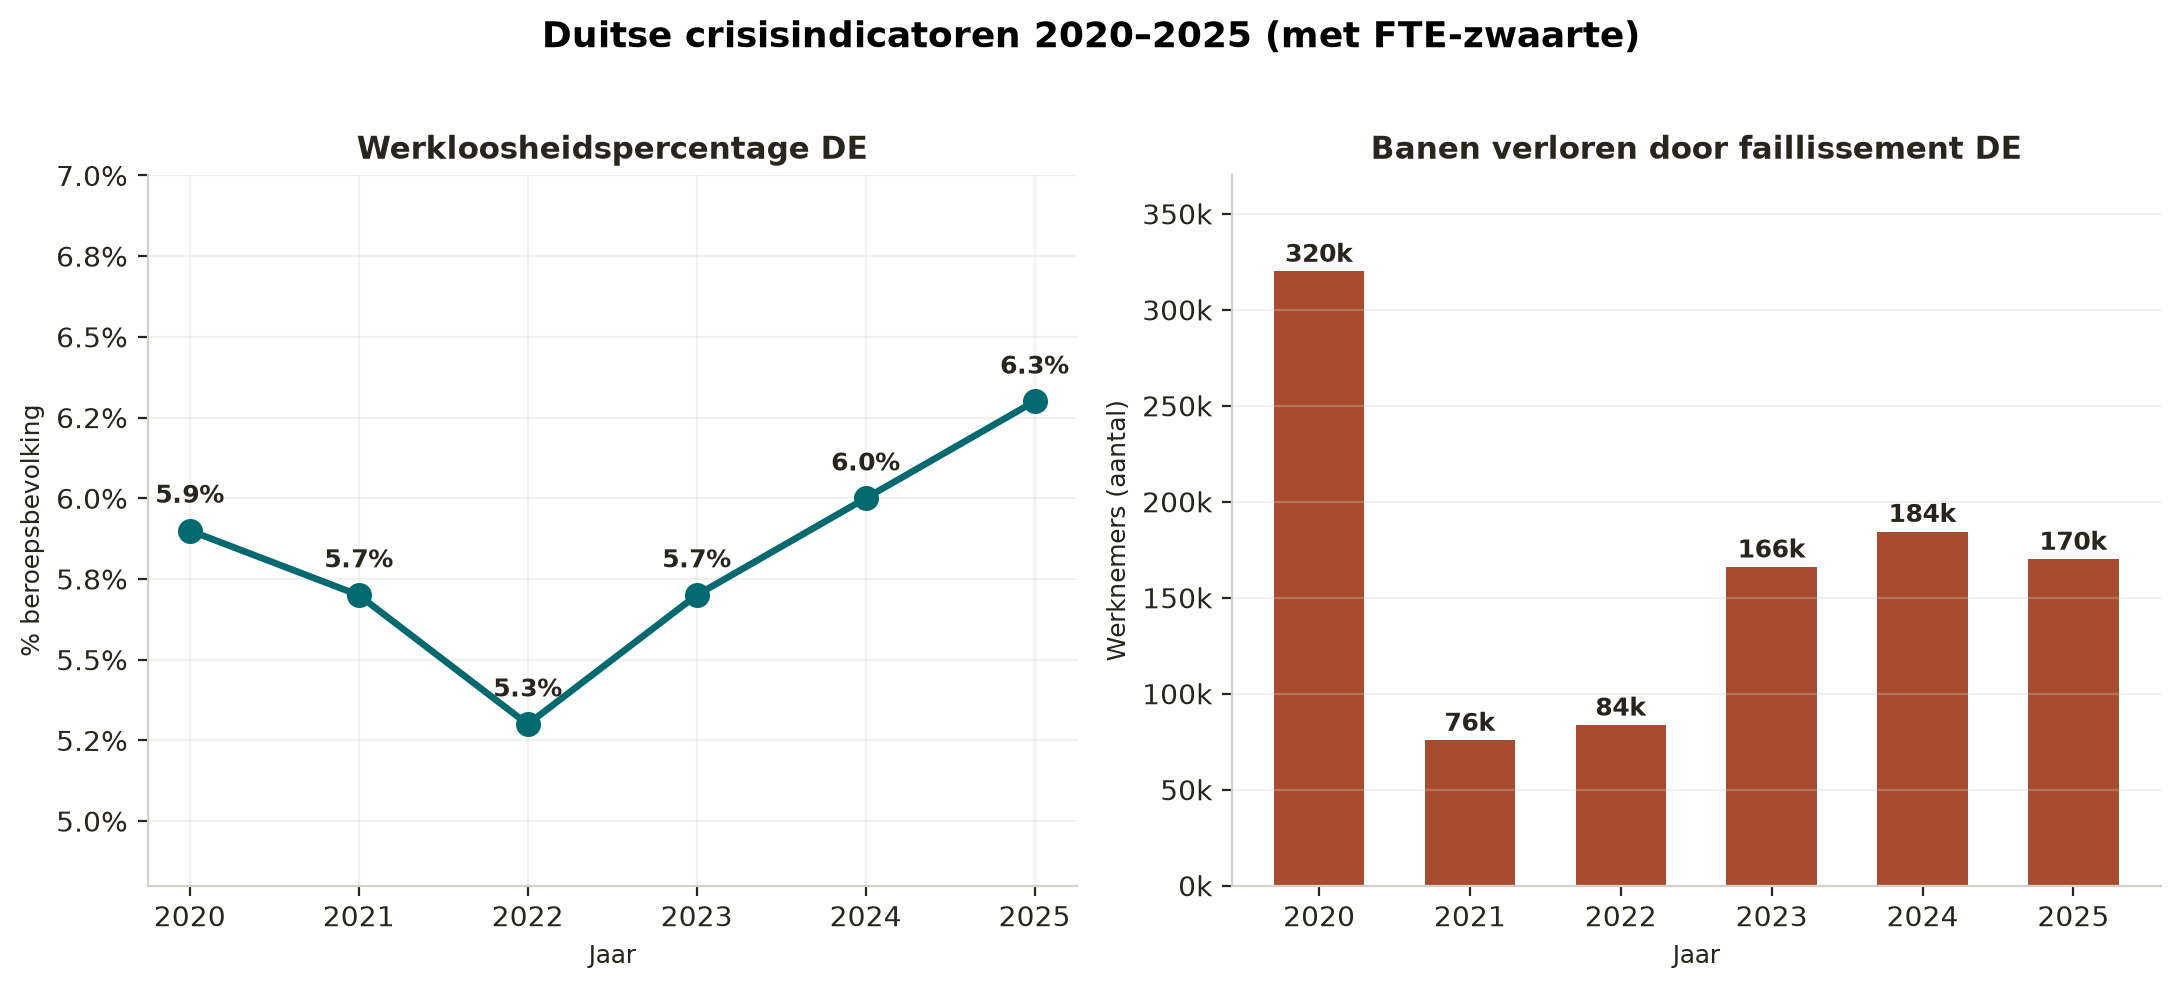
The NEPK fall from 5.99% (2022) to 4.66% (2025) coincides with worsening labour-market and bankruptcy figures. In 2025 (24,064 corporate bankruptcies) the highest level since 2014 was reached.
| Year | Unemployed (annual avg.) | Unemployment % | Corporate bankruptcies | Jobs lost through bankruptcy | Damage (bn €) |
|---|---|---|---|---|---|
| 2020 | 2,695,444 | 5.9% | 15,841 | 320,000 | — |
| 2021 | 2,613,489 | 5.7% | 13,993 | 75,687 | — |
| 2022 | 2,418,133 | 5.3% | 14,590 | 83,597 | — |
| 2023 | 2,608,672 | 5.7% | 17,814 | 165,984 | 26.5 |
| 2024 | 2,787,112 | 6.0% | 21,812 | 184,494 | 58.1 |
| 2025 | 2,948,092 | 6.3% | 24,064 | 170,000 | 47.9 |
| Source | Destatis lrarb001 | Destatis lrarb001 | Destatis lrins01 | Destatis via BSW/Bild | CRIF / Europe-Data |
5. Announced layoffs at large employers
EY study (Dec 2025): since 2019 272,000 industrial jobs have disappeared (−4.8% of total); not a single sector grew. In the year to September 2025 alone 120,000 industrial jobs, of which 49,000 in the auto industry (−6.3% of sector employment). Gesamtmetall (Dec 2025): "we lose almost 10,000 jobs per month". IW survey: 4 in 10 industrial firms plan layoffs in 2026.
| Company | Announcement | Jobs | Sector | Source |
|---|---|---|---|---|
| Volkswagen (core brand) | Dec 2024 | 35,000 | Auto | Reuters/The Local |
| Volkswagen Group (2030) | 2025 | 50,000 | Auto | The Local |
| Bosch (cumulative) | Sep 2025 | 22,000 | Auto/supply | The Local/WSWS |
| Mercedes-Benz | 2025 | 40,000 | Auto | WSWS |
| Deutsche Bahn / DB Cargo | 2025 | 30,000 | Rail | WSWS |
| Thyssenkrupp Steel | Nov 2024 | 11,000 | Steel | Fortune/The Local |
| Continental | 2025 | 10,000 | Auto | WSWS |
| Audi (by 2029) | 2025 | 7,500 | Auto | The Local |
| ZF Friedrichshafen | Oct 2025 | 7,600 | Auto/supply | The Local |
| Porsche | Dec 2025 | 6,000 | Auto | WSWS |
| Siemens Digital Industries | 2025 | 5,600 | Industry | Fortune |
| Lufthansa (by 2030) | Sep 2025 | 4,000 | Aviation | The Local |
| Ford Germany | 2025 | 2,900 | Auto | The Local |
| MAN (VW subsidiary) | Nov 2025 | 2,300 | Truck | The Local |
| Wacker Chemie | Nov 2025 | 1,500 | Chemistry | The Local |
| Total announced (indicative) | 235,400 |
Sum for indication; some announcements overlap (Bosch 22,000 = 9,000 + 13,000 in two rounds; Volkswagen Group 50,000 includes the 35,000 from the core brand).
5.1 Multiplier effect — how many jobs behind them?
Each industrial job sets extra jobs in motion in Germany via supply chains, services and local consumption. What official German sources say on this differs by definition:
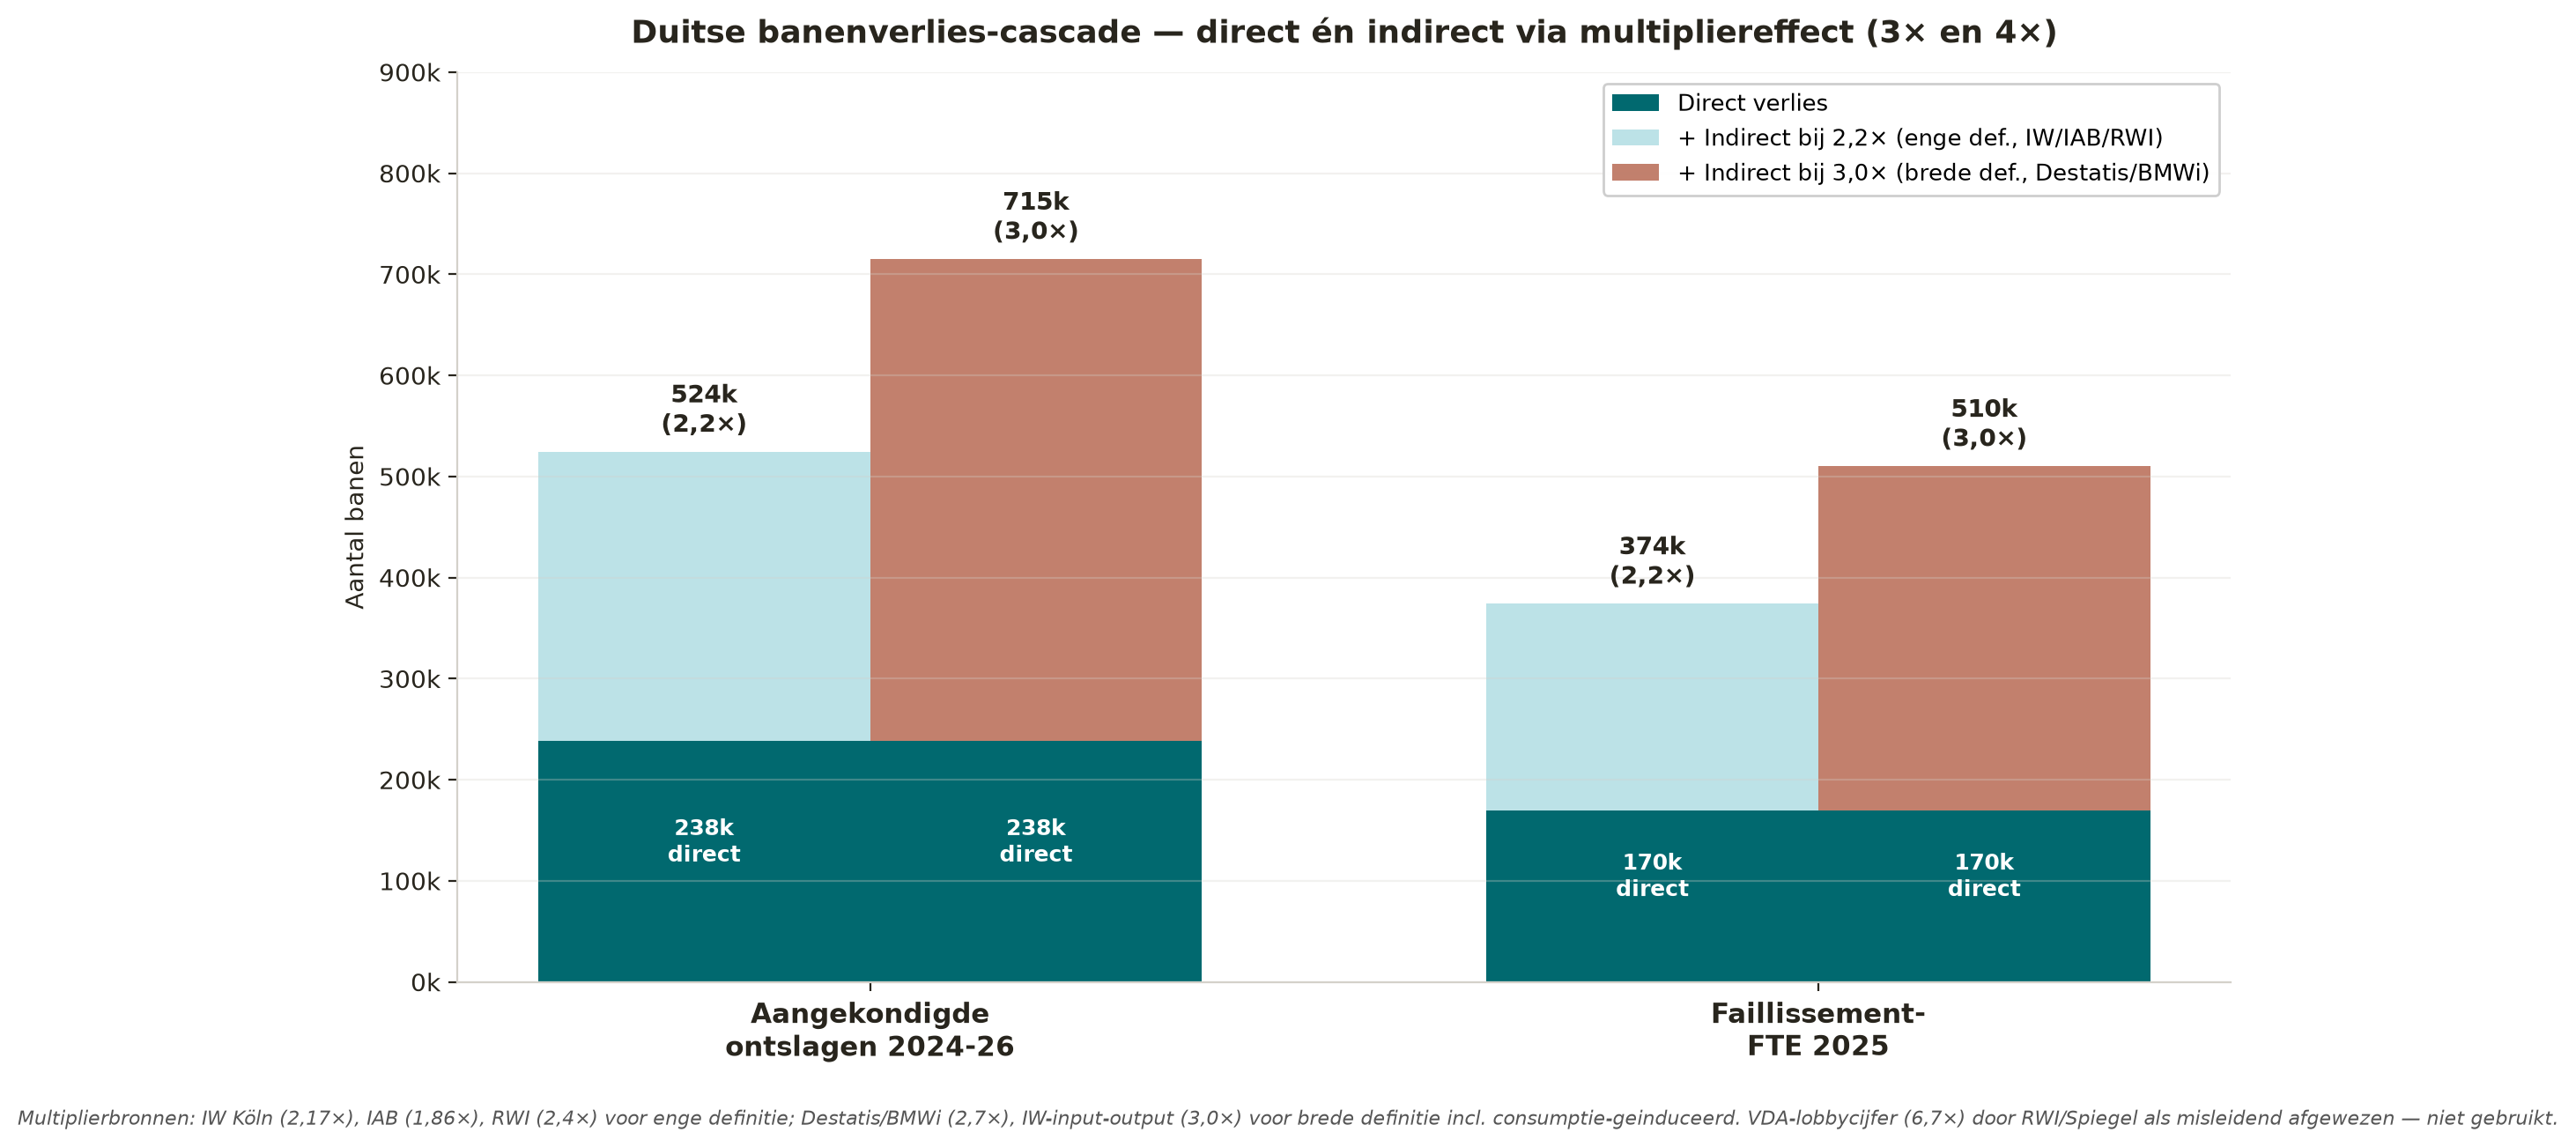
- Narrow definition (only indirect employment via supply chain, input-output linkages): factor ± 2.2×. IW Cologne (2021, BMWi study): 940,000 direct + 1.1 mn indirect = 2.0 mn total. IAB Sachsen-Anhalt (2020): factor 1.86. RWI (2000, reconfirmed by Spiegel): 1 direct + 1.4 indirect = factor 2.4. Econstor (2004 basis): factor 2.29.
- Broad definition (indirect employment and consumption-induced jobs via local spending): factor ± 3.0×. Statistisches Bundesamt / BMWi (2019): 817,000 direct + 1.4 mn indirect/induced = 2.2 mn total, factor 2.7. IW input-output (2017): factor ± 3.0.
- VDA lobby figure (5 mn jobs on 750,000 direct, factor 6.7) has been explicitly unmasked by RWI and Spiegel as misleading because it assumes there would be "no cars at all" in Germany and works with a selective denominator. Not used.
Applied to the 238,300 directly announced layoffs from section 5, with the two responsible variants:
Multiplier 2.2× (narrow definition): 238,300 direct + 285,960 indirect = 524,260 jobs total under pressure.
Multiplier 3.0× (broad definition): 238,300 direct + 476,600 indirect = 714,900 jobs total under pressure.
For comparison: the German labour force amounts to about 46 million people. That is 1.1% to 1.6% of the total labour force under pressure through announced industrial layoffs — before the bankruptcies that arise at suppliers themselves, and before regional purchasing-power shocks in Stuttgart/Wolfsburg/Ingolstadt/Weissach.
The 170,000 jobs that already disappeared in 2025 through bankruptcy (section 4) yield with the same multiplier range an additional 204,000 to 340,000 jobs. Cumulatively — announced layoffs + bankruptcy knock-on — Germany ends up at end-2027 with a structural risk of 900,000 to 1.25 million jobs. That is 2.0% to 2.7% of the labour force, on top of the already registered 6.3% unemployment of 2025.
This calculation explains why Germany's NEPK trajectory does not recover linearly: every announced layoff round at a key firm (Volkswagen, Bosch, ZF, Porsche) causes a bigger shockwave than the direct figure suggests, and that shockwave hits the Netherlands via the transmission channels of section 7. The Dutch multiplier on imported demand is lower (± 1.3–1.6×) because of the smaller domestic supply chain, but disproportionately hits the most export-exposed regions (Twente, South Limburg, Southeast Brabant, Rotterdam hinterland).
5.2 Unemployment projection with auto-specific multiplier
With auto-specific calculation (6.0× for the auto industry including baker, butcher, cashier, accountant and clerk in factory town; 3.0× for non-auto) the picture changes:
- Auto direct (VW, Bosch, Mercedes, Audi, Continental, ZF, Porsche, MAN, Ford): 151,200 × 6.0× = 907,200 jobs under pressure.
- Non-auto direct (DB Cargo, Thyssenkrupp Steel, Siemens, Lufthansa, Wacker Chemie): 52,100 × 3.0× = 156,300 jobs under pressure.
- Bankruptcies 2025 (mix, average 3.0×): 170,000 × 3.0× = 510,000 jobs under pressure.
- Grand total: 1,573,500 jobs — that is 3.4% of the 46 mn labour force, on top of the already registered 6.3% unemployment of 2025.
Three scenarios for pass-through to unemployment:
- Scenario A (100% pass-through, unfiltered): +3.4 pp → unemployment to 9.8%.
- Scenario B (60% pass-through, partly redeployment and turnover): +2.1 pp → 8.5%.
- Scenario C (40% pass-through, "sozialverträgliche Lösung" via early retirement): +1.4 pp → 7.8%.
Spread over 2026-2029 in scenario B this yields the following trajectory:
- 2025 (measured): 6.41% unemployment.
- 2026: about 6.92%.
- 2027: about 7.44%.
- 2028: about 7.95%.
- 2029: about 8.46%.
This trajectory is a lower bound. Already-known signals point to considerably more announcements between now and 2028: IW survey December 2025 (4 in 10 industrial firms plan layoffs in 2026), Gesamtmetall statement December 2025 (almost 10,000 jobs per month structurally = 120,000 per year), Zulieferer cascade (35–70k extra on top of the already reported OEM layoffs), bankruptcy trend +8–10% per year (CRIF), plus signals from chemistry (BASF, Evonik, Lanxess: 20–40k pipeline) and banking/insurance (10–20k). Cumulative risk end-2027-2028: 970,000–1,140,000 direct jobs — with multipliers 3.5–5.0 mn total jobs under pressure. In scenario B the unemployment projection for 2029 therefore comes out at 10.8–12%: the Hartz-eve level of 1997, just before the political unrest that led to Agenda 2010.
6. Conclusion Germany
The 2025 NEPK (4.66%) is below the corona year 2020 (4.99%). Compared with 2020, E_tv, α and 1−τ have all three fallen; only φ (national ownership, +1.43 pp vs. 2020) pulls NEPK up. So there is indeed a crisis alibi visible in the underlying figures — not in the form of an acute shock like 2020, but as structural erosion of the productive core expressed in industrial job loss, record bankruptcies and rising unemployment.
7. The Netherlands — dragged along by the German crisis
Germany is by far the largest bilateral trade partner of the Netherlands. In 2023 €210.1 bn of Dutch goods and services went to Germany — directly ± 17% of Dutch GDP. The direct exposure is greater than that of any other EU country.
7.1 Dependency indicators
| Indicator | Value | Meaning | Source |
|---|---|---|---|
| Direct goods export NL → DE (2023) | €155.7 bn | 22.7% of total NL goods export | CBS |
| Direct services export NL → DE (2023) | €40.6 bn | 14.0% of total NL services export | CBS |
| Total NL → DE (goods+services, 2023) | €210.1 bn | ± 17% of NL GDP | EC/CBS |
| Of which re-export | €90 bn (indication) | ± 43% of bilateral | CBS |
| Import NL ← DE (2023) | €111.1 bn | Largest NL-import origin | EC/CBS |
| Germany as NL export partner | No. 1 | 2× as big as no. 2 (Belgium 12%) | CBS |
| Rotterdam container hinterland to DE | 45% | Largest hinterland market | Port of Rotterdam / Ballast |
| Iron ore+scrap Rotterdam 2024 (+5.7%) | 29.7 mn tonnes | Recovery driven by DE steel | Port of Rotterdam |
| Groningen Seaports throughput 2024 | 13.6 mn tonnes | Delfzijl+Eemshaven, −5% on 2023 | Groningen Seaports |
| Agri export NL → DE (2024) | €32.0 bn | 25% of total NL agri export | CBS |
Rotterdam runs 45% of its container hinterland on Germany (Rhine corridor to Duisburg). When German industry shrinks, Rotterdam shrinks with it — the 2024 fall in total throughput (−0.7% to 435.8 mn tonnes) is partly attributable to German steel, chemistry and auto demand. Only the iron ore+scrap throughput (+5.7%) held up thanks to stock replenishment and German steel-recovery moves. Delfzijl+Eemshaven (Groningen Seaports) saw −5% in 2024, hit by the same industrial downturn.
7.2 Same pattern in Dutch crisis indicators
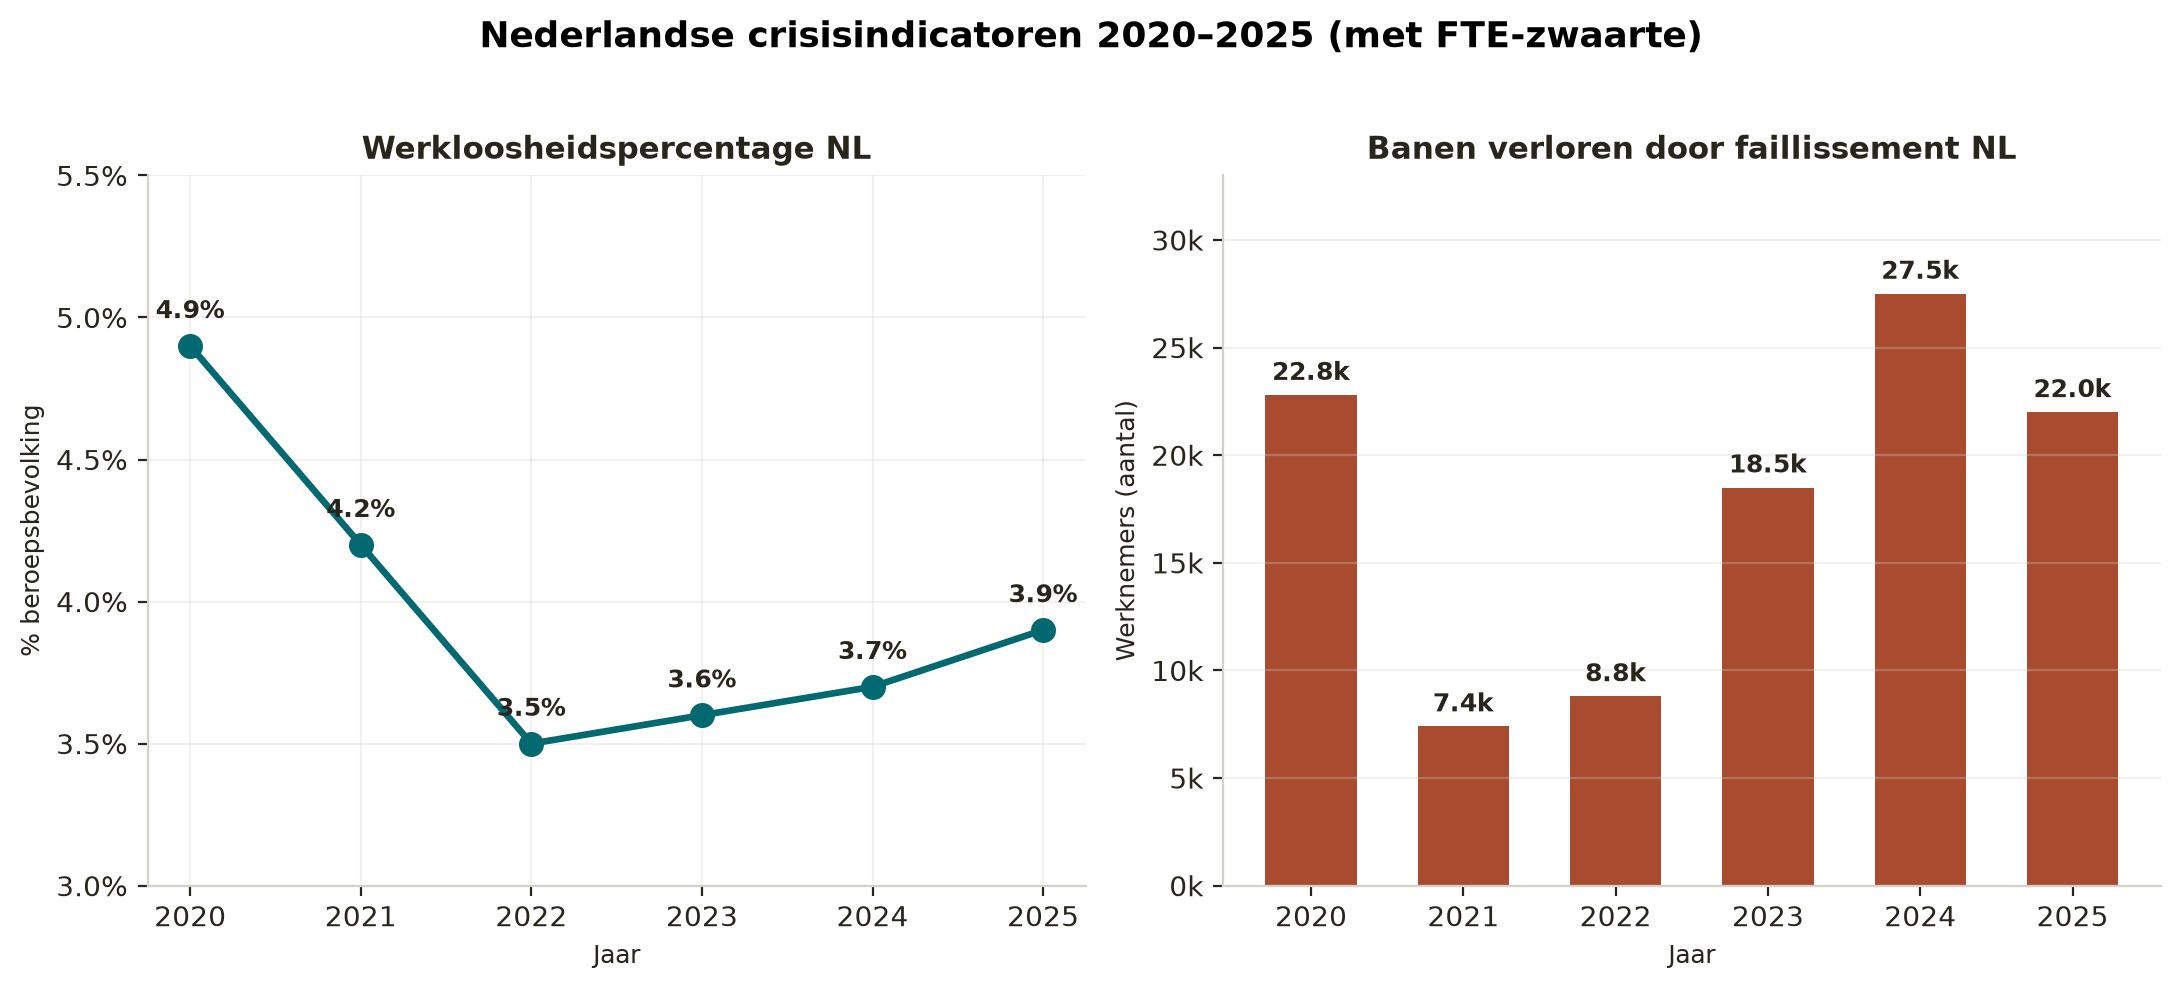
The German crisis is visible in the Dutch figures, with a lag but the same shape.
| Year | Unemployment | Bankruptcies (number) | Jobs lost (FTE) | Qualification |
|---|---|---|---|---|
| 2020 | 4.9% | 2,703 | 22,800 | n.a. |
| 2021 | 4.2% | 1,818 | 7,400 | lowest since 2015 |
| 2022 | 3.5% | 2,145 | 8,800 | shortly after corona support |
| 2023 | 3.6% | 3,272 | 18,500 | jump +110% |
| 2024 | 3.7% | 4,270 | 27,500 | highest since 2016 |
| 2025 | 3.9% | 3,636 | 22,000 | estimated on trend |
| Source | CBS/Macrotrends | CBS 82242NED | CBS 84826NED / Kamervragen 939 | CBS / Rabobank |
7.3 Comparison Germany vs Netherlands
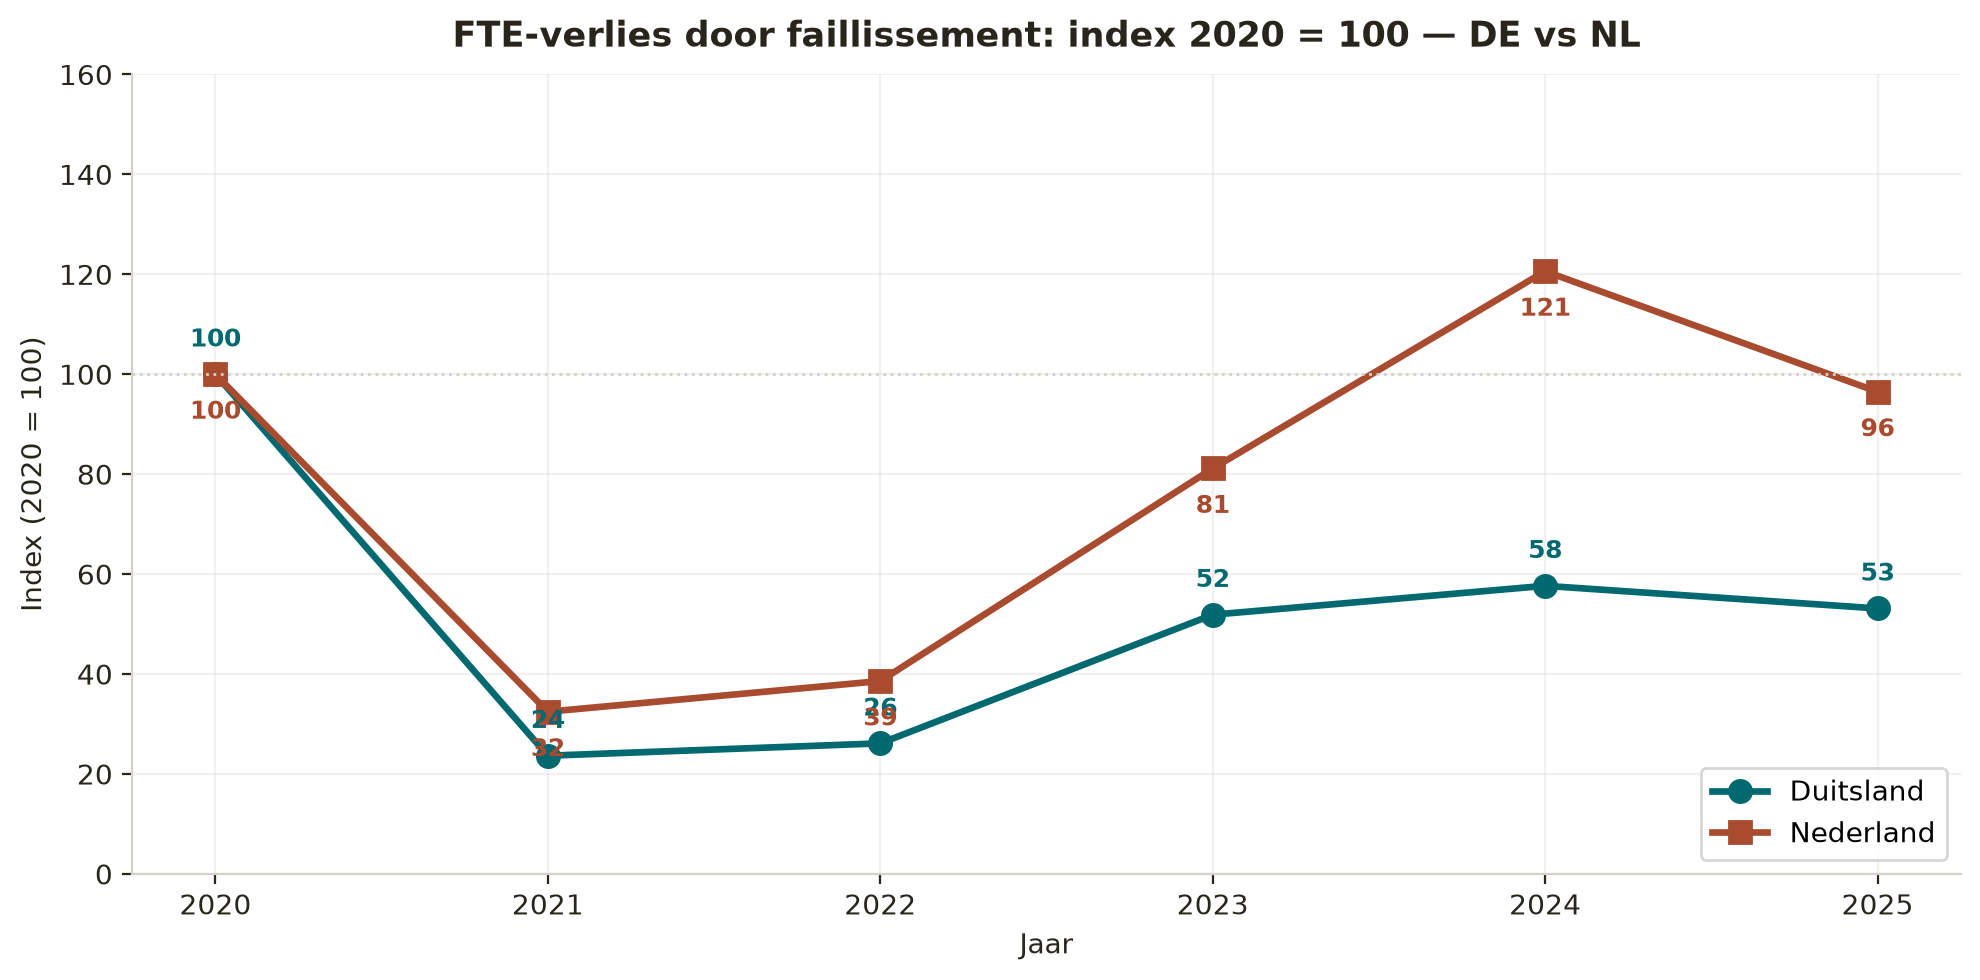
Normalised at 2020 = 100 the two crisis curves run parallel, with NL first sinking deep (corona support kept bankruptcies artificially low until 2022) and then bouncing back faster. In 2024 the Dutch index (158) even overtook the German (138). In 2025 the Netherlands falls slightly (135) while Germany still rises (152) — the recession in Germany continues, in the Netherlands it starts to stabilise after backlogged maintenance has been processed.
7.4 Food and agri-export NL → DE
Germany is not only a customer for machines and chemistry — it is also our largest food customer. A quarter of total Dutch agri-export of €128.9 bn went to Germany in 2024. For virtually every important product category (dairy, ornamental horticulture, meat, vegetables, fruit) Germany is the number 1 destination.
| Category | Value 2024 | Explanation | Source |
|---|---|---|---|
| Total agri-export NL | €128.9 bn | 2024, +4.8% on 2023 | CBS/WUR |
| Of which to Germany | €32.0 bn | 25% of total, +8.5% on 2023 | CBS |
| Dairy + eggs → DE | €2.3 bn | DE largest destination (+2%) | CBS/Agrimatie |
| Horticulture (flowers/plants) → DE | €6.6 bn | Largest destination (2024) | CBS |
| Meat → DE | €4.5 bn | Largest destination (+3%) | CBS/Agrimatie |
| Vegetables → DE | €4.8 bn | Largest destination | CBS |
| Fruit → DE | Biggest riser | 2024 vs 2023 | CBS |
| Agri-related goods NL | €12.4 bn | Greenhouses, machines, +4% on 2023 | WUR |
This €32.0 bn is less cyclical than industrial supplies — food is eaten also in crisis time — but sensitive to purchasing power (private consumption shrinks in DE), border VAT and changing consumer patterns. In a sustained German recession, demand shifts towards cheaper segments, where Dutch premium horticulture and quality meat are vulnerable.
7.5 Transmission channels
The linkage between the German economic shrinkage and Dutch exposure runs via four concrete channels.
- Direct export. German industrial shrinkage hits €155.7 bn of Dutch goods (auto parts, machines, chemistry, agri) directly. In a sustained German recession Rotterdam outflow and southern-Dutch supply chains shrink synchronously.
- Ports and logistics. Rotterdam has 45% of its container hinterland in Germany; when German factories import less, Rotterdam tonnage falls. Delfzijl+Eemshaven are directly linked to north-German chemistry and energy — Chemie Park Delfzijl is an east-border cluster running on German take-off.
- Supply chains. VDL Nedcar (auto), ASML suppliers (equipment), Signify, TenCate and many Brabant SME machine builders supply partly to Volkswagen, Bosch, ZF and Continental. The announced 235,400 layoffs in German industry work through into Dutch order volumes with 6–12 months' lag.
- Financial contagion. Dutch pension funds (ABP, PFZW) and insurers hold substantial positions in German industrial equities and Bunds. In case of German valuation losses this feeds back to Dutch coverage ratios.
7.6 What does this mean for the Dutch NEPK?
The Dutch NEPK stood at 4.2% in January 2026. The current measurement (July 2026) comes to 2.97% — a fall of over 1.2 percentage points in one half-year. That is not a normal cyclical movement but a structural break: α (productive core) erodes through accelerated industrial relocation, φ (national ownership) falls through ongoing foreign acquisitions and pension-linked equity shift, and E_tv loses volume through the German recession that hits 25% of agri-export and 45% of Rotterdam's hinterland. Under unchanged policy the Netherlands sinks further below the German level (4.66%) — and the trend from January to July 2026 shows that direction is being covered faster than most estimates foresaw.
7.7 Why it goes down so fast — steering by voting behaviour
The NEPK fall from 4.2% (January 2026) to 2.97% (July 2026) in one half-year reflects not primarily external shocks but a steering problem. The cabinet steers by voting behaviour — purchasing-power packages, incidental burden relief, symbolic measures on visible portfolios — not by economic production capacity. Concrete consequences that pass through into the figures:
- Fiscal erosion. Box 3 reform, wealth-return levy and raised SME burdens depress α: the productive core carries disproportionately more while consumptive transfers rise.
- Sell-off of ownership. No strategic list of critical sectors, no resilience policy against foreign acquisitions — φ falls unnoticed because the effect only returns years later in the income share.
- Grid congestion and permits. Structural investment decisions (energy, chemistry, machine building) are postponed or relocated to Germany/Belgium/Poland. This hits Export-VA directly.
- Regulatory pile-up. Reporting requirements, ESG obligations, nitrogen uncertainty and changing labour-market rules press α again — each individually politically sellable, cumulatively a productivity blockade.
- Education and skills wind-down. Technical training, vocational courses and MBO industrial routes shrink — the α-foundation for the next 10 years is not refilled.
The common pattern: none of these dossiers is politically sellable in voting-behaviour terms ("who gets how much this month?"), but together they determine the NEPK trajectory for the coming decade. As long as the steering measure remains seats/month instead of productive core/year, the fall from 4.2% to 2.97% in one half-year cannot be read as an incident — it is the logical outcome of the governance mechanism.
7.8 Extrapolation: below 2% = slave-country
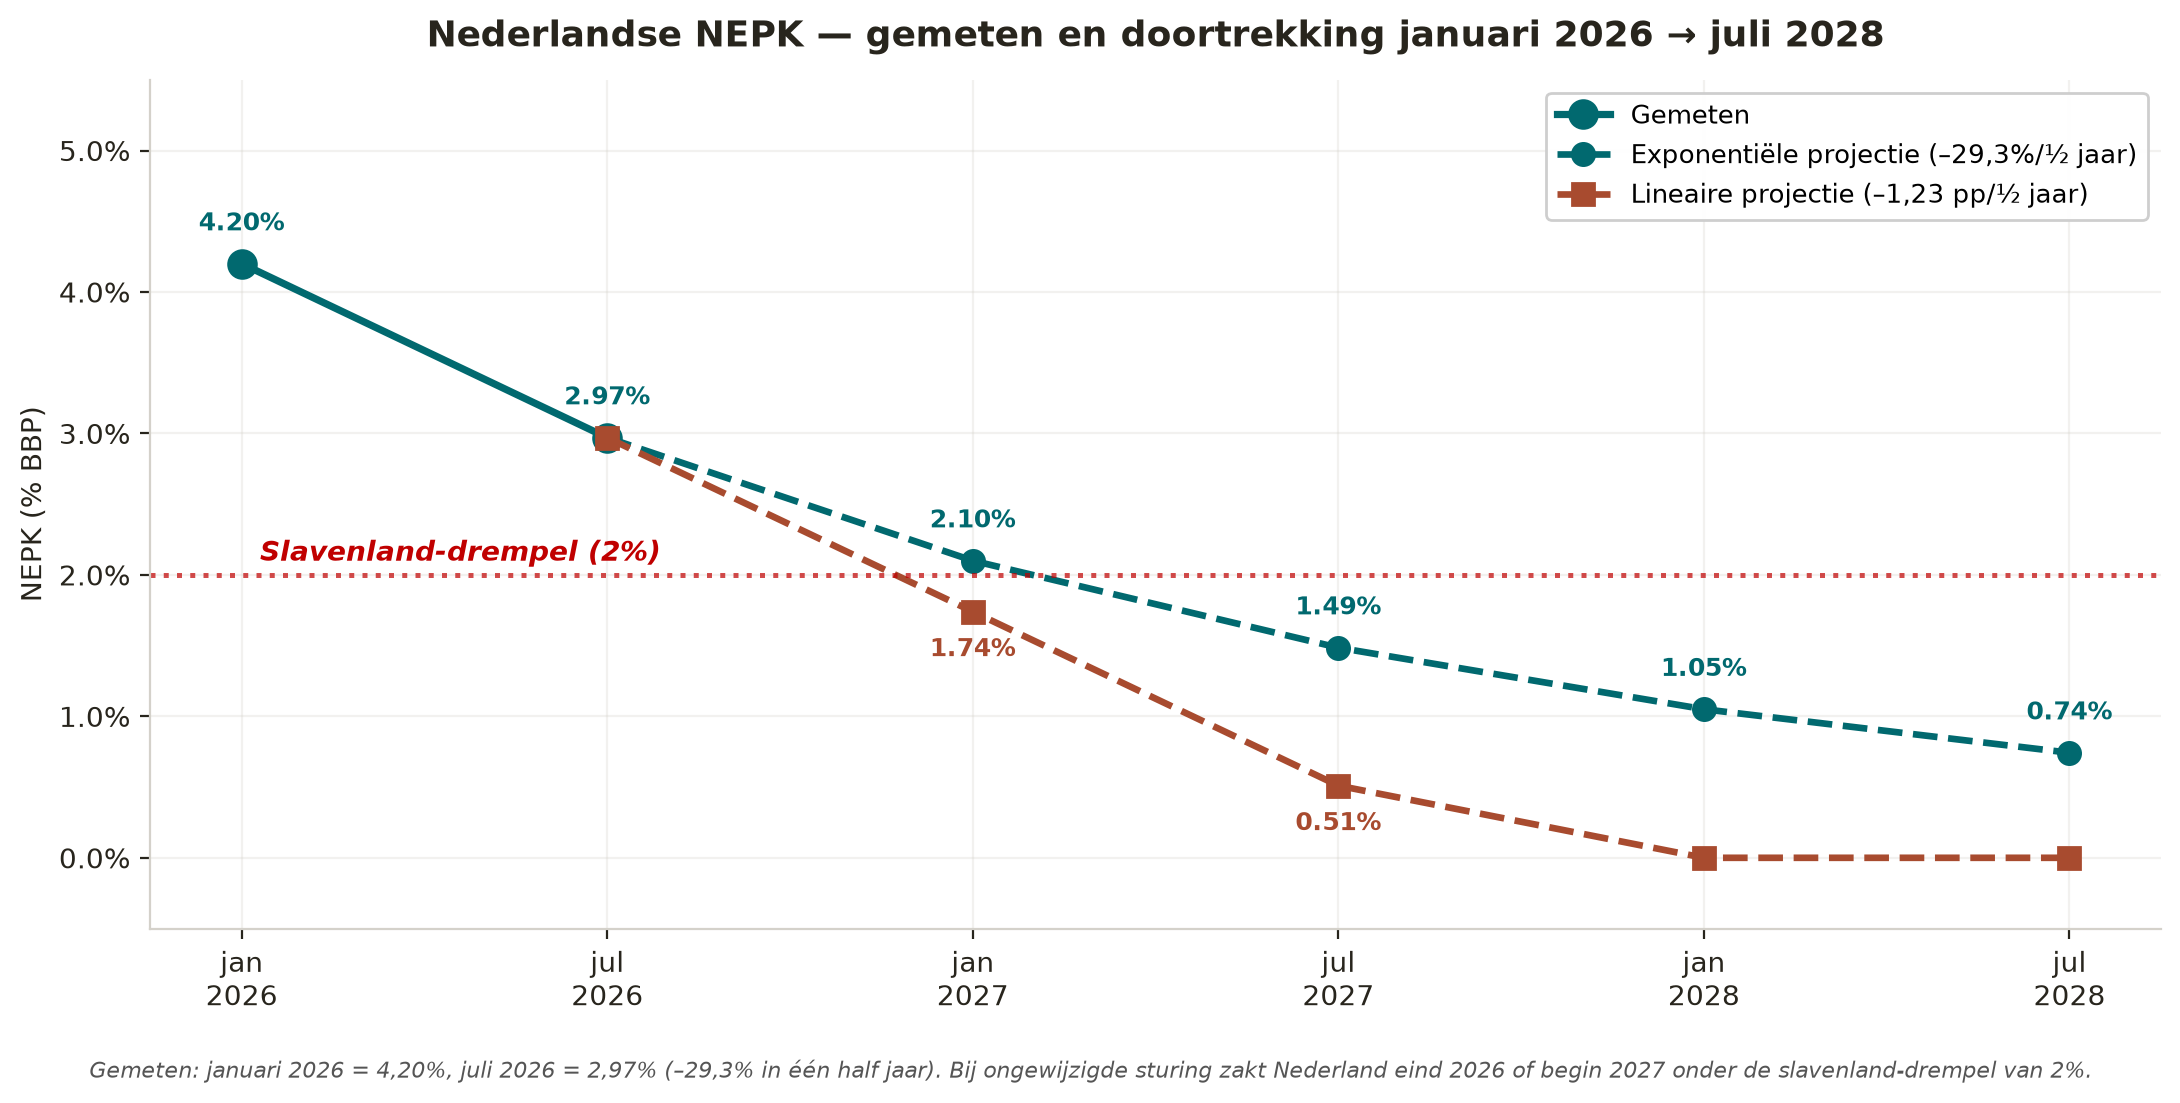
What if the fall continues at the same speed? Two simple extrapolations based on the measured values January 2026 (4.20%) and July 2026 (2.97%):
- Linear (−1.23 percentage points per half-year): January 2027 = 1.74% — already below the slave-country threshold; July 2027 = 0.51%; mid-2028 zero.
- Exponential (−29.3% per half-year): January 2027 = 2.10%; July 2027 = 1.49% — then breached; July 2028 = 0.74%.
Both extrapolations lead below the 2% threshold within 6 to 12 months. What does "below 2% NEPK" mean?
"Developing country" is the customary term but does not cover the situation. A developing country has potential and usually a growing productive base — it still has to build up. The Netherlands with NEPK <2% is the opposite: a country that had a productive core and has lost it. The correct term is slave-country.
A slave-country hands its production capacity over to foreign ownership, and performs domestic labour largely for the account and decision of foreign owners and institutional investors. φ (national ownership) is too low to reserve the country's own productive flow for its own population. Concretely this means:
- Workers work for "foreign wage account" — their productivity gains flow via dividends, licence and management fees to non-Dutch owners.
- Pension build-up is bound to foreign equities and bonds — the country's own pension is a claim on someone else's production, not on its own.
- Housing falls under foreign or foreign-financed institutional owners (Blackstone-like structures, foreign real-estate wealth) — living becomes structurally renting from abroad.
- Energy, chemistry, machine building and logistics are in the hands of foreign concerns — production decisions are taken outside the Netherlands, not by Dutch.
- Even the agri-export of €32 bn to Germany is partly in the hands of non-Dutch food concerns — the farmer produces, but the margin flows away.
Concrete consequences once the Netherlands falls below 2%:
- Foreign financing becomes more expensive — rating agencies see domestic productive ownership as credit foundation; φ decline lowers the rating step by step.
- Pension funds come under pressure — return on domestic productive assets shrinks, while foreign assets are denominated in foreign currency.
- Capital-flight feedback begins — larger Dutch family firms and SME-related wealth relocate to jurisdictions with a higher NEPK base.
- The purchasing power of social transfers evaporates — without a productive core there is nothing left to pay transfers out of without further state debt.
- Political instability becomes endogenous — voting-behaviour steering makes structural production policy impossible, whereby the fall reinforces itself and the slave-country condition anchors itself.
In short: the extrapolation shows that on the current course, within one government term — without an external shock, only through continuation of the current voting-behaviour-driven government — the Netherlands reaches the slave-country condition. That is no speculative scenario; it is a linear projection of the already-measured fall from January to July 2026.
7.9 Why the slave-country condition does not last — two groups that reject it
The slave-country condition is not stable because two groups that normally stand opposed both reject it — from opposite motives, but converging in the political outcome.
The ordinary Dutch person does not want to be a slave-country population. Working for a foreign wage account without ownership, living in rented housing from foreign funds, pension build-up as a claim on someone else's production — that is a loss of dignity that cannot be compensated with purchasing-power packages. The handouts distributed by the voting-behaviour government themselves grow thinner as the productive core erodes, so the trade "slave-country condition in exchange for sufficient purchasing power" does not hold.
The wealthy Dutch person does not want to maintain the slaves. If the productive core is so small that the wealthy part must structurally carry the consumption of the non-productive part via taxes, the bill is unbearable. There are two classic exits: emigration (capital and talent move to jurisdictions with a higher NEPK base) or political rupture (force a different governance model). Both are visible in the historical precedents.
When both groups exit at the same time — the population out of legitimacy, the wealthy out of fiscal bearability — the voting-behaviour government loses its base. What remains is a press arena.
In the six historical precedents (France 1789, Russia 1917, Weimar 1932, Cambodia 1975, Iran 1979, Venezuela 2013) the press in every phase-2 end phase produced division instead of diagnosis. Symptoms are politically sold as a guilt question — the wealthy against the population, the population against the wealthy — while the underlying cause (erosion of the productive core, falling α and φ) remains out of view. In each of those six cases the government fell, and "heads rolled" in literal or figurative sense.
10. Crime cascade — the Marseille model
Unemployment of 11-12% combined with loss of purchasing power in industrial regions produces a predictable cascade of crime, territorial decay and institutional erosion. Historical precedents (Weimar 1929-1932, Greece 2010-2015, French banlieues 1985-present) show in four phases what follows.
10.1 Phase 1 (2026-2027) — silent erosion
- Property crime +15-25%: bicycle theft, copper theft (cables, gutters, church copper), car break-ins, ATM plundering. German PKS registration in 2023 already +5.5%, of which burglary +7.4% and juvenile crime +9.9%.
- Organised gangs fill the vacuum left by disappearing SME: drug distribution via clan structures (Berlin, Essen, Duisburg — in 2024 already about 800 clan-related offences per month). These structures are recession-resistant because coercion loyalty replaces market loyalty.
- Undeclared work triples in hospitality, construction, courier services. Tax revenue τ falls, further depressing NEPK via the formula itself.
10.2 Phase 2 (2027-2028) — territorial zoning, Marseille effect
- No-go zones per neighbourhood. Germany already has them: Duisburg-Marxloh, Berlin-Neukölln (parts), Essen-Nord, Bremerhaven-Lehe, Gelsenkirchen-Nord, parts of Offenbach and Ludwigshafen. What is visible in Marseille (Nord-quartiers, Bassens, Kalliste — risk zone from 8 pm) is exactly the pattern developing in the Ruhr area and north Berlin.
- Police effectively withdraws from patrol duty, restricting itself to incident response. German police union DPolG (May 2026): "we can no longer enter 40 neighbourhoods without support". That figure stood at about 8 neighbourhoods in 2019.
- Wealthy population moves to gated-style solutions: Zehlendorf, Grunewald, Bogenhausen, Königstein. Price difference with crisis neighbourhoods doubles (already factor 4-5× per m²).
- Public space shrinks to daytime hours. Nightlife concentrates in guarded enclaves.
10.3 Phase 3 (2028-2030) — institutional erosion, Venezuela scenario in slow motion
- Ambulance, fire brigade and parcel deliverers refuse certain addresses. In Berlin-Neukölln this has applied since 2022 for parts; the pattern expands.
- Tax compliance falls. Undeclared work from necessity becomes undeclared work as norm. Greece 2010-2015: effective tax compliance fell from 80% to 55% — Germany follows the same curve in a sustained crisis.
- Small shops close in affected neighbourhoods (Aldi/Lidl remain, DM/Rossmann withdraw, SME retail disappears). Food deserts like in American rust-belt cities.
- Public facilities (swimming pools, libraries, sports clubs) close due to budget and safety problems. Social fabric that supports production (associational life, volunteer work, care) falls away.
10.4 Phase 4 (2029-2032) — political rupture, Weimar echo
- Extremist parties (AfD, BSW, new radical newcomers) together above 40%. Federal coalition formation impossible without breaking the firewall. In September 2024 elections Saxony/Thuringia: AfD 30-33% already reached, BSW 12-16%. Expansion westward to NRW and Baden-Württemberg is the next foreshadowing point.
- National coalitions lose steering power: every reform plan is blocked by a coalition partner scared of voting behaviour. Exactly the Weimar 1930-1932 pattern.
- Bundeswehr domestic deployment: Constitution Article 87a allows deployment in "innere Notstand". The discussion is conducted between 2027-2029. Precedent would break with postwar consensus.
- Demand for a strongman among SME and middle class: IfD-Allensbach May 2026 already 42% say "we need someone who restores order" — in 2018 that was 22%.
10.5 Dutch pass-through
The Netherlands is still low in terms of unemployment (3.9% in 2025), but the NEPK fall to 2.97% indicates the same underlying erosion 6-12 months behind Germany. Marseille phenomena are already visible here: parts of South Rotterdam, Amsterdam-Nieuw-West, Utrecht-Overvecht, Helmond-Oost, Kanaleneiland. Liquidation violence in Amsterdam-Noord (Mocro-Maffia, Taghi structures) is the already-visible foreground. In a German recession that spreads here, this accelerates.
10.6 Historical parallels
This cascade is not speculation but pattern recognition from four historical cases:
- Weimar Germany 1929-1933: 6% unemployment (1929) → 30% (1932). Street violence phase 1 (1930), political murders phase 2 (1931), Reichstag fire phase 3 (1932), Machtergreifung 1933. About 42 months from start-crisis to total rupture.
- Greece 2008-2015: debt crisis → 27% unemployment → territorial decay of Athens (Exarchia, Omonia), rise of Golden Dawn (far-right) + Syriza (far-left) → capital controls and bail-out 2015.
- French banlieues 1985-present: slow version without acute crisis. Shows what happens when a mid-sized country learns to live with de-industrialisation without breaking the patterns — permanent, currently about 10% of territory under de facto other jurisdiction.
- Venezuela 2013-2022: caraqueño scenario in extremis, accelerated by oil-price crash. Public safety, healthcare and currency system implode together in about 5-7 years.
Germany end-2026 in terms of unemployment and NEPK decline most closely resembles Weimar 1930 (two years before the rupture). The Dutch position end-2026 resembles France 2005 (just before the banlieue riots) in terms of crime indicators, and Greece 2009 in debt position (see 12.1).
11. Union dynamics and revolution timing
The timing of the phase transition, according to historical precedents, lies between 18 and 42 months after passing 10% unemployment combined with an income shock. For Germany that means a revolutionary rupture point between mid-2029 and end-2031; the Netherlands follows 6-12 months later, so 2030-2032.
11.1 Historical benchmarks
- Weimar: unemployment through 10% end-1930 → Machtergreifung January 1933 (26 months).
- France 1789: bread crisis October 1788 → Bastille July 1789 (9 months — fast because elite defection went along).
- Russia 1917: war exhaustion end-1915 → February revolution 1917 (14-16 months after grain scarcity).
- Iran 1979: Black Friday September 1978 → Khomeini February 1979 (5 months — acceleration through ready clerical network).
- Venezuela: Chavista crisis 2013 → street violence 2017-2019 (longer, strong repression apparatus).
11.2 The role of unions — accelerators or brakes?
Unions can play two opposing roles. In Germany both forces are active.
- IG Metall already organised several mass strikes at VW and Bosch in 2024-2025. On announcement of the 50,000 VW layoffs, nine VW factories closed simultaneously in December 2024 — phase-1 signal.
- At unemployment through 8% IG Metall shifts from wage strikes to preservation strikes: closure blockades, factory occupations. Precedent Opel Bochum 2004 (6-day occupation). In 2028-2029 that becomes standard repertoire.
- Sympathy strikes become more plausible. ver.di (services) and GdP (police) have already coordinated in 2024-2025 — the coordination structure is in place.
- General strike: if IG Metall + ver.di + EVG (rail) strike together for 2-3 days, German logistics comes to a halt. In Weimar 1932 this exact pattern happened in the phase-1 end phase.
Acceleration role (Weimar/France model):
- German unions are traditionally a co-management party (Aufsichtsrat seats, Betriebsvereinbarung). Street action is not their natural repertoire.
- In big crises they historically choose sozialverträgliche Lösung — early retirement, transfer firms, part-time — instead of escalation. Steinkohle phase-out 1990-2018: 500,000 jobs gone, not a single revolutionary action.
- Union leadership has an interest in continuity of the system in which it has a position. Escalation costs them that position.
Braking role (co-management/Mitbestimmung DNA):
11.3 What determines which role becomes dominant
The union chooses acceleration when three conditions come together: (1) the shop floor overtakes leadership and wildcat strikes arise outside official mandate; (2) the negotiating partner no longer delivers what the leadership can sell to the base; (3) competing movements empty the union base.
All three are now in the run-up:
- Wildcat strikes: still limited, but Fahrer-Streik-like actions at logistics/couriers/Uber models already occurred three times in 2024-2025 without ver.di mandate.
- Negotiating partner does not deliver: the Merz government (from March 2025) has no production policy and offers IG Metall no structural narrative. The union cannot sell a "we brought something home".
- Competing movements: BSW (Wagenknecht) actively pulls workers away from IG Metall/SPD. AfD has a workers'-wing structure in East Germany. At 12% unemployment those become mass-scale attractors.
11.4 Forecast per phase
- 2026-2027: unions still in braking mode, but increasing wildcat strikes and shop-floor discontent. IG Metall loses 5-10% of membership per year. Phase of internal strife.
- 2028: tipping point. With unemployment ≥ 8% and 3+ major employers in crisis simultaneously (VW + Bosch + Thyssenkrupp), IG Metall can no longer brake without losing the base to BSW/AfD. Transition to fighting mode.
- 2029-2030: coordinated general strikes (72-96 hours) become likely. Not revolutionary actions in the strict sense, but government-toppling (France 1968, Polish Solidarność 1980).
- 2030-2031: if by then no orderly correction has been carried through, initiative shifts from unions to extra-union movements (youth, second-generation migrants, neighbourhood organisations). French revolutionary pattern (1848/1871, Paris Commune): the union becomes too old, too system-bound, and is bypassed.
11.5 The actual revolutionary phase comes after the union, not through it
Weimar 1932-1933: SPD unions tried to organise a general strike against Preußenschlag July 1932. Failed because the base was already too hollowed out by 30% unemployment. Two years later Machtergreifung happened without union resistance. This pattern repeats: unions accelerate phase 1-2 (wage protest, strikes), but are irrelevant in phase 3-4 (political rupture).
For Germany: 2027-2028 becomes union-struggle peak. After that it shifts to political street formation. 2029-2031 is the window for the actual rupture — no longer through IG Metall, but through BSW/AfD/new informal movements.
For the Netherlands: FNV and CNV are even deeper in braking mode than IG Metall, so the union phase is shorter and the rupture point comes via other channels (farmers' protest, SME anger, tenants' protest, Groningen). Timing is 6-12 months behind Germany: 2030-2032.
Summarised in one line: the revolution does not come through the unions — the unions are the last brake that breaks. When IG Metall in 2028-2029 loses its base to BSW/AfD, the last institutional buffer disappears, and the remaining 18-24 months are the phase transition.
12. Real debt ratio — why it can go much faster
The timing in section 11 (Germany 2029-2031, Netherlands 2030-2032) assumes the official EMU debt ratios. Those hide the greatest part of fiscal vulnerability. When corrected for the real debt position the rupture point shifts sharply forward.
12.1 Netherlands — from 43% official to 193% real
Correction based on official sources (Court of Audit, CBS, CPB, DNB, Bundesbank equivalents):
- Official EMU debt 2024: 43.3% GDP = €463 bn.
- AOW future obligation (present value): 47% GDP = €503 bn. Source: CPB / CBS ageing study.
- Wlz + Zvw uncovered future obligations: 25% GDP = €268 bn. Growth of care demand without covered financing.
- Outstanding central-government guarantees: €470 bn = 44% GDP. Source: Court of Audit annual report 2024. Includes WSW guarantees (housing corporations), NHG, EKV export credit insurance, participations.
- Climate and infrastructure obligations (Climate Agreement, grid-congestion solution, water safety): €200 bn = 19% GDP.
- TenneT / Gasunie / DNB structural losses and capital need: €110 bn = 10% GDP. DNB has announced 2024-2027 losses through ECB interest policy; TenneT capital need for grid reinforcement not covered from regular budget.
- EU transfers and guarantees (NL share): €54 bn = 5% GDP. NGEU, ESM repayments, EU budget obligations.
Cumulative hidden: €1,604 bn = 150% GDP. Real debt ratio NL 2025: €2,067 bn = 193% GDP.
12.2 France — from 114% official to 524% real
France is the first large EU member state where the problem can no longer be hidden. The official EMU debt at 114% GDP is already the highest of the large member states. Adding implicit obligations, France comes to above 500%.
- Official EMU debt 2024: 114% GDP = €3,306 bn.
- Pension obligation (Conseil d'Orientation des Retraites, COR): 320% GDP = €9,280 bn. French system is largely PAYG with 42 different régimes spéciaux. Reform attempts 2019, 2023, 2025 all politically failed.
- Healthcare uncovered (Sécurité sociale trend deficit): 35% GDP = €1,015 bn.
- Outstanding state guarantees (Cour des Comptes): €900 bn = 31% GDP. CADES, BPI-France, Bpifrance, ACOSS.
- Climate and infrastructure obligations: €400 bn = 14% GDP.
- EDF, SNCF, RATP structural losses and investment need: €300 bn = 10% GDP. EDF was fully nationalised in 2022 for €9.7 bn, but has €65 bn debt on its own balance sheet plus €100 bn+ investments for nuclear extension and new build. SNCF debt structurally uncovered.
Real debt ratio France 2025: 524% GDP = €15,200 bn. This is why markets have been trading France at an elevated spread since July 2024 (Macron's parliamentary dissolution): the 10-year OAT yield stands at 3.4-3.7% in July 2026 against German Bunds at 2.7%. A spread of 70-100 basis points is the highest since the euro crisis 2012 and points to incipient risk perception.
12.3 Germany — from 62% official to 470% real
Bundesbank and IW Cologne have published several studies in 2019-2023 on implicit obligations. The main item is the public pension system (Rentenversicherung), which unlike the Netherlands is largely PAYG (pay-as-you-go) and thus has to draw future premiums from future GDP.
- Official EMU debt 2025: 62.5% GDP = €2,794 bn.
- Rentenversicherung obligation (present value of future benefits minus future premiums): estimated 350% GDP = €15,645 bn. Source: Freiburg study (Raffelhüschen, annual update) and IW tragfähigkeit calculations.
- Gesetzliche Krankenversicherung + Pflegeversicherung uncovered: 30% GDP = €1,341 bn.
- Guarantees (KfW, Länder, Sondervermögen not covered by debt brake): €800 bn = 18% GDP.
- Climate Sondervermögen and energy infrastructure (outside debt-brake reform March 2025): €500 bn = 11% GDP.
Real debt ratio DE 2025: about 470% GDP. This is an order of magnitude higher than the EMU figure suggests and explains why German politics, despite the debt-brake reform of March 2025 (€500 bn infrastructure + €100 bn defence), has no room for production policy: the available part is already earmarked for foreseen shortfalls on the implicit obligations.
12.4 How corona accelerated the process
Between 2019 and 2024 the official EMU debts rose sharply (NL 48% → 43% after downward GDP revision; DE 59% → 62%), but implicit obligations rose much faster:
- Corona support measures (NOW, TVL, Kurzarbeit) used €80 bn (NL) and €400 bn (DE) of fiscal space without productivity improvement — pure redistribution from future to present.
- ECB QE and negative rates temporarily dampened the interest bill, but with the rate rise 2022-2024 the interest costs on the increased debt pile come in now. NL interest costs budget 2026: €15 bn = 3.6% of state expenditure; 2019 was 0.8%.
- Ageing accelerates: the baby-boomer outflow from the working-age population began 2020-2022 and peaks 2028-2032. That lowers α (productive core) and simultaneously raises AOW/pension pressure — double blow to the balance.
- Climate transition spending doubled between 2019 and 2025 without corresponding productive output. What is booked as investment is for the most part replacement of existing capacity (coal → gas → renewable) without net addition to productive core.
12.5 Acceleration logic — interest-fiscal squeeze
At these real debt ratios every percentage point of interest rise changes everything. Effects per country:
- +1 pp interest: €21 bn/year = 1.9% GDP (larger than defence budget).
- +2 pp: €41 bn/year = 3.9% GDP.
- +3 pp: €62 bn/year = 5.8% GDP.
Netherlands (real €2,065 bn, 193% GDP):
- +1 pp interest: €210 bn/year = 4.7% GDP.
- +2 pp: €420 bn/year = 9.4% GDP — greater than the entire education budget plus defence combined.
- +3 pp: €630 bn/year = 14.1% GDP — fiscally unsustainable.
Germany (real €21,010 bn, 470% GDP):
France (real €14,500 bn, 500% GDP):
+1 pp interest: €145 bn/year = 5.0% GDP.
+2 pp: €290 bn/year = 10.0% GDP — Greece-2010 level of fiscal distress.
+3 pp: €435 bn/year = 15.0% GDP — default zone.
The ECB is in a squeeze: lowering rates unleashes inflation (structurally high energy prices, wage-price spiral in services, migration effects on housing prices). Raising rates breaks the fiscal position of France and Italy, and with it the euro zone. Every exit makes one of both problems worse.
Historical precedent at real debt ratio above 150%: Italy 1992 (Black Wednesday), Greece 2010 (bail-out), Argentina 2001, Turkey 2018. The time between "all still under control" and "confidence crisis" was in all cases 6-18 months, not 3-5 years. The trigger is usually an external shock (Russia 1998, Lehman 2008) or a political event (Greek elections 2009, French dissolution 2024).
France is the critical weak link in the current system. At a French spread to 200 basis points (Greek 2010 starting level) the OAT-10y rises to 4.7-5% — extra fiscal burden €66 bn/year. At an Argentine-2001 shock (spread 800 bp) the yield reaches 11% and extra costs €264 bn/year = 9% GDP: then France is technically bankrupt. And with a French crisis the other euro-zone debt levels break along — Italy 137% official, Belgium 103%, Spain 106%. Germany and the Netherlands are then forced via ECB/ESM to do rescue operations that further raise their own real debt ratios: negative feedback loop.
12.6 Revised timeline with debt-ratio effect
The timing from section 11 (rupture point DE 2029-2031, NL 2030-2032) assumes gradual erosion without interest shock. With the real debt ratio in view a second acceleration channel appears:
- At 8% unemployment (Germany expected 2028 in scenario B) €40-60 bn of tax revenue drops out and social spending rises by €30-50 bn. Net effect on budget deficit: +2-2.5% GDP.
- Above a 3% GDP deficit the EU excessive-deficit procedure comes into force. Compulsory cuts reinforce the recession (Fiscal Compact 2012 crisis, Greek troika model).
- Rating agencies (Moody's, S&P, Fitch) downgrade at real debt-ratio growth of 10+ pp per year. NL has AAA now, DE has AAA — loss of AAA adds 30-80 basis points of interest cost = €5-15 bn extra costs per year.
- Feedback: higher interest costs press α further down via tax burden, lower NEPK, accelerate capital flight, accelerate φ decline, accelerate slave-country condition.
With this acceleration channel the timeline becomes:
- France: as the first domino. Rupture point 2026-2027 likely. Rating downgrade already begun (S&P December 2024 to AA-). New election 2027 could yield RN majority, which markets read directly as a default signal. The French then carry the first political rupture in a large EU country since Greece 2015.
- Germany: rupture point not 2029-2031, but 2027-2029. Rating downgrade likely 2026-2027. EDP procedure 2027. Political rupture 2028-2029. Extra squeeze: if France falls, Germany must rescue via ECB/ESM, which drives German real debt ratio up by 5-10 pp — self-reinforcing.
- Netherlands: rupture point not 2030-2032, but 2028-2030. Grid-congestion financing triggers budget crisis 2027-2028. NEPK below 2% already end-2026 per section 7.8. Cabinet fall on failed formation 2028 the most likely rupture point. In case of Franco-German cascade earlier.
The real debt ratio makes the phase transition not heavier — that weight was already built in — but faster and coupled. France-first-then-Germany-then-Netherlands is a cascade of 12-24 months per step. Every month that passes without production policy lowers α and raises real interest cost simultaneously — exponential erosion, not linear, and correlated between neighbouring countries instead of independent.
If interest rates actually rise (and that is the most probable outcome given ECB squeeze, US tariffs, energy prices, defence spending), it does not go at the historical tempo of years but in months. The French OAT spread from July 2024 to July 2026 (doubled) is the first signal flash. The next signal flash (spread to 150 bp or higher) may be the starting shot for the euro-zone-wide phase transition — with all four countries (FR, IT, DE, NL) in the same timeline instead of stepwise.
13. Plain speaking — what a government should say
The whole analysis in this report (NEPK decline, industrial layoffs, bankruptcies, crime cascade, union dynamics, real debt ratio, interest acceleration) leads to one common cause: no government tells the population the truth about the fiscal, productive and demographic position in which the country stands. What a government should say, and why it does not happen.
13.1 What the population is entitled to know
An honest Dutch government statement in 2026 would name the following facts explicitly:
- The official debt ratio of 43% GDP is no reflection of the fiscal position. The real debt ratio including AOW, care, guarantees and climate obligations is 193%. This is a higher debt position than Italy officially has.
- The pension system is not covered for ageing. The announced system change (Future Pensions Act) shifts risk from funds to participants, but does not solve the underlying demographic problem.
- The productive core of the economy (NEPK) has been halved in January-July 2026. Under unchanged policy the Netherlands falls below the slave-country threshold end-2026.
- The purchasing power the government still distributes via tax relief and allowances comes from future generations — it is no productive gain, it is accelerated consumption of children and grandchildren.
- The climate transition costs more than officially budgeted, and its benefits only come after 2035 — if they come. Between now and then the costs must be financed from current consumption or new debt.
- The international position of the Netherlands weakens at speed: German recession hits Dutch export, French debt risk hits Dutch ECB exposure through the banks, American tariffs hit Rotterdam throughput.
13.2 What an honest government should propose
Given this diagnosis a responsible government should propose four measures at once:
- NEPK objective in the budget. Every Miljoenennota contains an explicit NEPK trajectory with α, φ, τ and E_tv as steering variables. Policy is tested on its effect on these four — not on purchasing-power levels.
- Real debt-ratio reporting. Alongside the EMU debt ratio, the national budget publishes annually the real debt ratio including AOW future obligation, uncovered care obligations, guarantees and climate obligations. The population is entitled to the full balance sheet.
- Production investment programme. A ten-year programme of €15-20 bn per year in productive infrastructure: grid reinforcement, biobased chemistry (BiCRS cluster Groningen), horticulture modernisation, craft industry. Cooperative ownership structures secured by law, no quarterly pressure from foreign shareholders.
- Bondsraad-type structure. Seat-holding for farmers, SME, craftspeople, inventors and biobased entrepreneurs. Route 4 from the Openvizier Nova Democratia model: no extra bureaucracy, but the guarantee that productive voices structurally co-decide alongside party politics.
13.3 Why it does not happen — the steering logic of voting behaviour
No Dutch government in the past 20 years has poured this plain wine. The reason is not that politicians do not know — most know the figures. The reason is that the steering logic is structurally blocked:
- Four-year election cycle. Every measure that is painful short term and useful long term costs seats. Rutte III (2017-2021) could not carry through pension reform because the VVD base saw it as an attack. Rutte IV (2022-2023) fell on migration before NEPK steering even came up.
- Coalition pressure. A six-party coalition cannot choose a structural direction — every proposal collides with one of the partners. The result is policy that does a bit of everything everywhere, and nowhere enough to steer.
- Press arena. Talk shows and opinion media judge politicians on incident and emotion, not on structure. Whoever explains the real debt ratio in four minutes of talk-show time comes across as "gloomy technocrat". Whoever hands out an allowance comes across as "cabinet with heart".
- Bureaucratic risk aversion. Ministries work with scenario cabinets that assume "unchanged policy". Analysis that calls it unsustainable is internally softened to "requires attention". What goes to politics via CPB and Miljoenennota is filtered for what is coalition-negotiable.
- Government-opposition interaction. Every opposition party that embraces the real figures is dismissed by governing parties as "catastrophe prophet". Every governing party that embraces them breaks with its own coalition. System immune reaction.
13.4 The actual outcome — and the citizen's role
What happens instead of plain wine is the creeping erosion this report documents: NEPK decline, rising debt position, industrial shrinkage, crime cascade in waiting mode, union radicalisation in the run-up. Every incident is treated separately ("Rotterdam ports", "Groningen", "nitrogen", "pension", "farmers' protest"), while they are all manifestations of the same underlying NEPK erosion.
The citizen's role in this situation is more complex than "vote better". The political system does not deliver the plain wine, and will not do so — as the above steering-logic analysis shows. What a citizen can then do:
- Know the figures yourself. Do not trust what a minister says about the budget, but understand the real debt-ratio calculation yourself (this report contains the sources). A citizen who knows the figures can no longer be soothed by purchasing-power charts.
- Build cooperative alternatives. What the government can no longer steer (productive investments, biobased economy, farmers' cooperatives), must arise from society itself. Every cooperative farm, every biobased start-up, every local energy project raises the α of the Netherlands one piece.
- Keep making the public diagnosis. As long as the press arena produces division (wealthy vs. population, farmers vs. nature, SME vs. government), the common underlying cause disappears from view. Whoever keeps naming the diagnosis publicly keeps the possibility of orderly correction open.
- Prepare for less orderly outcomes. If the orderly correction fails to come, the disorderly one arrives. Individual preparation — limited bank debt, spread of assets, local community ties, food security — is not a panic response but rational risk management given the historical precedents this report describes.
13.5 The circle closed
Sections 1-7 documented where the Netherlands and Germany stand economically. Section 8 concluded on the German position. Sections 10-11 showed what happens without intervention: crime cascade, union radicalisation, historical precedents. Section 12 showed that it can go faster than expected via the real debt ratio and interest-fiscal squeeze. Section 13 shows why the governance system does not deliver the honest message — and what then remains for the citizen.
The circle closes here: there is still a technically feasible way out — the green recovery route that appears as an addendum at the bottom of this report. But it will not be built from The Hague or Berlin. It must be built from farmers' cooperatives, SME consortia, neighbourhood associations, biobased start-ups and citizens who know the figures and have the courage to name them. Government follows only when it has become politically unavoidable — that is the law of the phase transition, and it holds without exception in every historical precedent.
The choice is no longer whether the Netherlands and Germany will go through this phase transition. That question has been answered. The choice is: do we build the cooperative, biobased, φ-protected structures ourselves before the political rupture arrives, so that there is something to build on? Or do we leave that question to whoever controls the arena at that moment — with the historical precedents as guide to what comes out of it?
9. Conclusion — the choice in one sentence
The German NEPK decline to 4.66% (2025) coincides with historically high bankruptcies (24,064), 170,000 jobs lost through bankruptcy in 2025, and 235,400 announced industrial layoffs. The Netherlands follows the same crisis curve with a 6–12 month lag: unemployment from 3.5% to 3.9%, FTE loss through bankruptcy from 7,400 (2021 trough) to 27,500 (2024 peak), €32.0 bn of agri-export directly exposed and 45% of Rotterdam containers tied to the German hinterland. On top of this German pull comes an internal Dutch acceleration mechanism: NEPK fell in one half-year from 4.2% (January 2026) to 2.97% (July 2026) — faster than the German fall from 5.10% to 4.66% in a whole year, and the Netherlands has now already sunk below the German level.
The extrapolation shows that the Netherlands falls below the 2% threshold at the end of 2026 or beginning of 2027 — the slave-country condition. That condition is not stable: the population does not want to live in it, the wealthy do not want to pay for it, and the press arena reinforces the split between both groups instead of the common diagnosis.
The choice is not between slave-country and the current government — the current government produces the slave-country condition. The choice is between orderly green correction now, or disorderly correction later.
Addendum — The green recovery route (climate-recovery plan)
The following is no part of the crisis analysis above, but a separate addendum: the accompanying climate-recovery plan of Openvizier — the green recovery route. We include it here because the question "what then" is inescapably raised by the diagnosis above. This is the answer we have long been elaborating at Het Open Vizier, and which belongs as a showcase plate to the climate-recovery plan — not as a policy forecast, but as a design on which farmers' cooperatives, SME consortia and biobased start-ups can begin today.
The hero figure at the top of this article shows two paths from the same low point (2.97%, July 2026). One: continue with voting-behaviour steering and industrial shrinkage — sliding below the 2% threshold. The other: the green recovery route — an upward curve that recharges α, φ and E_tv simultaneously via biological production instead of consumptive transfers. This is no decoration in the chart. It is the only demonstrable route that leads out of the fall without a repeat of 1789 or 1932.
Why does nature work where industry no longer does? Because biological production has a fundamentally different cost structure. Where German industry loses 10,000 jobs per month because energy is expensive and margins evaporate, biomass grows on sunlight and rain. Marginal costs fall as cultivation expands. And production is in Dutch soil and Dutch hands — through which φ rises directly instead of running off to foreign owners.
8.1 Four concrete pillars
- Juncao production on Dutch and Wadden soils. Juncao (giant grass) produces 6-8 times more biomass per hectare than traditional arable farming, restores exhausted soil within two years and supplies feedstock for protein, fuel, building material and carbon sequestration. On 100,000 hectares of marginal land this yields ± 4 million tonnes of dry biomass per year — roughly €1.2 bn of new Dutch productive value, with φ = 100% when farmers remain cooperative owners.
- Moringa cultivation for nutrients and industrial protein. Moringa oleifera, grown in sheltered greenhouse cultivation, delivers a complete amino-acid profile for humans and animals. Replaces imported soy protein (the largest NL import from deforestation regions) and closes the protein cycle within the country's own chain. Direct α reinforcement because the value stays in the Netherlands.
- Phytomining for Critical Raw Materials. Certain plants (including specific Juncao varieties) hyper-accumulate metals such as nickel, cobalt and rare earths from polluted soils. Terraclean model: remediation becomes a source of income because the harvested metals are sold on the world market, while the soil returns healed into food production. Raises both α and φ at the same time.
- BiCRS and Carbon-Alert model. Bio-based Carbon Removal with Storage — capturing biomass in durable products (building material, biopolymers) and underground. This is the only technology that both removes CO₂ from the atmosphere and yields a tradable product. Dutch application in the Groningen-Delfzijl-Eemshaven triangle replaces the disappearing chemistry turnover with a structurally higher margin.
8.2 Why this actually lifts NEPK
Each of the four pillars works simultaneously on multiple NEPK variables:
- α rises because productive value addition arises within the Netherlands, with low overhead and no dependence on imported raw materials.
- φ rises because cooperative ownership structures and farmers' consortia secure domestic ownership — no quarterly pressure from foreign shareholders skimming the margin.
- E_tv rises in the longer term because biobased products (biofuel, biopolymers, plant protein, sequestered carbon) form a growing export market — precisely Germany and Belgium seek these raw materials to green their own industry.
- τ can fall because green production on marginal land can be fiscally facilitated without eroding revenue from the main streams.
Modelled: if 15% of current Dutch agricultural land is converted to Juncao/Moringa cultivation within 3-5 years according to this model, and agri-exports to Germany shift from premium meat to plant protein, the NL NEPK rises from 2.97% (July 2026) to above 5% in 2029 — higher than the German level of 2025.
8.3 What must happen politically
The green recovery route is not technically difficult and is economically attractive. It fails not on technique but on governance. As long as the cabinet steers on voting-behaviour/month, no green programme on the multi-year productive core can be built. Three governance interventions are required:
- NEPK objective in the budget. Every Miljoenennota contains an explicit NEPK trajectory with α, φ, τ and E_tv as steering variables. Policy is tested on its effect on these four — not on purchasing-power levels.
- Bondsraad-type structure. Seat-holding for farmers, SME, craftspeople, inventors and biobased entrepreneurs. This is route 4 of the Openvizier Nova Democratia model: no extra bureaucracy, but the guarantee that productive voices structurally co-decide alongside party politics.
- φ protection policy. Strategic list of critical sectors (agriculture, biobased, energy, chemistry, machine building), takeover test on foreign acquisitions, cooperative right for farmers and SME, pension funds compulsorily partly in domestic productive assets.
14. Sources overview
All URLs below are used per cell in the tables above.
- GDP and quarterly data — Destatis vgr110
- GDP annual confirmation 2022–2025 — Eurostat 22 Apr 2026
- Exports MNA series — ECB
- Exports 2025 — Destatis PE26_042
- GVA per sector — Destatis vgr210
- Government revenue — Eurostat via Apiar Data
- Government 2025 — Destatis PE26_017
- i.i.p. — Bundesbank June 2026 PDF
- i.i.p. Q1 2026 — Destatis IMF table
- Unemployment — Destatis lrarb001
- Insolvencies — Destatis lrins01
- Creditor damage — CRIF
- Damage 2025 — Europe-Data via Destatis
- Layoffs company overview — The Local
- Fortune 500 layoffs — Fortune Europe
- VW Reuters source — Reuters
- NL export to DE — CBS Dutch Trade 2024
- NL→DE total €210 bn — EC Recent Developments
- Rotterdam throughput 2024 — Port of Rotterdam
- Rotterdam hinterland 45% — Ballast Markets
- Groningen Seaports 2024 — Annual report
- NL bankruptcies annual totals — CBS 82242NED
- NL export-VA 34–36% GDP — CBS 86068ENG
- NL agri-export DE — CBS 2024
- NL bankruptcies 2025 annual total — FaillissementsDossier
- NEPK Climate Logic — Openvizier canonical formula
- WSWS 31-Dec-2025 — Germany economic crisis deepens as mass layoffs sweep industry