On the box seat or on the luggage rack
Europe can choose — today, not tomorrow
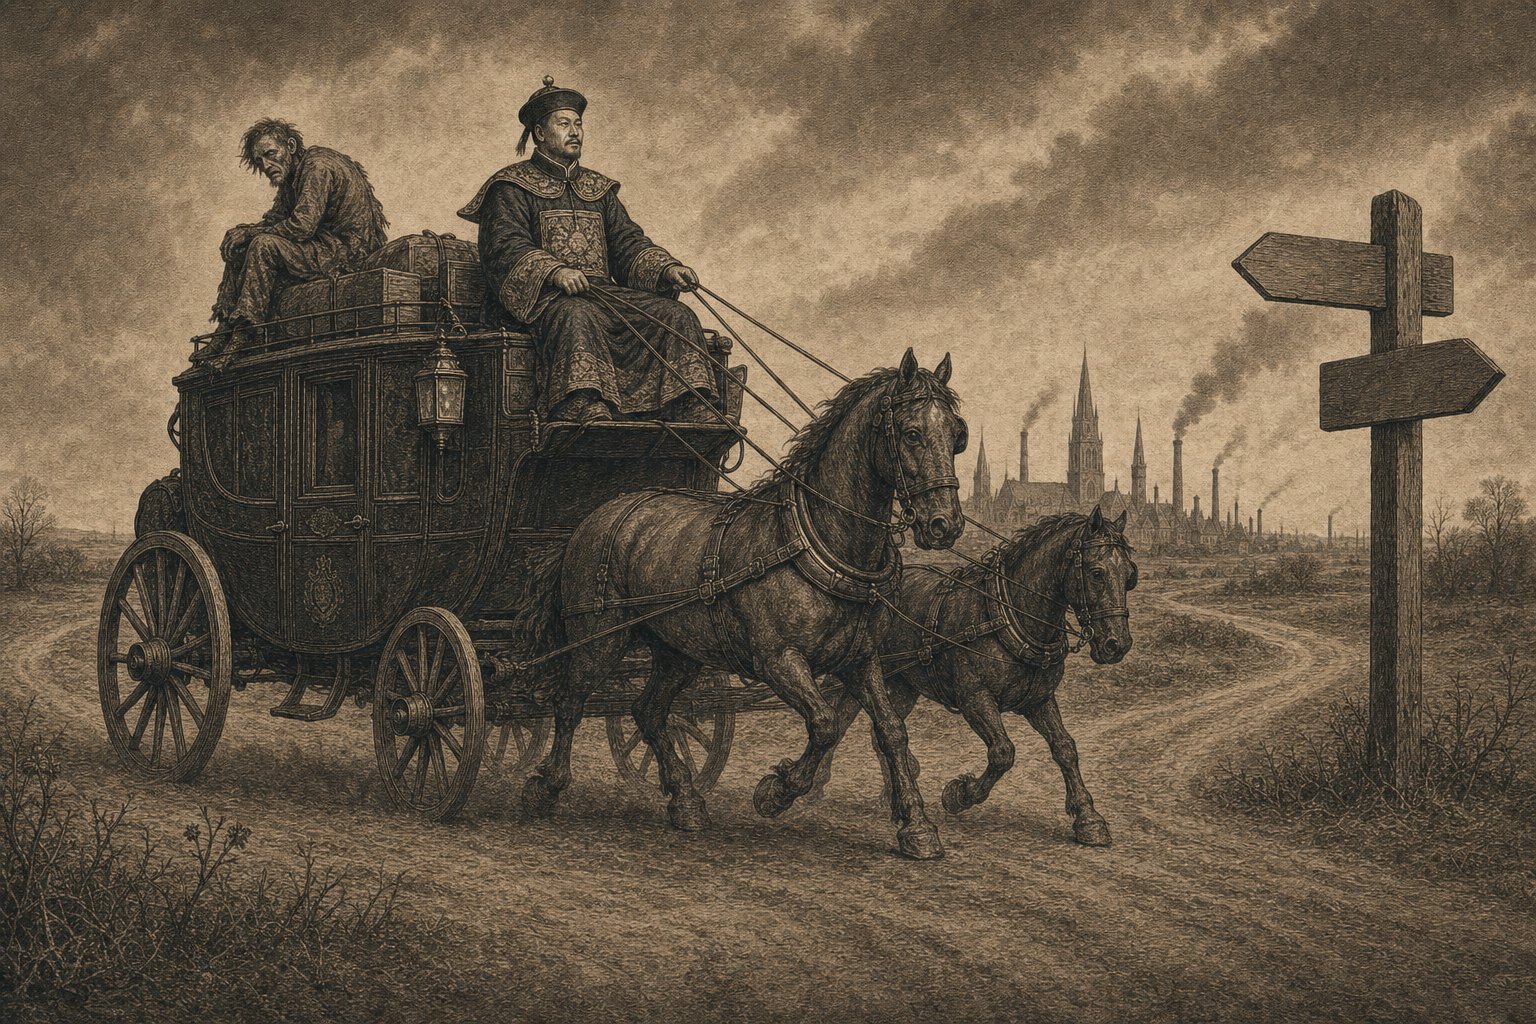
The coachman sits on the box seat. He holds the reins. He sees the road. He determines the route. On the luggage rack sits the person who has allowed themselves to be carried along. They see nothing. They decide nothing. They are dependent. Europe spent thirty years in that position — on batteries from China, on oil from Saudi Arabia, on gas from Russia. There is now a rein ready for us to take hold of ourselves. But only today. Not tomorrow.
The thesis of this article
Those who wait for others to see it will soon be sitting at the back again. Advantage is not what they say in Brussels or The Hague. Advantage is what you see, understand and tackle earlier than the rest. The coachman who waits for consensus becomes cargo himself.
The figures in this article show that there is one energy route that wins without subsidy. On every metric. That route was not invented in Europe, but it can be built in Europe. If we start today. Otherwise Japan, Korea and China will build it. And in seven years we will import it under Asian licensing terms.
That decision does not lie with Brussels. That decision lies with everyone who reads this text and acts on what they see.
- Author
- Jacobus van Merksteijn — Carbon-Alert Ltd
- Date
- 20 June 2026 — Palma, Mallorca
- Method
- Three blocks: source · conversion · end system
- Scope
- Mobile + stationary · transport + heating · all forms of energy
- Subsidies
- Deliberately removed from every figure (SDE++, ETS, RED-III, BPM, feed-in)
- Externalities
- Mining clean-up and BECCS effect explicitly included
Who is on the box seat now — and who is on the luggage rack?
First, a timeline. In 2009, Brookhaven National Laboratory published a catalyst that splits ethanol at room temperaturea. Four years later, Nissan began a pilot plant for solid-oxide fuel cells running on bioethanol. In 2022, PNAS published a catalyst with 99.9 per cent CO₂ selectivity at a record-low potentialb. In 2024, Nissan started a facility in Tochigi with seventy per cent efficiency. In 2025, Brookhaven licensed the technology to Chemcat Japan. In 2026 — today — Europe has zero commercial ethanol-SOFC factories.
Read that again. Seventeen years between the scientific breakthrough and the Asian licence. In those seventeen years, Europe has poured billions into battery gigafactories, hydrogen corridors and SDE wind farms. That is money already burned — sunk into an assumption that seemed obvious in 2016 but is no longer valid in 2026.
Stellantis stopped its hydrogen programme in 2025c. Bosch discontinued its SOFC divisiond. Volkswagen, Mercedes and Stellantis had worked on ethanol fuel cells within the IPEN consortium since 2017 and withdrew strategicallye. Not because of a lack of technology. Because of a lack of policy direction. European industry received no signal that this route was permitted.
Meanwhile, Nissan was driving ahead. So was Doosan. Weichai began licensing. Bloom Energy scaled up. Ceres Power signed contracts in Korea. The window closed in Europe while it stood wide open in Asia. They were the coachmen there. We stood watching.
What we learn from fifteen years of falling behind on battery production:
Europe lost the battle for the lithium-ion cell in ten years. CATL, BYD and LG now have 73 per cent of global capacity. We are paying billions in subsidies to European gigafactories that will never become cost-competitive. We are now making the same mistake on the hydrogen route. And without intervention, on the ethanol-SOFC route too.
The three blocks below show why this cannot continue. The figures are not political. They are physical and economic. They show one route that wins without a single cent of subsidy. Anyone who does not take that route is consciously choosing the luggage rack.
Europe already has everything — today, not tomorrow
The strongest counterargument to everyone who says this is too ambitious: every building block we need is already in place. No Marshall Plan. No ten years of preparation. No billions in upfront investment. The four foundations:
One. The unemployed are waiting for work. Spain has 2.6 million unemployed people. Italy 2.0 million. France 2.4 million. Germany 2.8 million. The Netherlands 380,000. A large proportion have technical or practical training. The Carbon-Alert chain needs staff at precisely those levels: pellet production, distillation operations, SOFC installation, maintenance and BiCRS CO₂ logistics. Permanent, non-outsourcable jobs. Spread across all regions. Not Silicon Valley work — industrial labour. That is where Europe excels.
Two. The infrastructure is already there. 120,000 filling stations in Europe. Mechanically identical for petrol, diesel and ethanol — only the labelling and calibration change. More than 1,200 EU pellet factories that can directly supply cellulose feedstock. 70,000 km of existing gas pipeline, suitable for regional ethanol distribution. Distilleries in every grain, beetroot and wine region. Empty industrial sites where coal, refining and automotive facilities once stood — ready-made locations for BiCRS+SOFC hubs.
Three. The technology is proven. No prototype. No proof of concept. No ‘still needs scaling up’. Nissan has been operating a 70-per-cent-efficiency ethanol-SOFC on bioethanol at trial scale in Tochigi since 2026. Ceres Power is supplying 50 MW of SOFC stacks to Doosan this year, along with the production licence to Weichai. Lawrence Berkeley has demonstrated that an HEA catalyst can operate with 80 per cent less precious metal. Brookhaven solved C–C splitting at room temperature back in 2009. PNAS demonstrated 99.9 per cent CO₂ selectivity in 2022. This is not risk research. This is implementation.
Four. The learning curve is documented. Not by consultants. By the International Energy Agency Bioenergy Task 39, as early as 2020, using measurement data from cellulose factories now operating. €0.55 per litre today. €0.45 in 2030. €0.30 in 2036. €0.25 in 2040. An 18-per-cent learning rate on the SOFC stack. The same curve that reduced solar-panel LCOE sixfold between 2010 and 2020 — only now applied to a liquid fuel that does not depend on the Sahara or the seabed of the North Sea.
So what is missing is not money. What is missing is not the technology. What is missing is not the market.
What is missing is a European coachman who sees that everything is already in place — and takes the reins.
Block 1
The source
What does a megawatt-hour of primary energy cost at the factory gate — without any subsidy?
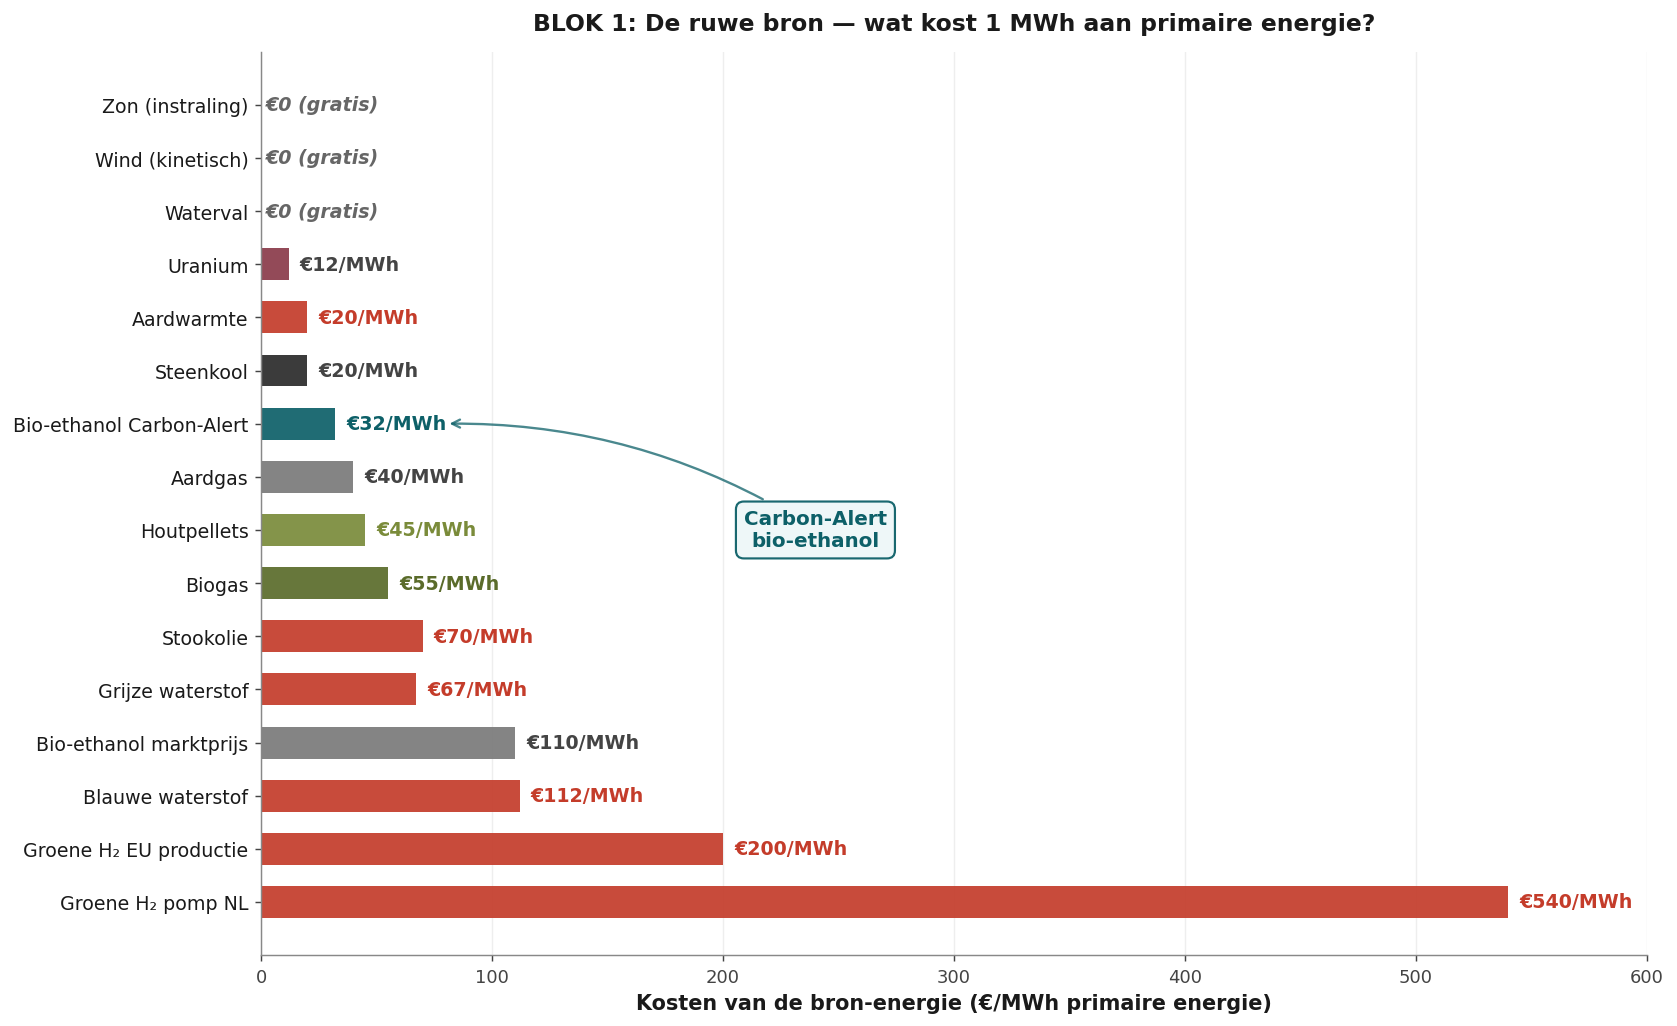
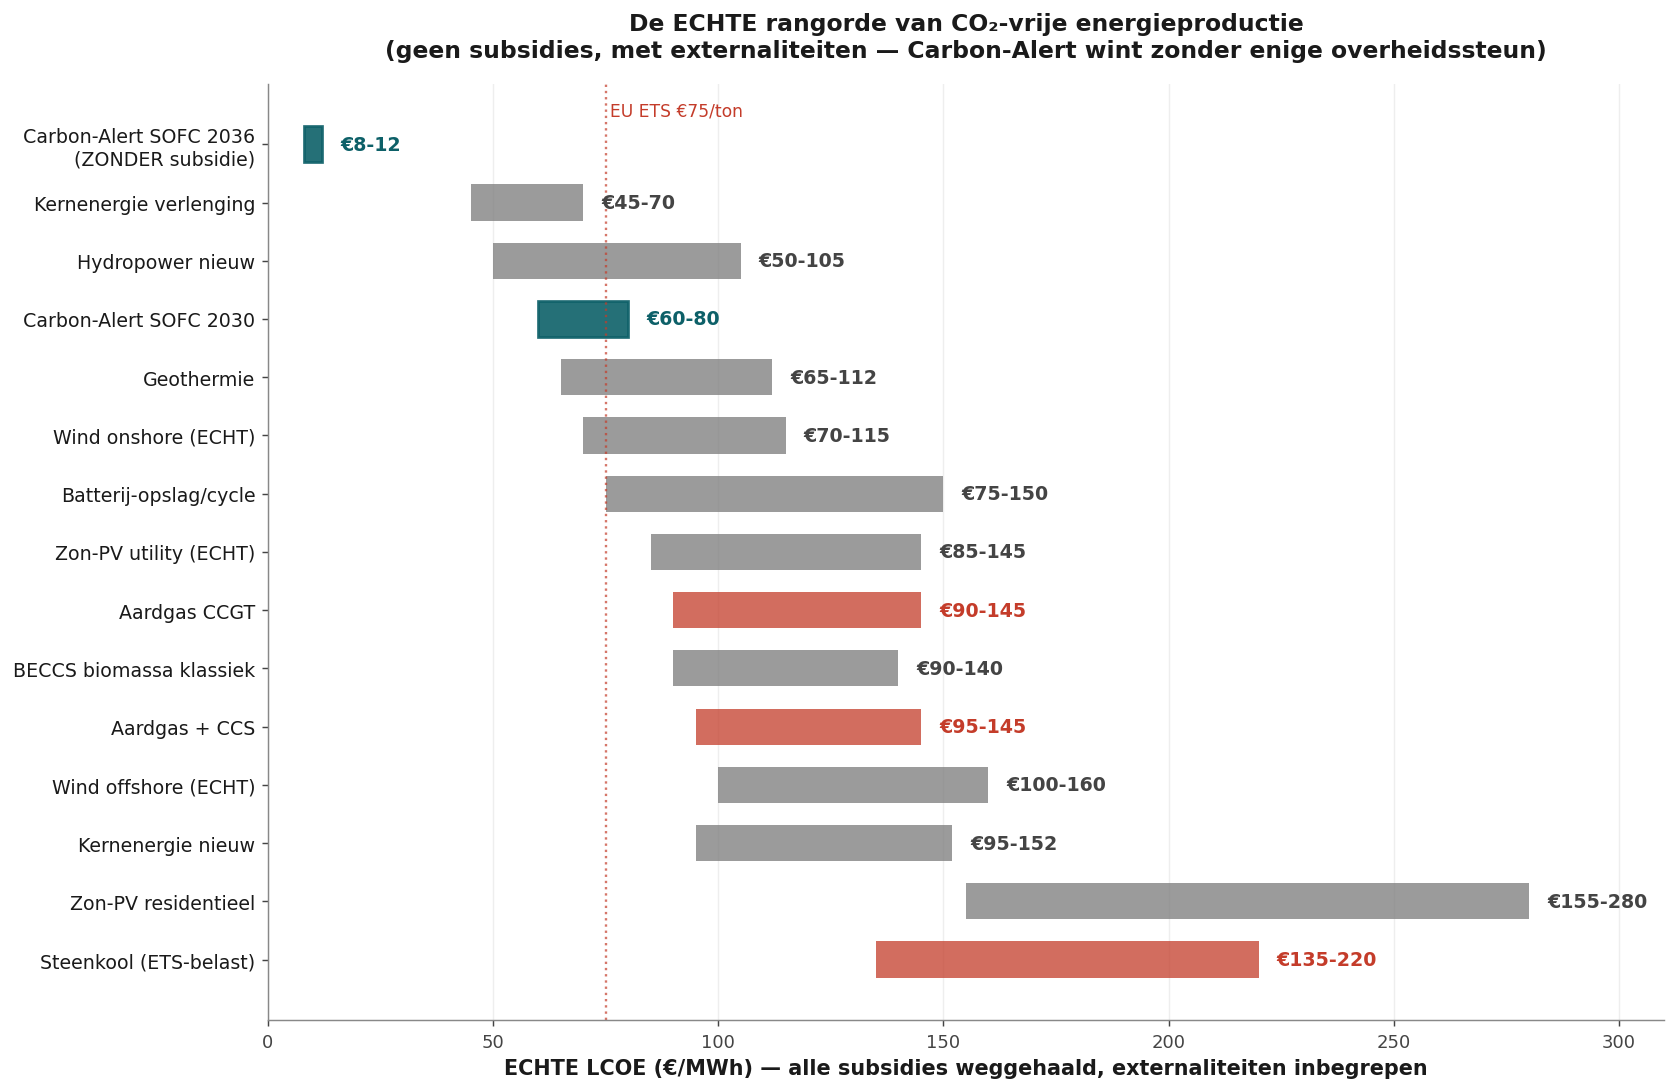
The ranking is brutal. Sun, wind and water power — free. Uranium €12 per megawatt-hour. Geothermal energy €20. Carbon-Alert bioethanol €32. Natural gas €40. Wood pellets €45. Heating oil €70. Grey hydrogen €67. Green hydrogen at the Dutch pump: €540 per megawatt-hour.
Five hundred and forty. Against thirty-two. That is not a detail. That is an order of magnitude against which no subsidy can compete. Anyone keeping the Dutch hydrogen route at the pump pays structurally seventeen times the price of the cheapest alternative. No consultant can fix that. No Brussels directive can fix that.
The physics behind green hydrogen is unfavourable and will remain so. Electrolysis requires 52 kilowatt-hours of electricity per kilogram of hydrogen. Compression to 700 bar costs another 10 per cent. Transport and storage another 15. Every loss factor compounds. This is not a technology that becomes better with scale — it is a technology whose structural costs are embedded in the laws of nature.
Cellulosic bioethanol does the opposite. Pellet feedstocks are local, residual streams and compatible with BECCS. The learning curve runs from €0.55 per litre today to €0.25 in 2040 — without policy allocation. This has been documented by IEA Bioenergy Task 39 since 2020. It is not a forecast. It is a measurement in cellulose factories that are operating now.
Block 2
The conversion
What does it cost to turn that source into a usable service — electricity or heat?
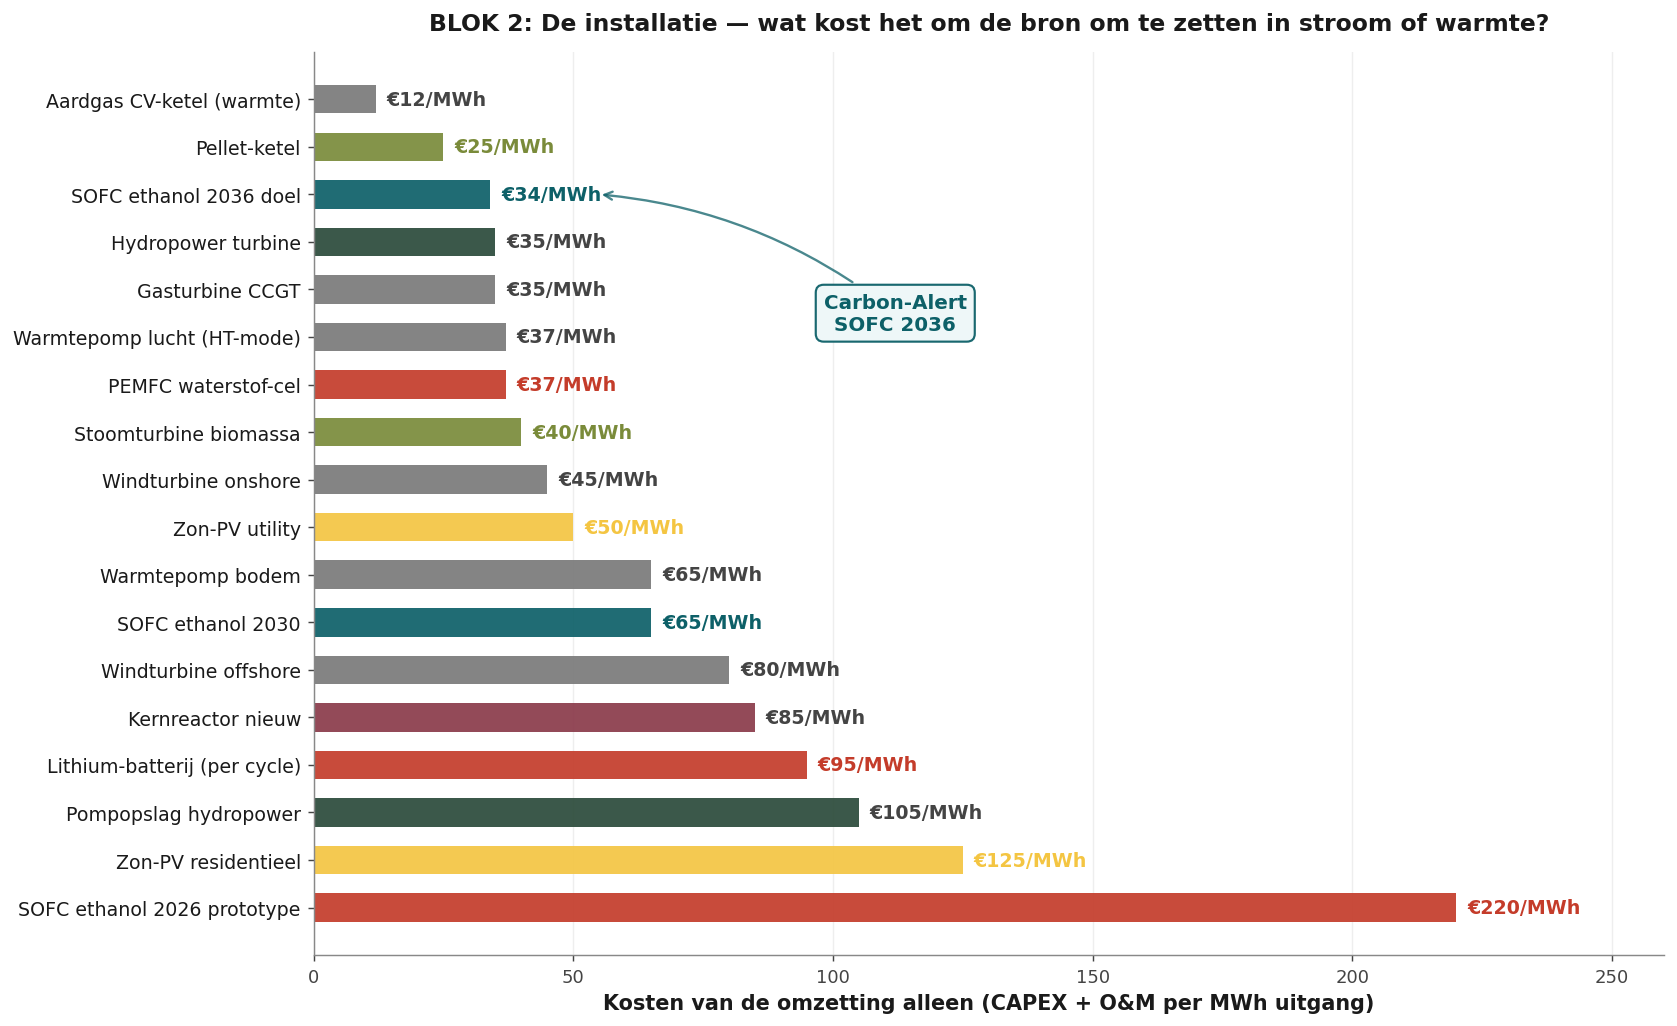
A natural-gas boiler runs at €12 per megawatt-hour for conversion — but then you are burning fossil fuel. A pellet boiler at €25. Ethanol-SOFC 2036 at €34. A CCGT gas turbine at €35. A PEMFC hydrogen fuel cell at €37. Biomass steam turbine €40. Onshore wind turbine €45. Utility-scale solar PV €50.
Residential solar PV: €125 per megawatt-hour. Eight times more expensive than the utility-scale version. The economics of the small panel on the small roof do not work without subsidy. That is the truth behind every domestic solar garden in the Netherlands: without the net-metering scheme, every installer would stop tomorrow.
The ethanol-SOFC currently stands at €220 per megawatt-hour for conversion in 2026 — a prototype. By 2036, this falls to €34. That is not an optimistic projection. It is the cost curve that Bloom Energy, Doosan, Ceres Power and Weichai are demonstrating today. A six-to-eightfold cost reduction in ten years — comparable to the reduction in solar-panel LCOE between 2010 and 2020.
Those who enter now buy at the prototype rate and ride the learning curve. Those who wait will buy in ten years at the Japanese licensing rate. The difference between these two attitudes is the difference between coachman and passenger.
Block 3
The end system
What does the user pay per delivered service — kilowatt-hour, hundred kilometres, megawatt-hour of heat?
Only at this third step do we compare like with like. Source plus conversion plus externalities. Per service actually consumed by the end user.
3a · Stationary electricity
| End system 2036 | Final price | Explanation |
|---|---|---|
| Carbon-Alert SOFC ethanol | 9,97 c€/kWh | 24/7 power, CHP heat bonus |
| Onshore wind + battery | 12–16 c€ | 40% capacity factor + storage |
| Commercial natural-gas genset | 13–17 c€ | Including ETS €100/tonne |
| Residential solar PV + battery | 14–18 c€ | 30% capacity factor |
| Spanish commercial grid | 21,5 c€ | End-user market price |
| Diesel genset | 28–32 c€ | Fuel €1,70/L, 38% efficiency |
| Green H₂ fuel cell | 30–40 c€ | H₂ €6/kg, 55% cell efficiency |
3b · Mobility per hundred kilometres
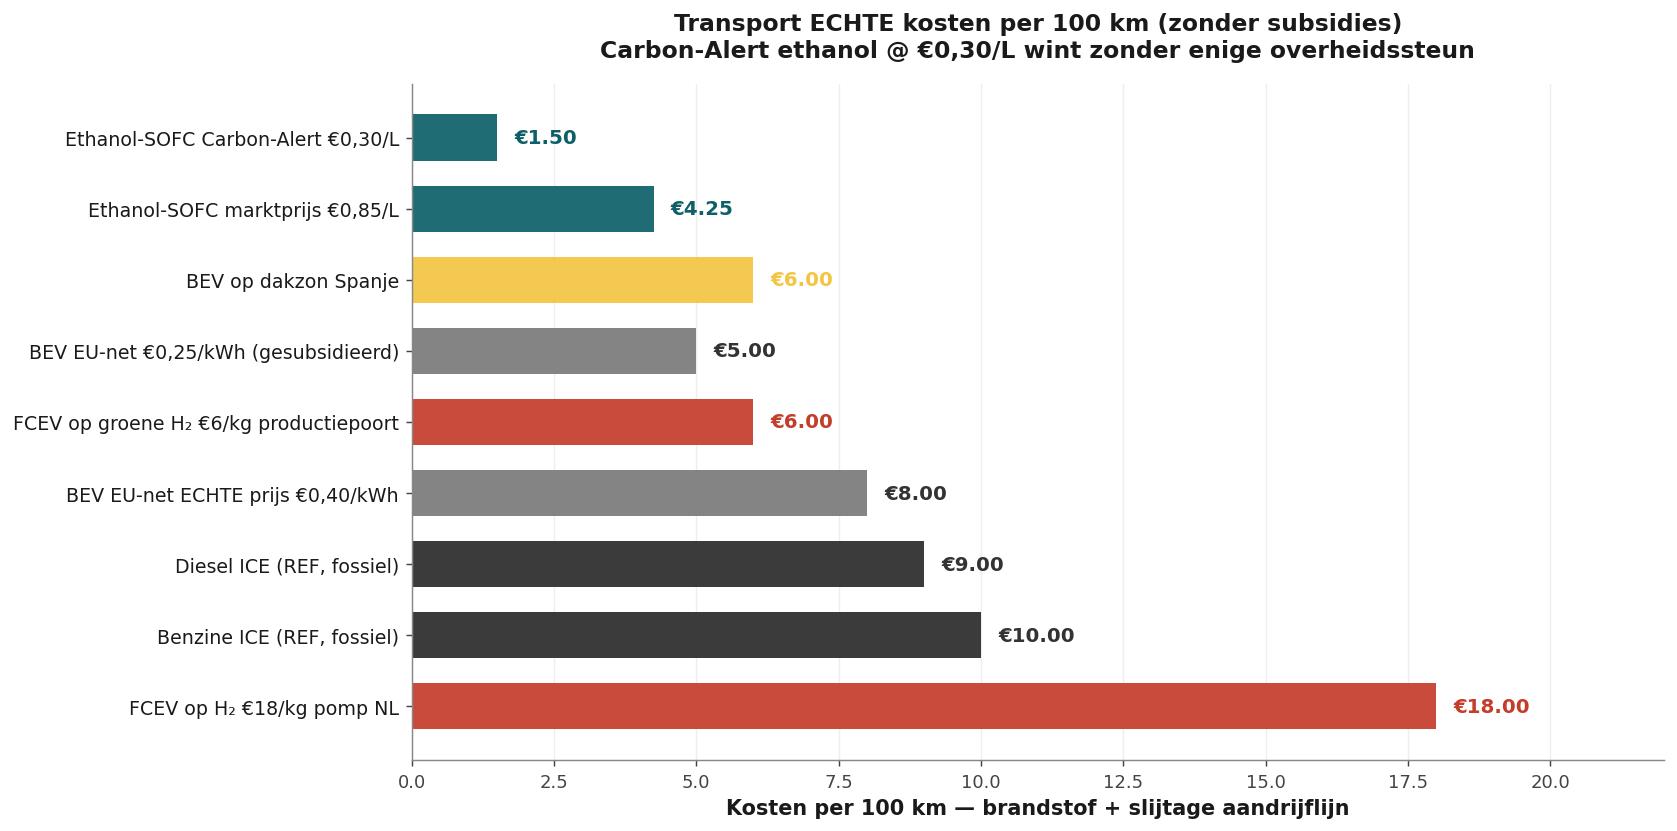
| Drivetrain 2036 | Consumption | € / 100 km |
|---|---|---|
| Ethanol-SOFC (€0,30/L) | 5 L/100km | €1,50 |
| BEV on grid (21,5 c€/kWh) + battery depreciation | 17 kWh/100km | €5,15 |
| Diesel (€1,80/L) | 5 L/100km | €9,00 |
| Petrol (€1,70/L) | 6 L/100km | €10,20 |
| BEV at rapid charging (~50 c€/kWh) | 17 kWh/100km | €8,50 |
| Hydrogen pump (€18/kg) | 1 kg/100km | €18,00 |
3c · Heating per megawatt-hour
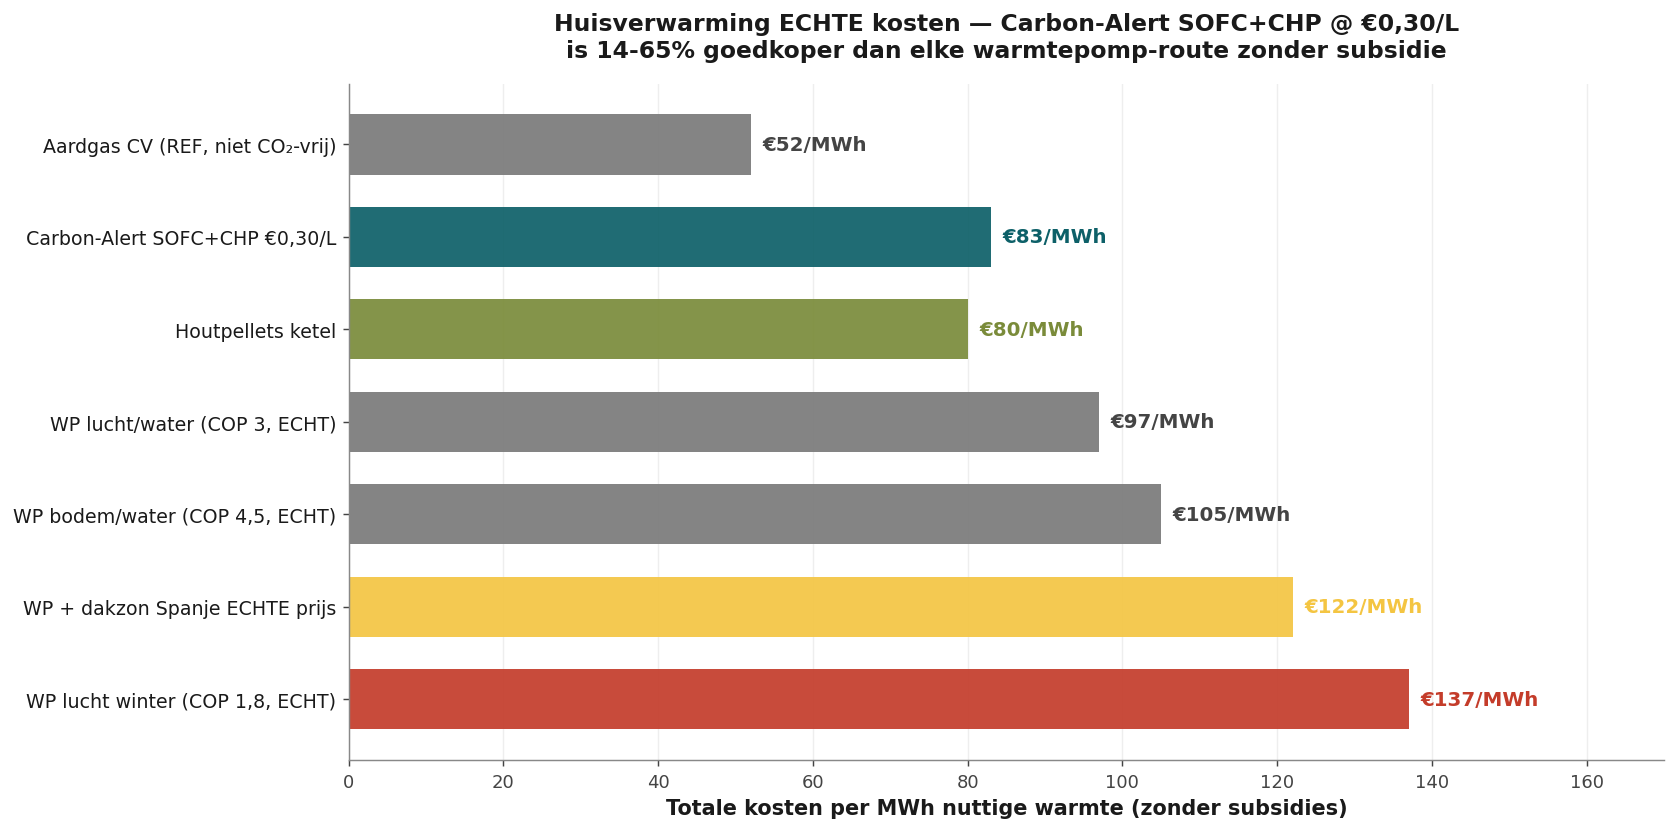
| Heating system 2036 | Final price MWh | Explanation |
|---|---|---|
| Carbon-Alert SOFC + CHP | €83 | Electricity + heat combined |
| Pellet boiler | €90–€110 | Own pellets, no subsidy |
| Heat pump on unsubsidised wind | €97–€137 | COP 3,2 · electricity 13–18 c€/kWh |
| Heat pump on grid electricity | €110–€150 | COP 3,2 · electricity 21,5 c€/kWh |
| Natural-gas boiler (€1,40/m³) | €140–€160 | 95% efficiency, ETS included |
| Heating oil | €170 | €1,20/L |
| Hydrogen boiler at €6/kg | €240 | 40 kWh/kg, 95% efficiency |
The great misconception in the Dutch heat-pump debate:
The true wind-electricity price without SDE subsidy is not 6 to 9 cents per kilowatt-hour. It is 13 to 18 cents. That puts a heat pump at €97 to €137 per megawatt-hour of heat — not €60 as the Climate Agreement figures suggest. Ethanol-SOFC+CHP operates at €83. Without any support. And with a BECCS CO₂ bonus that nobody pays for.
The business case — 100 kW hub, paid back in three years
A 100-kilowatt Carbon-Alert hub costs €180.000 to build. It produces 800.000 kilowatt-hours per year at a capacity factor of 91 per cent. Market value of that electricity: €172.000. Plus €18.000 in heat as a CHP bonus. Fuel costs: €32.400. Maintenance: €8.000. Stack depreciation: €90.000. Net margin in year one: €59.600. Payback period: three years.
No subsidy. No feed-in. No RED bonus. No BPM exemption. No ETS credit. Only sales at the grid price of a product with genuine production costs.
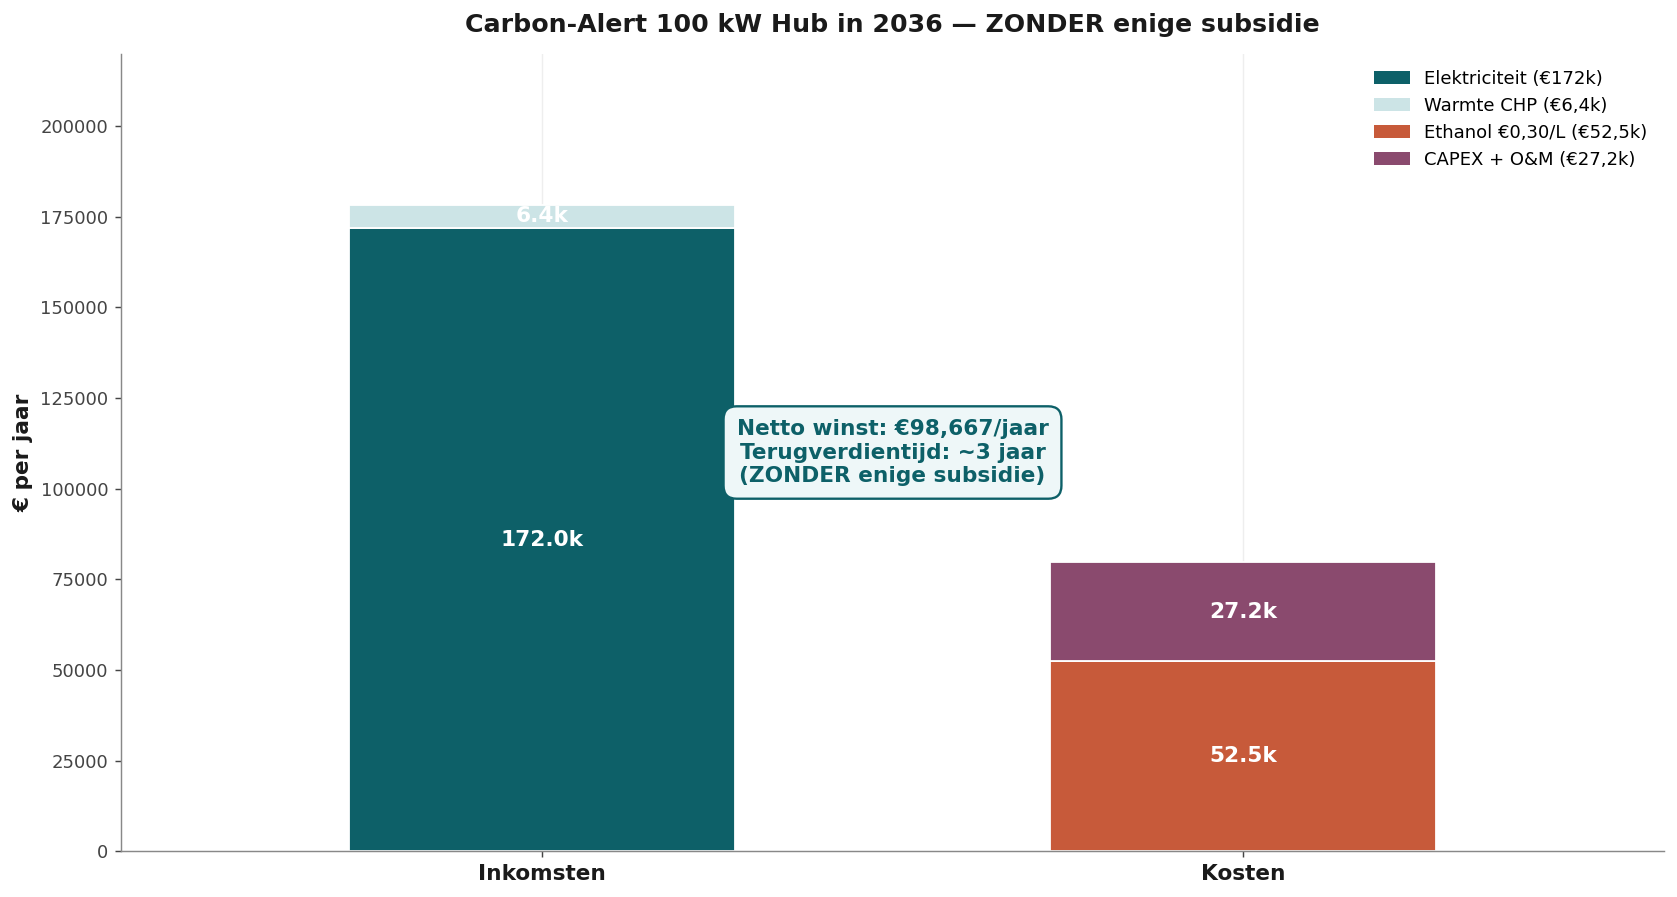
| Item | Amount | Explanation |
|---|---|---|
| CAPEX 100 kW hub | €180.000 | €1.800/kW × 100 kW, balance of plant included |
| Annual electricity production | 800.000 kWh | Capacity factor 91 per cent, 8.000 full-load hours per year |
| Annual electricity revenue | €172.000 | Sold at market price of 21,5 c€/kWh |
| Annual CHP heat revenue | €18.000 | 20 per cent heat utilisation × €0,11/kWh |
| Total annual revenue | €190.000 | Market prices, no feed-in tariff |
| Fuel costs | −€32.400 | 108.000 L ethanol × €0,30/L |
| OPEX and insurance | −€8.000 | 1,5 per cent of CAPEX per year |
| Stack depreciation + depreciation allowance | −€90.000 | Linear, two years effective |
| Net margin year 1 | €59.600 | Rises to €100.000+ from year 4 |
| Payback period | ≈ 3 years | Without a single cent of subsidy |
| Optional: SDE++ BECCS bonus | +€70.000/year | Shortens payback period to approximately 1 year |
The distinction must be clear: without subsidy, a hub pays for itself in three years. With SDE++ in one year. Both figures are robust. The real story is that the technology stands on its own. That is the message to every government: you do not need to give money. You only need not to get in the way.
The summary in one table — and whoever reads it now decides
Four columns. Eight rows. One route that wins structurally. Anyone who sees this table and does nothing is consciously choosing the luggage rack.
| Dimension 2036 | Ethanol-SOFC | BEV | Hydrogen | Natural gas |
|---|---|---|---|---|
| Source per kWh | 4,1 c€ | 5–7 c€ | 15–20 c€ | 7–12 c€ |
| Conversion CAPEX | €1.800/kW | €500–€1.000/kW | €1.500/kW + €60k car | €1.800–€3.000 |
| Final price c€/kWh | 9,97 | 14–18 | 30–40 | 11–15 |
| € per 100 km | €1,50 | €5,15–€8,50 | €18,00 | n/a |
| € per MWh heat | €83 | €97–€150 | €240 | €140 |
| Externalities | BECCS −CO₂ | Li/Co/Ni clean-up | Pt + clean-up | CO₂ + clean-up |
| Politically dependent? | NO | YES (SDE) | YES (mass subsidy) | YES (ETS exemption) |
On every metric that matters to your voter, shareholder or taxpayer — €/kWh, €/100 km, €/MWh heat — ethanol-SOFC wins in 2036. Not because a politician decides so. Because the physics and the learning curve are there.
The only reason this picture does not dominate the current policy debate: subsidies artificially reduce the visible price of competing routes. This document shows the real price.
What if the price develops differently? — risks assessed honestly
No business case without an honest risk section. Below are the six scenarios people put forward when they want to wait — and what actually happens under each scenario.
| Risk | Probability | What happens |
|---|---|---|
| Ethanol price falls more slowly than €0,30/L | Medium | Hub remains profitable up to €0,45/L. Only the payback period extends to 4,5 years. |
| SOFC CAPEX remains at €3.000/kW | Low | Doosan, Weichai and Bloom have already announced production capacity. |
| Grid price falls instead of rising | Low | EU grid CAPEX and CO₂ pricing make a fall extremely unlikely. |
| Hydrogen makes a comeback | Very low | Bosch/Stellantis exits, Hyundai delays — H₂ is structurally more expensive. |
| Political subsidy push for electric/H₂ | High | Irrelevant. The Carbon-Alert accounts close without subsidy — no exposure. |
| BECCS credit disappears | High | Irrelevant. We do not include it already — so there is no impact. |
Carbon-Alert's structural advantage is precisely that the design does not depend on the whims of politicians and their subsidy schemes. When an SDE++ scheme collapses, the business plan built on it collapses. Carbon-Alert's break-even does not change. Our business case rests on market fundamentals — not public goodwill.
What history teaches us — and why we must intervene now
In 1995, Japanese car manufacturers began working on hybrid drivetrains. Europe said: too complex, too expensive, not scalable. Twenty years later, we bought Toyota's Prius technology through licences.
In 2001, BYD began making lithium-ion batteries for cars. Europe said: too unsafe, too unprofitable. Fifteen years later, European gigafactories are opening with Chinese cells and Chinese production lines.
In 2009, Brookhaven published evidence that ethanol could be oxidised cold. Europe said: interesting chemistry, but the hydrogen route has been chosen. Seventeen years later, Brookhaven is licensing to Chemcat Japan.
Three times, the same pattern. Each time, an Asian player saw the opportunity and acted. Each time, a European consensus waited for consensus. Each time, it ended with us paying for licences we could have sold ourselves. Three generations of taxpayers, the same bill three times.
The ethanol-SOFC route is the fourth opportunity. And perhaps the last. Because once Japan, Korea and China have scaled up their factories, the window will be closed. Not because the technology is protected, but because the economies of scale are irreversible. Whoever is first to reach a million units determines the price for everyone who follows.
What you can put on your desk — today
Five decisions that cost no money and change everything
- Accelerated permitting — decide that BiCRS and SOFC installations must be permitted within six months. Not in two to three years. An internal directive to Spatial Planning and Permitting. It costs nothing. It gains two years of advantage.
- Policy neutrality — abolish the implicit BEV monopoly in zero-emission classifications. Ethanol-SOFC receives the same rights as battery-electric. No preference, no exclusion. A signature.
- E100 pump standard — ask the European Commission for a standard for modified petrol pumps that can dispense ethanol. Existing pump infrastructure, modifiable for a few thousand euros per installation. Not a billion-euro package, a European CEN standard.
- Public procurement — allow hospitals, data centres, barracks and public buildings to choose Carbon-Alert hubs without formal barriers in procurement guidelines. No preference, only access. Something your own procurement department can arrange.
- Education and vocational training — include ethanol operations and SOFC maintenance in 500 European vocational colleges. A twelve-week module. Do not wait until the technology is in place — train for it. For the regional economy and employment.
The choice is on the table — and the table is not empty
The coachman sees the road. He decides. The passenger on the luggage rack looks backwards and waits. Both are choices. But you make the second choice by doing nothing. The first choice requires movement today.
The figures are there. The technology is there. The learning curve is running. The Japanese factories are operating. The Asian licences are ticking over. What is missing is not the technology, not the market, not the science. What is missing is a European coachman who sees what is already visible and takes the reins.
Carbon-Alert Ltd is based in Malta and Mallorca. The design has been developed. The learning curves are documented. The business case has been calculated without any subsidy. It is waiting for one thing — a European partner, a European minister, a European investor who sees what is on the table here and acts.
Those who wait for others to see it will soon be sitting at the back again. Those who see and act now will sit on the box seat.
That decision does not lie with Brussels. It lies with you.
Further reading — this triptych belongs together
Three documents, one message
- 1. This article — On the box seat or on the luggage rack. The manifesto. The thesis. The choice.
- 2. Vision 2036 — Carbon-Alert Energy Hub. The technical design. 100 kW modular SOFC hub, LCOE analysis, five building blocks, cash flow, risk matrix. The evidence underpinning the thesis.
- 3. Open letter to the governments of Europe. The appeal. Five questions that cost no money. 350,000 jobs, €9 bn annual revenue, energy independence — without a single cent of subsidy.