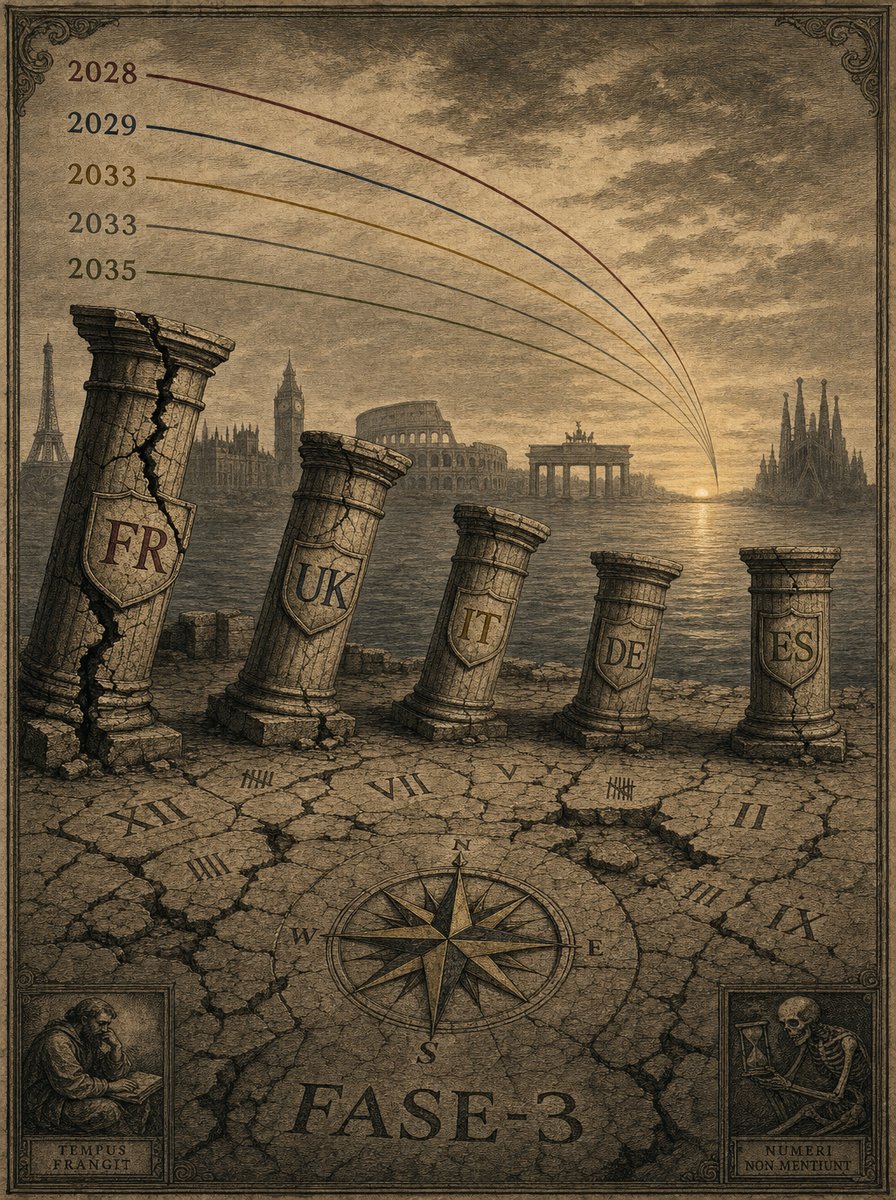
Five countries, five curves
Germany · France · United Kingdom · Spain · Italy. Five European phase-3 trajectories, stacked on one axis, anchored to Eurostat, Bundesbank, INSEE, ONS, ISTAT and INE.
Jacobus van Merksteijn
- Author --- Jacobus van Merksteijn
- Date --- 19 July 2026, Palma, Mallorca
- Section --- Political-economic forecast · Edition 2 (Tax policy) · European expansion on De Nederlandse Revolutie
- Countries --- France · United Kingdom · Italy · Germany · Spain
- Sources --- Eurostat 22 April 2026, Bundesbank 31 March 2026, INSEE June 2026, ONS May 2026, ISTAT July 2026, INE 2025, Banco de España 2025, EC Spring Forecast May 2026, Le Monde, Reuters, The Guardian, Il Corriere, Federal Reserve St. Louis, World Bank, Brookings, OECD, Skocpol (1979), Goldstone (1991)
- Method --- Four-phase model of political sociology, curve analysis of Russia/Argentina/South Africa, comparative fiscal-industrial analysis of five major EU countries
Five major European countries are simultaneously displaying early warning signs of a phase-3 systemic crisis. France goes first, sometime between 2028 and 2031, with a trough around 2036. The United Kingdom follows shortly afterwards. Italy and Germany fall almost simultaneously in 2033–2036, for different reasons — Italy through debt, Germany through industry. Spain falls last and least deeply, between 2035 and 2043. Every figure in this forecast is anchored to a published source. Every sequence can be deduced from four verifiable parameters. Anyone who reads this curve can act — before the window closes.
1. Method and sequence
This forecast stacks five European countries on a single curve — the four-phase model from political sociology (Skocpol 1979, Goldstone 1991). Each country is measurably in phase 1 or 2, each enters phase 3 at a different point, and each reaches phase 4 at a different depth. The sequence is neither arbitrary nor guessed. It follows from four verifiable parameters:
- Political stability — number of cabinets and prime ministers that have fallen since 2022
- Fiscal position — debt ratio, deficit and refinancing costs according to Eurostat, Bundesbank, ONS, ISTAT, INE and Banco de España
- Rate of deindustrialisation — loss of industrial jobs in absolute figures
- Populist electoral momentum — polling ahead of the next elections
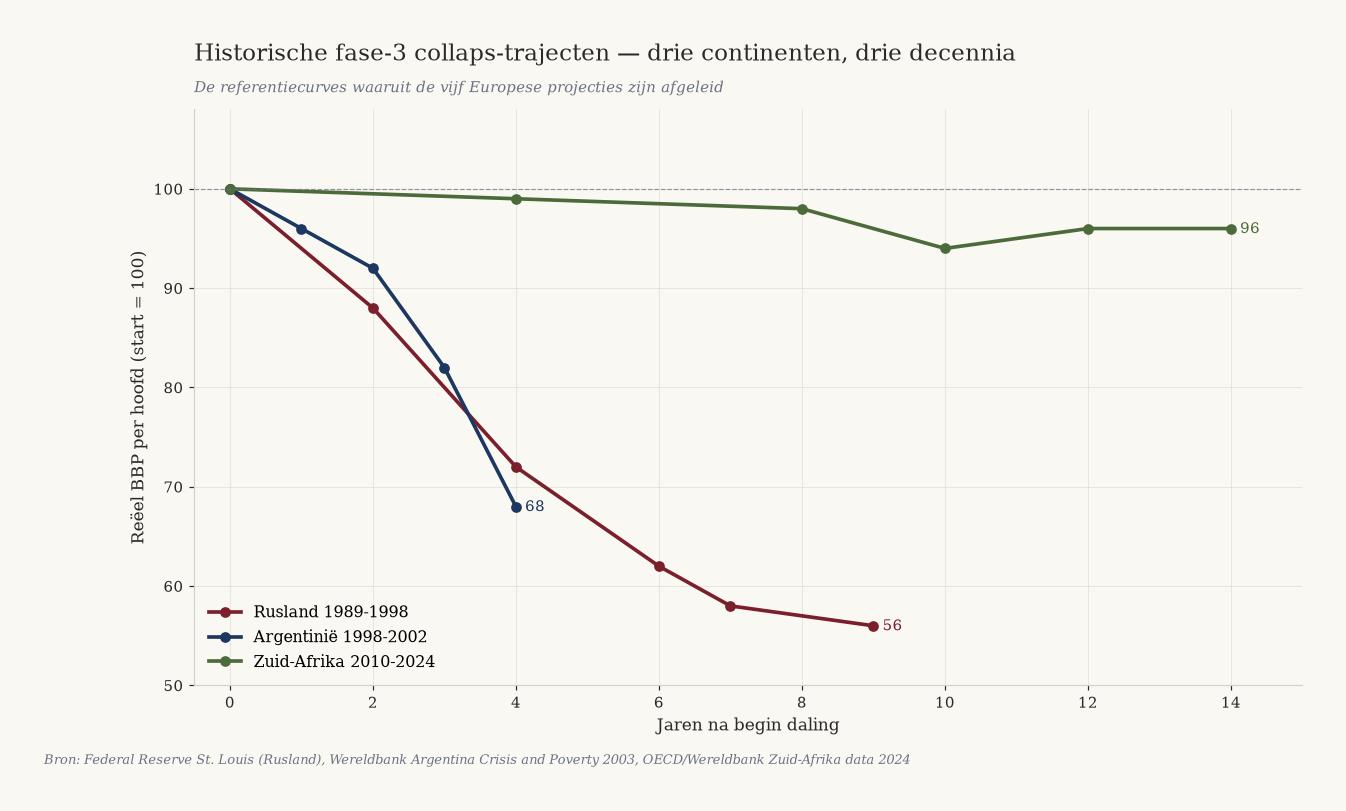
These parameters produce a sequence: France goes first, followed by the United Kingdom, then Italy and Germany almost simultaneously, with Spain last. Historical precedents (Russia 1991, Argentina 2001, South Africa since 2010) provide the curve shape and the scale of the loss of prosperity. In Russia, real GDP per capita fell to 56% of its 1989 level by 1998. Argentina lost more than 20% of GDP between 1998 and 2002. South Africa lost 4% of real GDP per capita between 2010 and 2024. These are the reference curves from which our projections are derived.
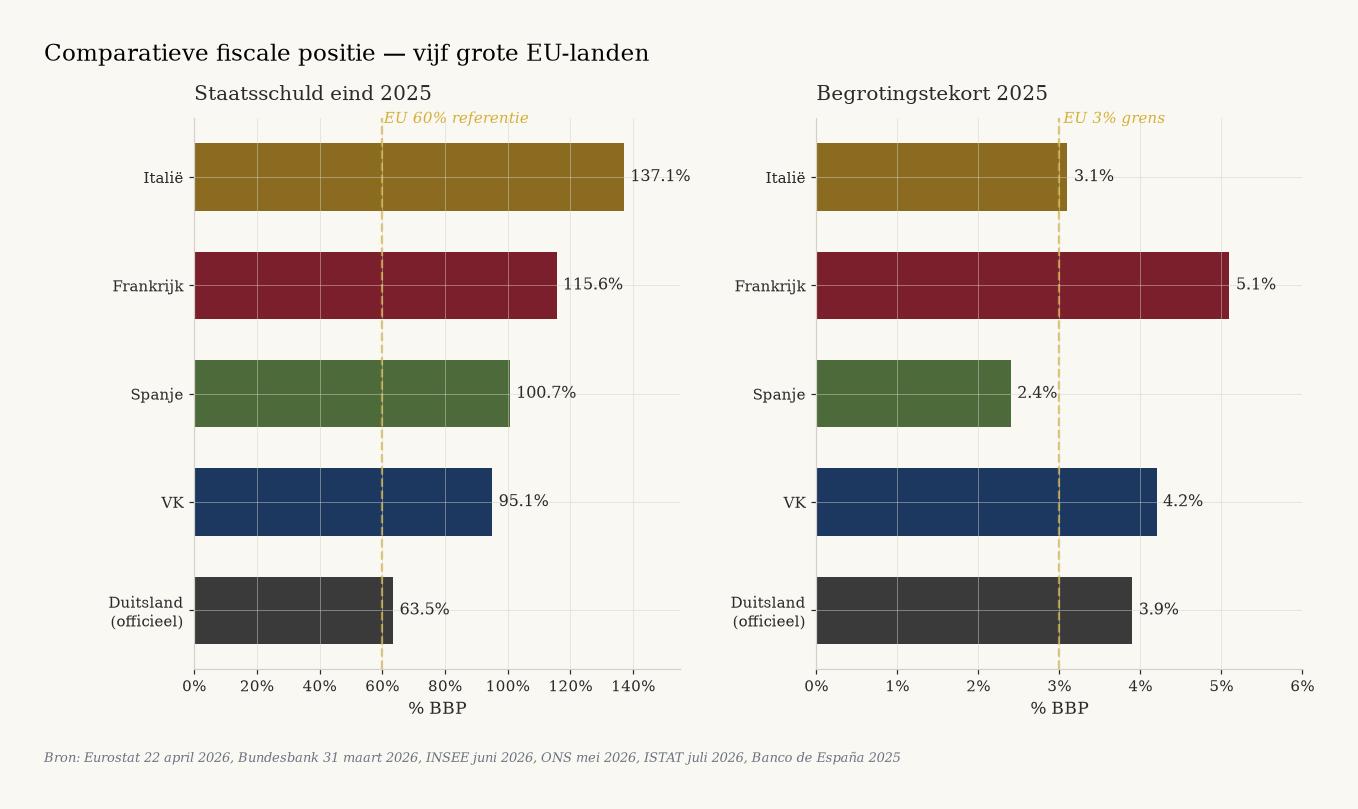
Comparative debt position 2025
| Country | Debt % GDP | Deficit % GDP | Trend |
|---|---|---|---|
| Italy | 137.1% | 3.1% | Rising to 139.2% in 2027 |
| France | 115.6% | 5.1% | Rising to 118.1% in 2026 |
| Spain | 100.7% | 2.4% | Falling below 100% in 2026 |
| United Kingdom | 95.1% | 4.2% | Rising moderately |
| Germany (official) | 63.5% | 3.9% | To 76.5% in 2028 |
2. France — the first to fall (phase 3: 2028–2031, trough in 2036)
France is fiscally, politically and industrially the most advanced in phase 2 and the most likely to enter phase 3 first. There are no rhetorical margins left.
Position in 2026
| Indicator | Value |
|---|---|
| Government debt Q1 2026 | €3,540bn (117.5% of GDP) |
| Deficit 2025 | 5.1% of GDP (2nd in the EU after Romania) |
| Interest burden 2026 → 2030 | €63bn → €120bn (more than the education budget) |
| Unemployment Q1 2026 | 8.1% (rising) |
| Youth unemployment Q1 2026 | 21.1% |
| Industrial jobs lost 2000–2021 | ~900,000 (-22%) |
| Governments fallen 2024–2025 | 4 (Attal, Barnier, Bayrou, Lecornu) |
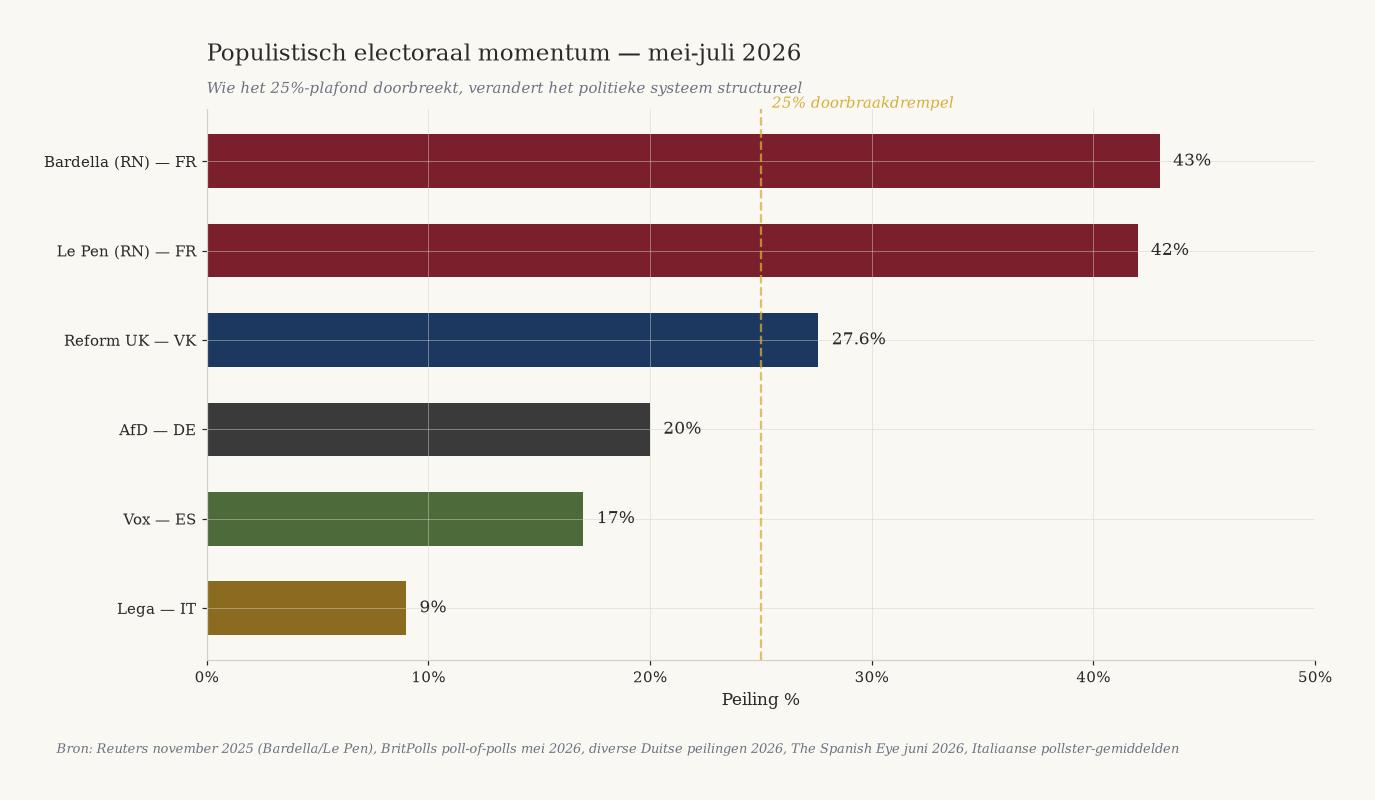
| Bardella 2027 (polling) | 43% in the first round |
Why France comes first
Four prime ministers have fallen in twelve months over budgets (Attal 2024, Barnier 2024, Bayrou 2025, Lecornu forced the 2026 budget through without a vote). This is no longer political normality. There has been no majority in the Assemblée since 2022. All legislation proceeds via Article 49.3 or minority deals.
The interest burden of €55bn in 2025 doubles to €120bn in 2030 — more than the entire education budget. It is structurally no longer sustainable without a foreign bailout or default. Youth unemployment at 21.1% in Q1 2026 is twice the EU average. Bardella (43%) and Le Pen (42%) dominate the presidential polls.
Food-poisoning figures have risen 42% since 2020, bakeries are closing in small municipalities, and more than 1,000 mayors have resigned since 2020 under fiscal pressure.
Predicted trigger and curve
By definition, the trigger for phase 3 is unpredictable in form but predictable within a time window. The most likely triggers for France in 2028–2031 are: presidential elections in 2027 bringing Bardella/Le Pen to power; a refinancing strike by investors (an interest-rate explosion); a new tax increase on the middle class leading to Gilets-Jaunes 2.0; or a banking crisis caused by exposure to French government bonds.
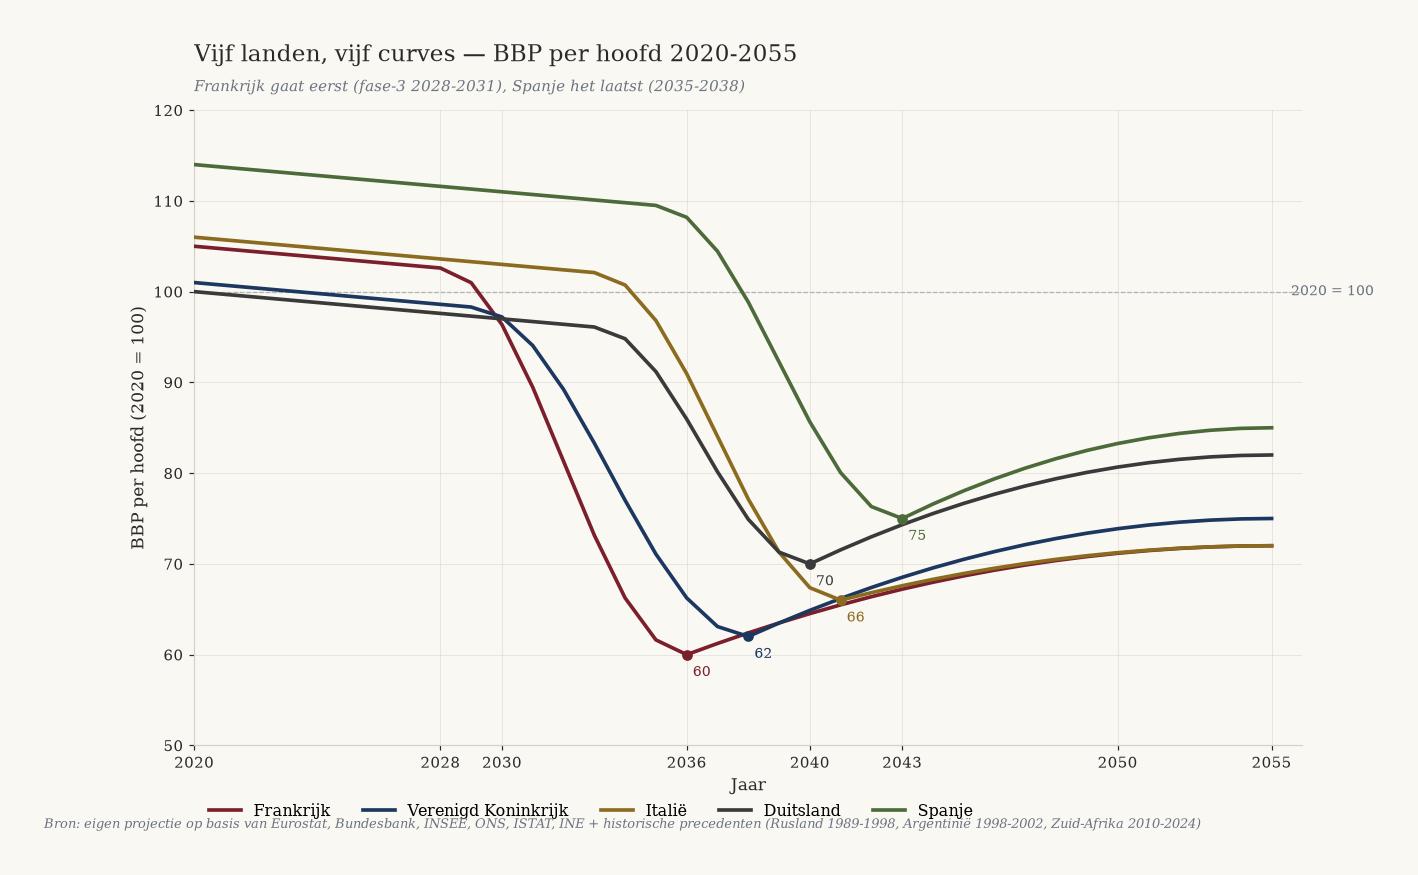
GDP per capita falls between 2028 and 2036 from 105 (2020=100) to approximately 60, followed by slow stabilisation at 72 by 2055. The precedent is Argentina 1998–2005: GDP per capita fell from $8,210 to $2,695. France will fall less deeply than Argentina (which had no eurozone safety net) but more deeply than Italy.
3. United Kingdom — the second (phase 3: 2029–2032, trough in 2038)
The UK is next after France in the danger zone. The combination of 95% debt, a 5% deficit, record-high youth unemployment and Reform UK at 27.6% in the polls points to phase 3 between 2029 and 2032.
Position in 2026
| Indicator | Value |
|---|---|
| Government debt May 2026 | £2.9 trillion (95.1% of GDP) |
| Deficit financial year 2025–26 | 4.2% of GDP |
| Unemployment February–April 2026 | 4.9% |
| Youth unemployment Q1 2026 | 16.2% (11-year high) |
| NEET young people (16–24) Q1 2026 | 1,012,000 (13.5%) |
| Reform UK polling May 2026 | 27.6% (largest party) |
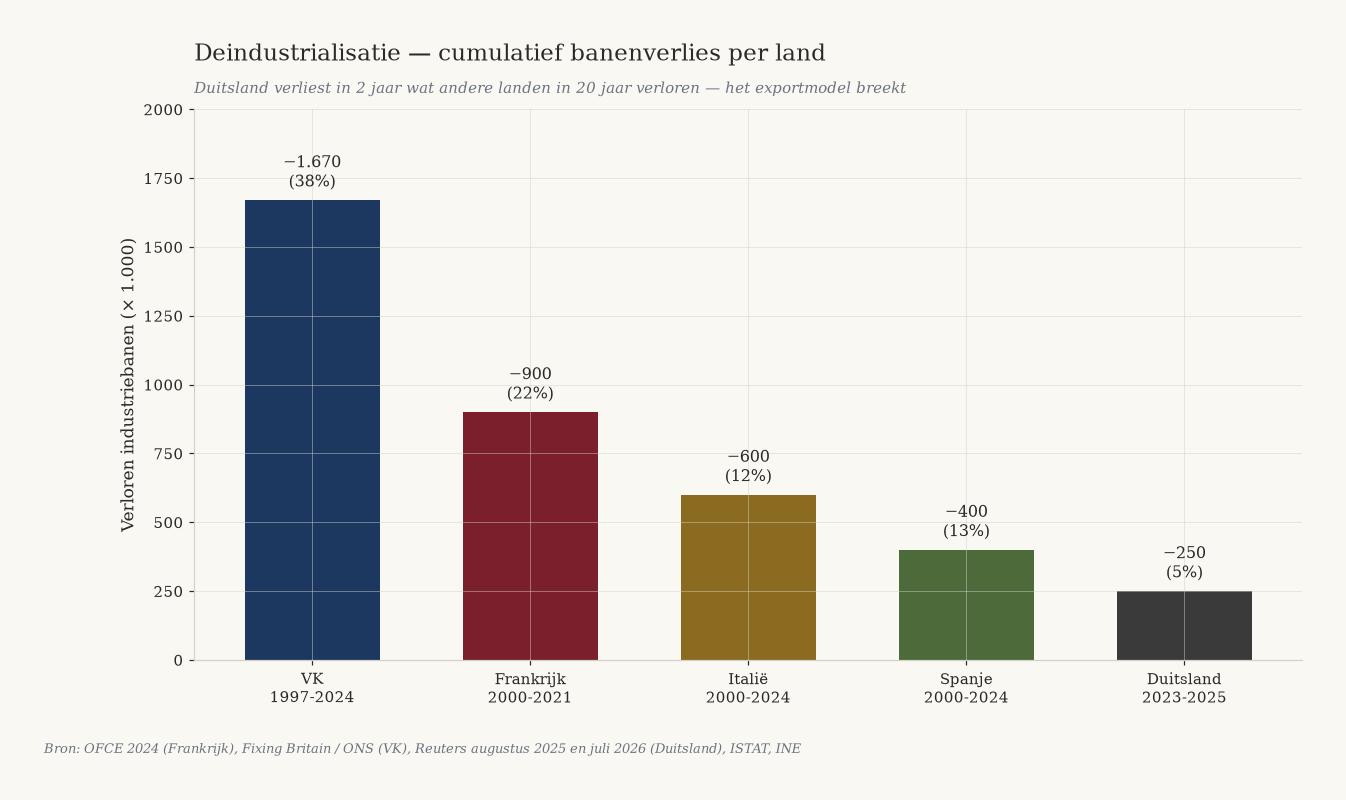
| Industrial jobs lost 1997–2024 | 1.67 million (-38%) |
Why the UK comes directly after France
In May 2026, Reform UK ranked first with every major pollster (YouGov, Opinium, Survation, More in Common, Ipsos). Farage could become prime minister at the next election. The 1,012,000 NEET young people represent an 11-year high. Youth unemployment now exceeds that of the eurozone. This is the kindling for phase 3.
Manufacturing jobs fell from 4.37 million in 1997 to 2.7 million in Q3 2024 — a loss of 1.67 million jobs (38%). Deindustrialisation is further advanced than in France or Italy. A deficit of 4.2% is the fifth-highest since 1993.
Predicted trigger and curve
The most likely triggers are: Reform UK winning the 2028–2029 election (a Farage government); a sterling crisis caused by fiscal distrust (Truss in October 2022 was the precursor); a migration-related incident with riots à la Southport 2024; or a banking crisis through commercial-property exposure.
GDP per capita falls between 2029 and 2038 from 101 (2020=100) to approximately 62, recovering to 75 by 2055. The UK has one advantage over France: its own currency, and therefore the option of devaluation. Its disadvantage: no ECB safety net, and historically greater dependence on the financial sector — a sterling crisis would have broader effects than a euro crisis.
4. Italy — the slow collapse (phase 3: 2033–2036, trough in 2041)
Italy has the highest debt in the eurozone (137.1%), but paradoxically one of the most stable political situations. Meloni is holding the coalition together; ISTAT reports youth unemployment at a record low. Nevertheless, the fiscal trajectory is unsustainable and the trigger will come through the refinancing market, not street protest.
Position in 2026
| Indicator | Value |
|---|---|
| Government debt at end-2025 | 137.1% of GDP (2nd in the EU after Greece) |
| Debt forecast 2027 | 139.2% (Italy becomes #1 in the EU) |
| Deficit 2025 | 3.1% |
| GDP growth 2025 | 0.5% (4th consecutive year below 1%) |
| Youth unemployment May 2026 | 15.1% (record low) |
| Tax burden 2025 | 43.1% (2nd consecutive increase) |
| Referendum March 2026 | Meloni lost, 53.2% to 46.8% |
Why Italy comes later than France but is not saved
Meloni is relatively stable politically — the FdI-Lega-FI coalition has existed since 2022, the longest-lasting coalition in decades. The March 2026 referendum defeat and the July 2026 defeat in the vote on the electoral law are signs of erosion, but not of a crisis.
Italian youth unemployment is falling (from 21% at the end of 2024 to 15.1% in May 2026). The NEET rate has fallen from 25.7% in 2015 to 13.3% in 2025 — the largest decline in the EU. The phase-3 fuel is not (yet) present.
Structural problem: GDP growth of 0.5% is too low to stabilise debt in this interest-rate environment. EC projection: debt rising to 139.2% in 2027, with no reversal before 2028. The trigger comes through the refinancing market: every rise in interest rates (for example, as a result of the French crisis) forces Italy to implement spending cuts that further suppress weak growth. This is the classic debt trap.
GDP per capita falls between 2033 and 2041 from 106 (2020=100) to approximately 66, recovering to 72 by 2055. Of all five countries, Italy has the longest history of stagnation: GDP per capita has barely risen since 2000. The collapse scenario is less an acute fall than a prolonged erosion.
5. Germany — the deindustrialisation implosion (phase 3: 2033-2036, low point 2040)
Germany has the strongest fiscal position (63.5% officially), but the most acute economic crisis: mass deindustrialisation in 24 months. Phase 3 comes not through debt but through industrial decline and the end of the export model.
Position in 2026
| Indicator | Value |
|---|---|
| Government debt at end-2025 | 63.5% of GDP (€2.84 trillion) |
| Forecast 2028 → 2037 | 76.5% (MinFin) → 85% (IW Köln) |
| Debt brake broken | March 2025 — €500 billion off-budget, 12 years |
| Industrial jobs lost 2023-2025 | ~250,000 |
| Industrial jobs lost in 2025 alone | 177,000 |
| VW announced redundancies | Up to 100,000, 4 factory closures |
| Implicit German pension liabilities | 391% of GDP (~€19.5 trillion) |
| AfD polling 2026 | ~20% (2nd national party) |
Why Germany falls later than France/the UK but more deeply
Fiscally, Germany is much stronger: 63.5% debt compared with France’s 115.6%. There is room to borrow. But Germany has broken the debt brake (€500 billion off-budget infrastructure fund for 12 years, with defence spending above 1% of GDP exempted) — not out of choice, but because it has to.
Deindustrialisation is the acute crisis. In two years, 250,000 industrial jobs have been lost; VW alone has announced 100,000 redundancies; BASF is closing factories in Ludwigshafen; ThyssenKrupp is warning of 1,200 steel jobs; Chinese competition in EVs, batteries and chemicals. The export model that underpinned 20 years of German success is falling apart.
Implicit pension liabilities of 391% of GDP: if corporate accounting were applied, Germany’s real debt would be 454%. Energy prices are structurally higher than those of competitors. The AfD is polling at ~20% nationally — the largest opposition party in the Bundesrat. Politically still manageable, but in the event of a sharp industrial crisis, phase-3 political fragmentation will come into view after 2030.
GDP per capita falls between 2033 and 2040 from 100 (2020=100) to approximately 70, recovering to 82 by 2055. Germany has two safety nets: eurozone membership and the strongest fiscal buffer of the five. Nevertheless, the decline will be deeper than Italy’s because the export model that supports 60% of German GDP has been structurally eroded. Precedent: British deindustrialisation 1975-1995 — a 30% loss of industrial jobs, followed by prolonged stagnation.
6. Spain — slow maturation (phase 3: 2035-2038, low point 2043)
Spain is the strongest economy of the five, with GDP growth of 2.8% in 2025 and falling debt. Yet a political crisis is building beneath these figures: PP+Vox consistently poll above 200 seats, Sánchez is faltering due to corruption investigations, and youth unemployment remains structurally high at 23%.
Position in 2026
| Indicator | Value |
|---|---|
| Government debt at end-2025 | 100.7% of GDP |
| Forecast 2026 | < 100% (for the first time since 2019) |
| Deficit 2025 | 2.4% (below the EU threshold) |
| GDP growth 2025 | 2.8% (strongest among the major eurozone economies) |
| Unemployment Q2 2025 | 10.29% |
| Youth unemployment Q4 2025 | 23.01% (structurally high) |
| PP+Vox polling June 2026 | ~200 seats (> 176 = majority) |
Why Spain falls last
Spain has the strongest economy of the five. GDP growth of 2.8% in 2025 is double the eurozone average. The deficit is below 3%. Debt is actively falling. This is phase 1, not phase 2. The Balearics and Costa del Sol are attracting a net inflow of German, Dutch and British wealth — precisely the “poor among the rich” pattern that draws crisis migrants from northern countries. Mallorca is one of the few EU locations with a stable inflow of wealth.
Youth unemployment remains structurally high at 23% — this is phase-2 fuel. But Spanish unemployment has historically survived 25% (2013-2014) without a phase-3 explosion. A different pattern from France and the UK. Sánchez is politically vulnerable but not gone. PP+Vox poll at 200 seats, but Sánchez retains regional alliances. Vox polls at 17% — strong, but not dominant as the RN is in France (43%).
The trigger will not come from Spain itself but from an external shock: the French crisis (2028-2031) infects Spanish banks holding French debt; the UK crisis (2029-2032) hits Spanish tourism; the Italian crisis (2033-2036) causes confidence in the ECB to plummet.
GDP per capita falls between 2035 and 2043 from 114 (2020=100) to approximately 75, recovering to 85 by 2055. Spain has the most resilient recovery potential thanks to its tourist appeal and the wealth-import model that draws northern crisis refugees to the Balearics and Costa del Sol.
7. Five curves on one axis
| # | Country | Phase 3 | Low point | GDP peak → trough | Recovery 2055 |
|---|---|---|---|---|---|
| 1 | France | 2028-2031 | 2036 | 105 → 60 (-43%) | 72 |
| 2 | United Kingdom | 2029-2032 | 2038 | 103 → 62 (-40%) | 75 |
| 3 | Italy | 2033-2036 | 2041 | 106 → 66 (-38%) | 72 |
| 4 | Germany | 2033-2036 | 2040 | 100 → 70 (-30%) | 82 |
| 5 | Spain | 2035-2038 | 2043 | 114 → 75 (-34%) | 85 |
Spain and Germany fall less deeply thanks to fiscal buffers (Germany) or economic resilience (Spain). France falls the deepest and recovers the least — the model based on government spending at 57% of GDP cannot be reconstructed.
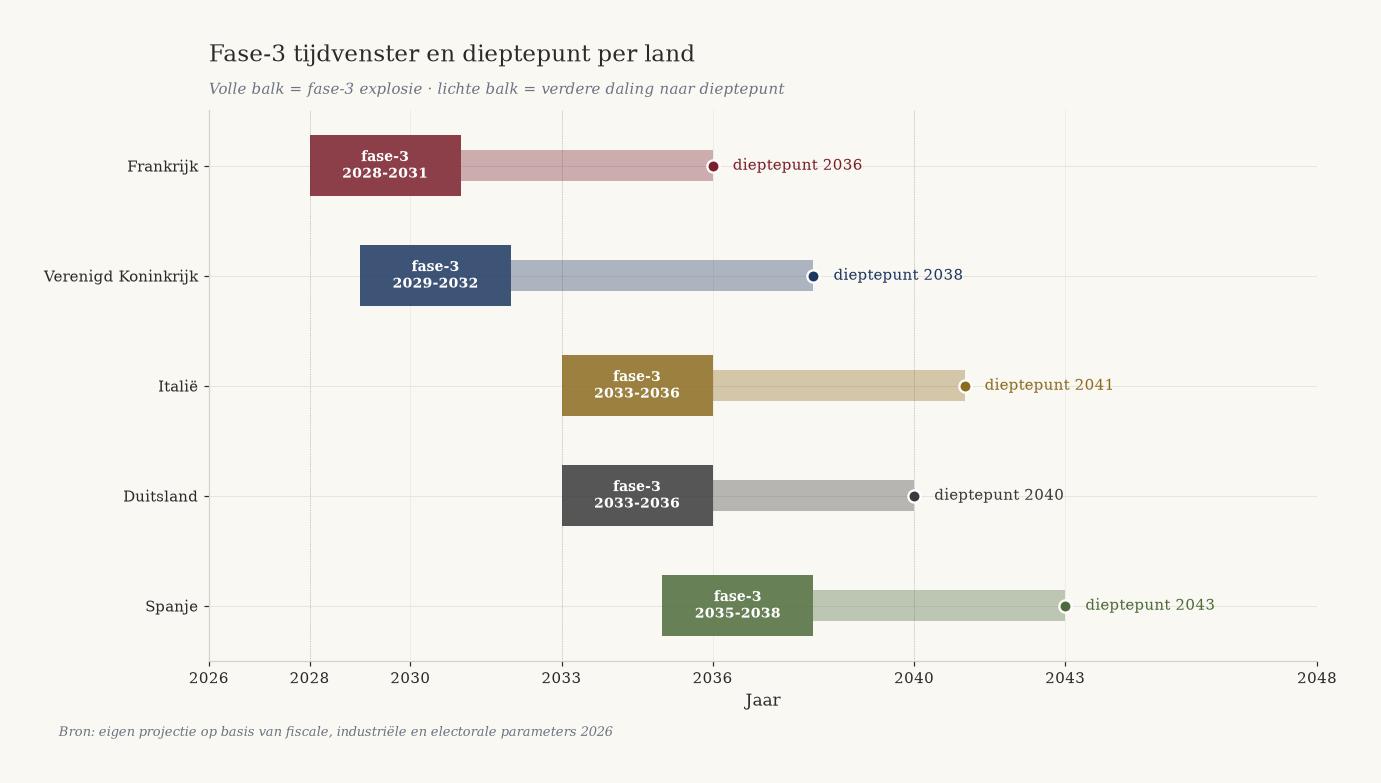
Five countries. Five curves. One pattern. Not a single curve points upwards.
8. What this means
For wealthy individuals and entrepreneurs
- Leave France before 2028 — capital, family or business. Move wealth to Switzerland, Luxembourg, Singapore or the Balearics.
- Leave the UK before 2029 if you oppose Reform’s policies, or stay and benefit from its reforms if you support them. The tax regime could shift dramatically.
- Italy: do not buy long-term Italian government bonds after 2028. The BTP spread rises with every ECB move.
- Germany: exit auto suppliers and chemical-sector suppliers before 2030. The migration of talent to the US, Switzerland and Singapore is already under way.
- Spain: property-buying opportunity in 2035-2040 (low point). The Balearics and Costa del Sol will become a safe haven for northern EU refugees — demand will rise structurally.
For politicians and policymakers
A loss of 30–45% of GDP per capita is not historically abnormal — Russia, Argentina and South Africa prove it. If comparable early warning signs manifest themselves simultaneously in five major EU countries, the assumption that ‘it cannot happen here’ is no longer defensible. EU bailout capacity is limited. When France, the UK and Italy enter crisis simultaneously (2028–2036), there is no fiscal reserve fund large enough. ECB QE will monetise default risk — the risk of hyperinflation will rise. Phase 3 prevention requires action before 2028–2029. After that window, any package will be crisis management only.
For journalists and publishers
Publish the figures by country, not as a European whole. The differences are the essence. Avoid ‘revolution’ and ‘collapse’ in headlines — they will be dismissed as sensationalism. Use ‘phase 3’, ‘systemic crisis’ and ‘erosion of prosperity’. Link every prediction to a verifiable source. Eurostat, Bundesbank, INSEE, ONS, ISTAT and INE — these agencies already publish the core figures. What is missing is aggregation and projection.
What can work
There is one alternative: radical, rapid, gradual systemic reversal — a CO2 certificate at source, a single-figure flat tax, SME protection, withdrawal of Brussels regulatory burdens, and the development of independent energy and industrial infrastructure. This is the ‘gradual exit’ that will work only if it is implemented within the next three to five years. After 2028–2029, that window will be closed.
9. What is solid, what is uncertain
What is solid
- Starting point 2025–2026: every debt ratio, every deficit and every unemployment figure is verifiable through the primary source (Eurostat, Bundesbank, INSEE, ONS, ISTAT, INE).
- Deindustrialisation trend: 250,000 German industrial jobs lost in two years, 1.67 million British jobs since 1997, and 900,000 French jobs since 2000 — empirically measured.
- Political instability in France: four prime ministers falling within twelve months is a historical fact.
- Populist polling: Bardella 43%, Reform UK 27.6%, Vox 17%, AfD ~20% — all verifiable.
- Historical precedents: Russia’s 44% GDP loss from 1989–1998, Argentina’s 20% loss from 1998–2002, and South Africa’s 4% loss from 2010–2024.
- Four-phase model: a consensus in political sociology since Skocpol (1979) and Goldstone (1991).
What is uncertain
- The precise timing of phase 3 may vary by 1–3 years. France could reach it in 2027 (a Bardella presidential crisis) or 2032 (a protracted impasse). Our midpoint is 2028–2031.
- The nature of the triggers is unpredictable in form. We identify the most likely ones based on historical precedents, but the actual event may be something else.
- The EU response could divert the trajectory. If the EU introduces a fiscal union with genuine transfer payments, the pattern for Italy and Spain could be milder.
- External shocks (a US–China war, climate extremes, an energy crisis) could accelerate or delay the timeline.
- The depth of the curve depends on political leadership. Authoritarian-competent leadership (à la Putin 1999–2005) could shorten the chaos; authoritarian-incompetent leadership (Venezuela) could prolong it.
10. Concluding statement
Five major European countries are simultaneously showing early warning signs of a phase 3 systemic crisis. France will go first, followed by the UK, Italy and Germany almost simultaneously, with Spain last. Every figure in this forecast is anchored to a published source; every prediction is supported by historical precedents from five continents and five decades.
This is not certainty — it is a pattern. Patterns can be broken by human action, external factors or exceptional leadership. But patterns can also come to pass. Anyone reading this forecast can act. Anyone who acts can still break the pattern. The choice is now.
The question for every reader is the same: which country do you want in 2035, and what will you do between now and then to get there?
Sources — consolidated overview
Fiscal data. Eurostat euro-indicators 22 April 2026 · Bundesbank 31 March 2026 — German debt at 63.5% · German Federal Ministry of Finance DBP 2026 · ONS Public Sector Finances May 2026 · OBR Brief Guide April 2026 · INSEE June 2026 — French debt at 117.5% in Q1 2026 · Brussels Signal March 2026 — French debt at €3,460bn · EU Council June 2026 — Spanish fiscal position · Banco de España 2025 · EC Spring Forecast Italy May 2026 · Reuters 2 March 2026 — Italy misses deficit targets · Eunews 22 April 2026 — Italian debt at 137.1% · Staatsverschuldung.de 2026 — Germany’s implicit debt at 454% · Bruegel October 2025 · Deutsche Welle March 2025 — debt brake broken
Unemployment and industry. INSEE May 2026 — French unemployment Q1 2026 · ONS NEET bulletin May 2026 — 1,012,000 young people · Reuters February 2026 — UK youth unemployment at a ten-year high · ISTAT July 2026 — Italian unemployment May 2026 · INE July 2025 — Spanish unemployment Q2 2025 · Reuters August 2025 — German industry loses 250,000 jobs · Reuters June 2026 — VW to cut up to 100,000 jobs · The Guardian July 2026 — German car industry warns of collapse · OFCE 2024 — French industry lost 900,000 jobs from 2000–2021
Political polling. Reuters November 2025 — Bardella leads presidential polling · BritPolls May 2026 — Reform UK 27.6% · The Spanish Eye June 2026 — PP+Vox reach 194 seats · Reuters 14 July 2026 — Meloni loses parliamentary vote · NYT 23 March 2026 — Italy rejects Meloni’s justice reform · Le Monde February 2026 — French 2026 budget delayed by 40 days
Historical precedents. Federal Reserve Bank of St Louis — Russian GDP loss of 44% from 1989–1998 · World Bank — Argentina Crisis and Poverty 2003 · Brookings — analysis of the 2001 Argentine crisis · World Bank historical GDP per capita data · OECD Economic Surveys South Africa 2025 · Skocpol — States and Social Revolutions (1979) · Goldstone — Revolution and Rebellion in the Early Modern World (1991)
All figures verified through primary sources up to 18 July 2026. Recalibrate if sources change or new data releases become available.
Related reading
- The Dutch Revolution — forecast 2028–2055 — the Dutch companion article
- They already know. And they do nothing. — on the same administrative paralysis
- Deciding without prospects — GDP lies — the fiscal correction method
- Edition 2 — Tax policy — the broader fiscal framework
- Germany edition — why the German curve is also our curve