The fenced dressing-up economy
How the Netherlands is losing its productive core and why Brussels builds walls instead of repairing the core.
By Jacobus van Merksteijn · Palma · 3 August 2026
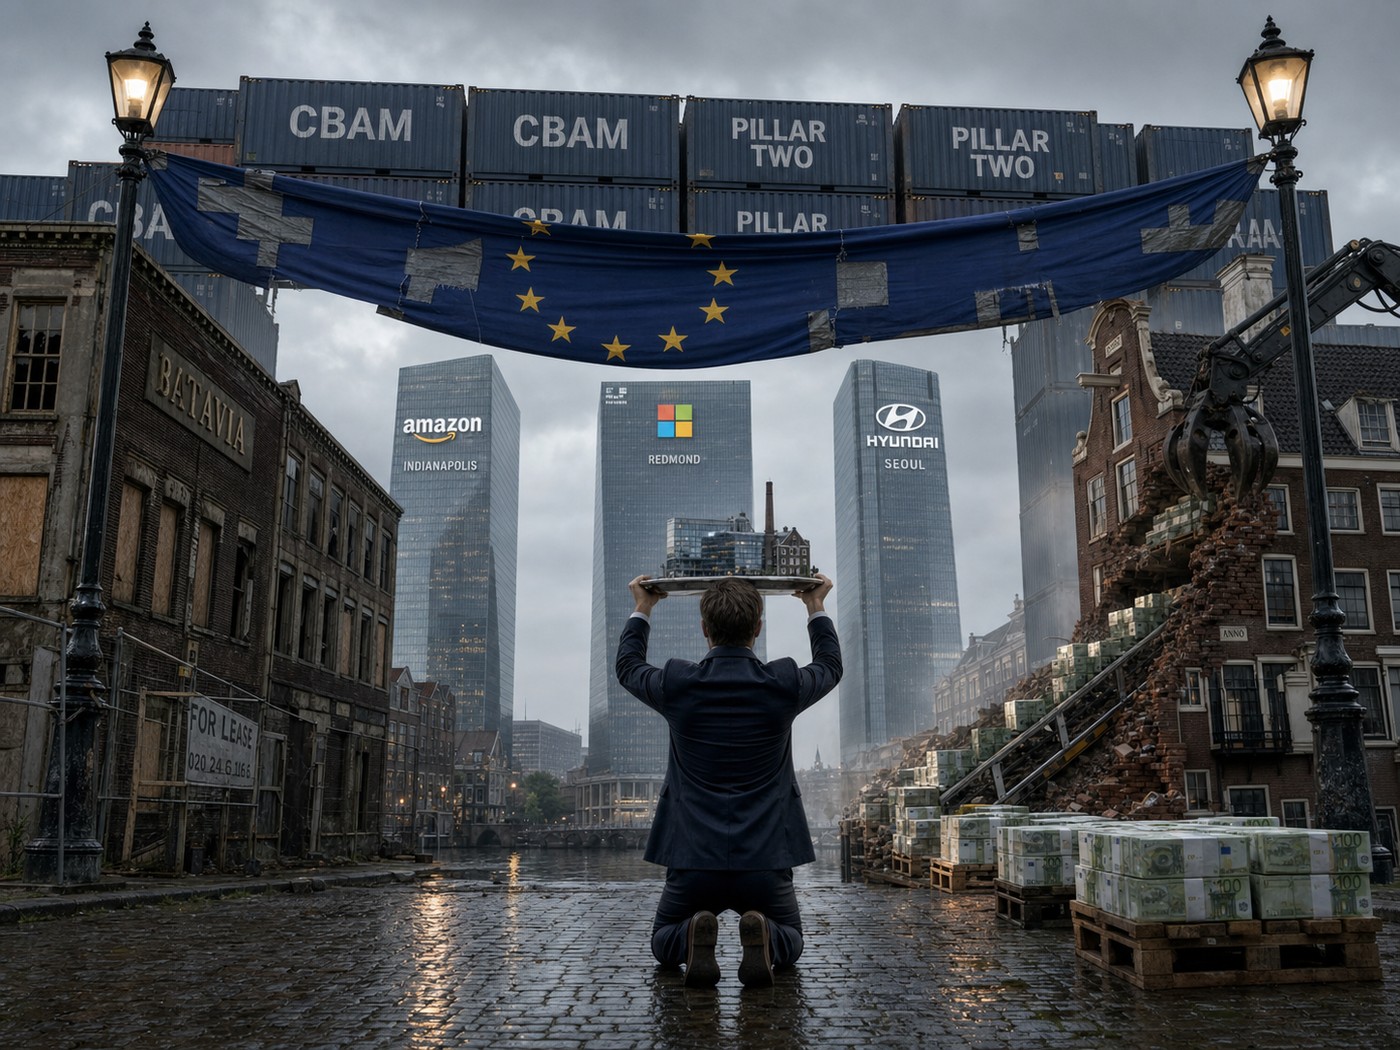
The Dutch economy grew by 0.4 percent in the second quarter of 2026, according to Statistics Netherlands (CBS). CBS chief economist Peter Hein van Mulligen called the figure "not bad" in remarks to ANP. What he did not mention is that every percentage point of GDP growth in this composition pushes the net external productive core of the Netherlands further down. We grow as a shopping basket, we shrink as a production machine. That is not an accident. That is a systematic pattern, and current policy — from The Hague and from Brussels — is precisely designed to keep that pattern in place.
The five layers that GDP conceals
What GDP measures is not what a country earns. To see what we structurally produce, you have to look through five layers:
- GDP — official expenditure, including accounting fictions and government consumption.
- GNP — GDP minus imputed rent, FISIM, SPE flow-through, R&D capitalisation and other imputations. In the Netherlands roughly 0.677 × GDP, calibrated via the debt-ratio conversion 44% GDP → 65% GNP.
- NPK (Netherlands Production Core) — GNP minus the entire collective sector: government, care, social affairs, police and municipalities. In CBS figures 44.4% of GDP = €498.5bn (2024). What is left produces real goods and services for citizens.
- NTPK (Netherlands Total Production Core) — the export-oriented production core after α and τ filters, including foreign firms on Dutch soil.
- NEPK (Netherlands Economic Production Core) — the production core in Dutch capital. NEPK = NTPK × φ, with φ = 0.744 (CBS 85821NED 2023).
In July 2026 the openvizier recalculation of NEPK came out at 2.95% of GDP — already below the critical 3% threshold. At the start of 2026 the figure stood at 4.20%. Q3 2026 is expected to come out between 2.70% and 2.95%, with a central point around 2.83% after processing four confirmed takeovers of Dutch firms by foreign parties in the last three weeks.
The five layers — Q2 2026 as a percentage of GDP
Source: CBS 85879NED (GDP Q2), 85869NED, 85882NED, 85968NED, 85821NED — Appendix B of this article.
Why GDP growth is at the same time an NEPK decline
The Q2 2026 growth comes from household consumption (+0.5%), government consumption (+0.4%) and a negative trade balance (imports 1.4% > exports 1.2%). That is not production growth; it is expenditure growth. And every extra euro of expenditure by government or households raises GDP but not necessarily the productive core.
The cascade shows what happens: GDP and GNP grow mechanically with expenditure. NPK grows marginally because government expenditure rises as fast as the rest. NTPK and NEPK fall, because the export-oriented production in Dutch hands does not move with domestic consumption. This is the pattern of a dressing-up economy: the country spends ever more money on itself, while ever less of what it produces actually stays in its own capital.
NEPK trajectory: from 9% (2000) to 2.83% (Q3 2026 projection)
Anchor points: 9% (2000, cited in article), 4.20% (start 2026, openvizier projection), 2.95% (July 2026, recalculation), 2.83% (Q3 2026 central, band 2.70–2.95%). Dashed projection 2028–2033 follows the conclusion in this article: NEPK falls through the 2% threshold between 2028 and 2033. Source: openvizier.org — In the end we have nothing left (20 July 2026).
Why this pattern is standard under centre-left governments
The dressing-up economy is not a personal failure of this cabinet. It is the logical outcome of a centre-left policy package with three standard components:
- Financing the social contract from consumption instead of from production — redistribution via benefits, care allowances and public services drives up GDP, but pushes α (productive core fraction) down and τ (tax burden) up.
- Open capital market without ownership lock — firms may be freely sold to foreign parties, including strategic ones. Every takeover lowers φ.
- Heavy control system — labour law, environmental permits, procurement pressure, ESG reporting, AI Act, CSRD, CSDDD. Startups do not make it, entrepreneurs leave for Belgium or Germany, foreign buyers walk off with the mature firms.
Each of the three is defensible on its own. Together they produce the dressing-up economy. Right-liberal cabinets have not reversed the NEPK decline — they have only adjusted the pace. The trend from 9% NEPK in 2000 to 2.95% in July 2026 runs through PvdA-VVD, CDA-PvdA, VVD-D66-CDA-CU and the present cabinet. It is a 26-year systemic movement.
The extension strategy: building walls to avoid repairing the core
When one's own production core is no longer competitive, a government can do two things: strengthen the core, or make the outside world more expensive until the own position fits again. The Netherlands and Brussels structurally chose the second.
1. Global minimum tax (OECD Pillar Two, 15%)
Countries that taxed lower — Ireland, Singapore, Hungary, Cyprus — must move up to Dutch levels. Net effect for the Netherlands: the τ gap with competitors narrows without the Netherlands having to lower its own τ. What we are too expensive at is not repaired; competitors are artificially made equally expensive. NEPK effect for the Netherlands: zero. NEPK effect for Ireland and Singapore: negative.
2. CO2 border levy (CBAM)
Fully operational since 1 January 2026. Importers of steel, cement, aluminium, fertiliser, hydrogen and electricity pay the ETS price on entry into the EU. The official motivation is climate; the actual working is protection of expensive European production against cheaper Chinese, Indian and Turkish suppliers. Our α stays low, but the competitor is made more expensive. Side effect: the steel price within NL rises, downstream industry becomes more expensive, export competitiveness comes under pressure. The wall eats what it protects.
3. Import levies on China and the US
EU anti-dumping tariffs of 17–38% on Chinese electric cars (2024), countermeasures against Trump-II tariffs (2025–2026). Aim: keep the domestic consumer price up so that European producers, having become too expensive through high τ and low α, can keep up. Effect on the citizen: higher price, less real consumption. Effect on α: unchanged. Effect on E_tv: apparently positive due to price protection, structurally zero.
4. Regulatory export (CSRD, CSDDD, AI Act, ETS-2)
Every firm that wants to supply the EU market must meet EU reporting and compliance requirements. Aim: lift the Dutch and European compliance cost level to global level so that NL firms are no longer disadvantaged. Effect: α stays low, τ base stays high, and the rest of the world becomes slower.
The four walls and their effect on the NEPK parameters
Source: EU regulations (CBAM, CSRD, CSDDD, AI Act, ETS-2), OECD Pillar Two, ACM. Interpretation: openvizier — this article §"The extension strategy".
Not a developing country but a serf-state
There is a misunderstanding worth refuting. The Netherlands is not sliding down to the level of a developing country. Developing countries actually see their productive core rise. Vietnam 1995, South Korea 1970, Ghana 2025: NEPK low but heading up, capital and decision-making power move inward, the population gets its own production power. We move in exactly the opposite direction.
The Netherlands has become a serf-state. The term is hard but mathematically correct: our production core is heading towards zero, our wage comes from operating foreign infrastructure on our own soil, our decision-making power lies in Indianapolis, Redmond, Seoul and Palo Alto. Eli Lilly builds in Katwijk for three billion dollars; the Netherlands supplies the land, the permit, the water, the power grid, and thirty-one million euros of traffic measures. In exchange we get contract labour. The profit goes to Indianapolis. Microsoft buys thirty-seven hectares in Middenmeer; the Netherlands supplies land, power capacity from the already overloaded grid, cooling water. We get jobs for security, canteen and garden maintenance. The compute revenue goes to Redmond.
Batavia Biosciences closed; the twelve-thousand-square-metre building waits for a foreign user who will do something with the infrastructure the Dutch built. Solvinity — the company behind DigiD — is going to Kyndryl. The identity infrastructure of every Dutch citizen will shortly be managed from New York.
The paw-giving has become politically visible. The provincial council of South Holland voted on 9 July 2026 by 47 to 5 for thirty-one million euros of traffic measures so as not to scare Eli Lilly away. The cabinet calls foreign investment "the best investment climate in Europe". Brussels builds CBAM and Pillar Two to convince foreign owners that the EU enclosure protects them, provided they stay. Every takeover is presented as "confidence in the Netherlands".
The treat is: jobs, tax revenue on land and wages — not on profit, because profit goes to headquarters —, infrastructure subsidies from EU funds, and a brief GDP boost from the construction phase. As soon as the investor decides to produce more efficiently somewhere else, he closes and the Netherlands is left with empty buildings. Like Batavia now. Like Halix now. Like Pharming shortly.
This is a structurally different layer from the dressing-up economy. The dressing-up economy is spending-without-producing. The serf-state is working-for-others-on-one's-own-soil. They reinforce each other: the dressing-up economy delivers the τ with which we build infrastructure for foreign owners, and the serf-state delivers the jobs that make the dressing-up expenditure financeable. Together we are a country that sells itself off and calls that growth.
Serf-state mechanism: what NL supplies vs. what flows abroad
Sources: NRC 29–30 July 2026, IO+/PropertyNL 28–29 July 2026, MarketScreener 30–31 July 2026, Studio Schumpeter 28 July 2026, Consultancy.nl July 2026, ACM concentration notification 29 July 2026.
Why this pattern does not hold
A wall you build to maintain your position raises the cost base of your own consumers and lowers competitive pressure on your own producers. CBAM raises the steel price in NL. Pillar Two raises the tax burden in the low-tax part of the EU. Import levies raise the consumer price. Regulatory export raises compliance costs worldwide — and thus also in the EU itself.
Every wall you erect speeds up the α decline instead of reversing it. The dressing-up economy then becomes a fenced dressing-up economy: the same movement, but with a wall around it that has to grow higher as the core grows weaker. At some point the wall becomes so high it can no longer be seen over by its own consumers and producers. At that moment the system breaks.
The NEPK does not fall because the Netherlands has bad luck or because the world does this to us. The NEPK falls because the policy package — redistribution + open capital market + heavy compliance + defensive walls — is precisely designed to remain what it is. Every step the government now takes reinforces the pattern.
The only way out: core strengthening instead of wall-building
Openvizier names three structural reversals that must happen at the same time:
- GNP as a second denominator alongside GDP — a dashboard that measures productive core rather than expenditure, so that every policy decision is judged on its NEPK effect.
- φ-lock on strategic sectors — a constitutional floor for Dutch ownership in defined critical sectors (biotech, chemistry, energy, defence, agri/food, digital), on Canadian and Singaporean lines.
- Zero-base legislative review — every policy dossier gets one annual zero-base cycle with 1/5 convergence towards a learning reference, carried out by high-knowledge teams at market-based remuneration.
Without these three, every government — left or right — is a dressing-up government. Without these three, every Brussels wall is an interim solution until the next one. And without these three, the NEPK of the Netherlands falls through the 2% threshold between 2028 and 2033, below which the social contract is mathematically no longer financeable from its own production.
Closing
The economy has grown as a shopping basket. As a production machine it has shrunk. We have become a dressing-up economy, and Brussels builds the enclosure. What remains is the question of how long we can convince ourselves that a wall is productivity.
Appendix A — Figures base
| Item | Value | % GDP | Source |
|---|---|---|---|
| GDP 2024 (provisional) | €1,122.5bn | 100.00% | CBS 85865NED |
| Imputed rent owner-occupied housing (68A) | €54.4bn | 4.84% | CBS 85869NED |
| FISIM (IGDFI production) | €22.0bn | 1.96% | CBS 85882NED |
| Total government expenditure S13 | €498.5bn | 44.4% | CBS 84116NED / 85968NED |
| GDP growth Q2 2026 q-o-q | +0.4% | — | CBS 85879NED flash |
| GDP growth Q2 2026 y-o-y | +1.3% | — | CBS 85879NED |
| Foreign control of NL business sector (2023) | 25.6% | — | CBS 85821NED |
| φ = 1 − foreign control | 0.744 | — | derived from CBS 85821NED |
| NEPK start 2026 | 4.20% | 4.20% | openvizier.org |
| NEPK July 2026 | 2.95% | 2.95% | openvizier.org recalculation |
| NEPK Q3 2026 (central projection) | 2.83% | 2.83% | model, band 2.70–2.95% |
Appendix B — Cascade Q1–Q3 2026 (index GDP Q1 = 100)
| Layer | Formula | Q1 2026 | Q2 2026 | Q3 2026 (proj.) |
|---|---|---|---|---|
| GDP | official | 100.00 | 100.40 | 100.80 |
| GNP | = 0.677 × GDP | 67.69 | 67.96 | 68.23 |
| NPK | = GNP − 44.4% × GDP | 23.28 | 23.37 | 23.47 |
| NTPK | = NEPK / φ | 5.65 | 3.98 | 3.88 |
| NEPK | = GDP × E_tv × α × (1−τ) × φ | 4.20 | 2.96 | 2.85 |
Sources
- CBS Statline 85865NED — Composition of gross domestic product (GDP), national accounts
- CBS Statline 85869NED — Supply and use, product groups (code B000083 = 68A Imputed rent owner-occupied housing)
- CBS Statline 85882NED — Current transactions per sector (Production of IGDFI)
- CBS Statline 84116NED / 85968NED — Government expenditure S13
- CBS Statline 85821NED — Foreign control of the Dutch business sector, 2023
- CBS Statline 85879NED — GDP, production and expenditure, quarterly (flash Q2 2026, 30 July 2026)
- CBS news release 31 July 2026 — Economic picture somewhat more negative in July (Business Cycle Clock)
- NRC Handelsblad, 29 July 2026 — Pension funds behind sale of DigiD to Americans
- NRC Handelsblad, 30 July 2026 — Pharmaceutical Eli Lilly faces battle with local residents over building mega-factory in Katwijk
- ACM concentration notification 29 July 2026 — Eurazeo Bright Bidco / Rotla
- MarketScreener, 30 July 2026 — Deals of the day: Arcadis, WSP Global
- MarketScreener, 31 July 2026 — Orkla buys Dutch confectionery maker for 207 million euros
- Consultancy.nl July 2026 — Valid sells managed services arm to DATAGROUP
- IO+ / PropertyNL, 28–29 July 2026 — Microsoft buys 37.5 ha in Middenmeer
- Reuters, 28 July 2026 — Dutch grid operator Enexis gets €500 million financing from EIB
- Studio Schumpeter, 28 July 2026 — Investments in sustainability (Neste, HyStock)
- Vraag & Aanbod / Nevi PMI July 2026, 3 August 2026 — Strong start to second half of 2026
- openvizier.org — In the end we have nothing left, 20 July 2026 (NEPK recalculation 2.95%)
- openvizier.org — Honesty makes governance possible, 20 July 2026 (PBW formula and debt layers)
- openvizier.org — Deciding without a view, 20 July 2026 (sunset clause)
- OECD Trade in Value Added (TiVA) 2023 — Export-VA Netherlands 36.1%
- OECD Revenue Statistics 2024
- World Bank Industry (including construction) value added (% of GDP) — Netherlands 2024
Jacobus van Merksteijn
Palma
Editor-in-chief of The Open Visor. Entrepreneur, developer of industrial and governance innovations (Carbon-Alert Ltd, TerraClean Ltd, GuardSkin Ltd). Writes on economic, ecological and political systems questions from experience with the Brussels and The Hague decision-making machine.